Polyoxymethylene Pom Market
Polyoxymethylene Pom Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711751 | Published On : November 15, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Polyoxymethylene Pom Market Size
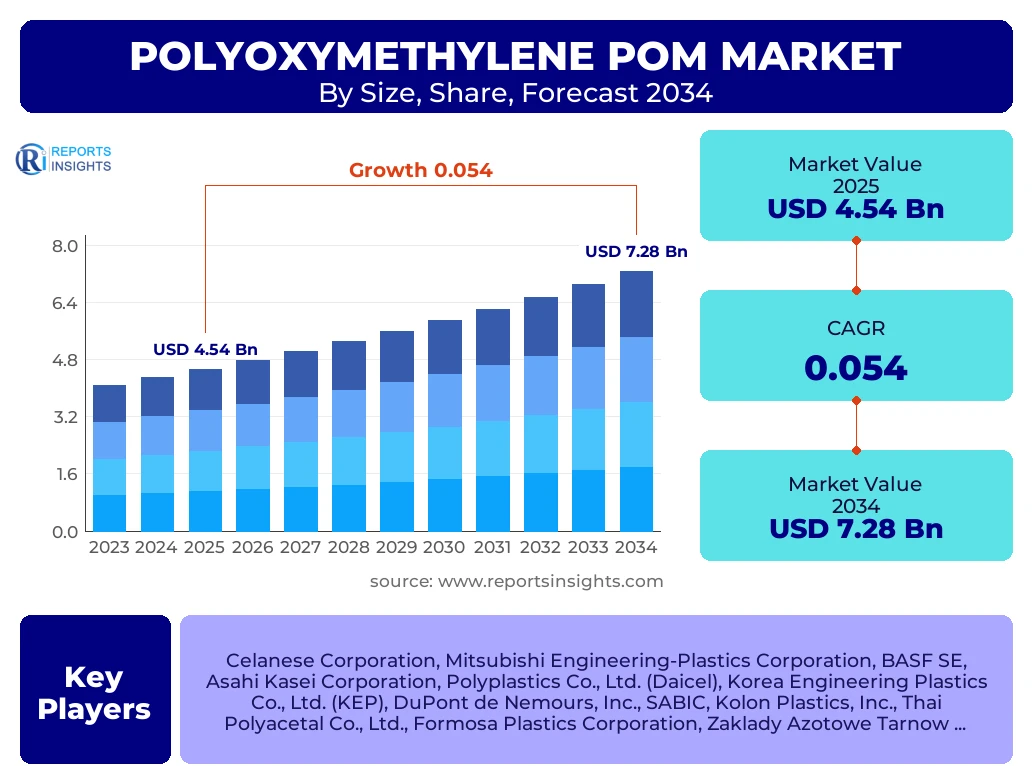
According to Reports Insights Consulting Pvt Ltd, The Polyoxymethylene Pom Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.4% between 2025 and 2034. The market is estimated at USD 4.78 Billion in 2026 and is projected to reach USD 7.28 Billion by the end of the forecast period in 2034.
Key Polyoxymethylene Pom Market Trends & Insights
The Polyoxymethylene (POM) market is currently undergoing a structural transformation driven by the global transition toward high-performance engineering thermoplastics that offer a combination of high stiffness, low friction, and excellent dimensional stability. Market intelligence suggests that the rapid electrification of the automotive sector and the miniaturization of electronic components are the primary catalysts for innovation in POM formulations. Regional insights indicate that manufacturing hubs in the Asia-Pacific region are increasingly adopting advanced POM grades for precision machinery, while European and North American markets are prioritizing sustainable and recycled POM variants to comply with stringent environmental mandates. Furthermore, competitive benchmarking reveals a shift toward specialized copolymer variants that offer superior thermal stability compared to traditional homopolymers, particularly in demanding industrial environments.
- Largest Region: Asia-Pacific, driven by massive industrial manufacturing in China, India, and South Korea, currently holds the dominant market share of over 45%.
- Fastest Growing Region: Southeast Asia (ASEAN countries) is emerging as the fastest-growing sub-region due to the relocation of electronics manufacturing bases and rising domestic automotive production.
- Largest Segment by Type: POM Copolymer remains the largest segment in terms of market share, preferred for its resistance to thermal degradation and high alkaline resistance.
- Largest Segment by Application: The Automotive segment continues to lead the market, specifically in fuel system components, fasteners, and interior trim mechanisms.
Key Takeaways Polyoxymethylene Pom Market Size & Forecast
Analysis of current market trajectories and stakeholder inquiries highlights a significant emphasis on the replacement of metal components with POM in various engineering applications to achieve weight reduction and cost efficiencies. The market size forecast reflects a steady upward momentum, supported by the expansion of the medical device industry where POM is utilized for its biocompatibility and resistance to sterilization processes. Stakeholders are increasingly focused on the volatility of raw material prices, particularly formaldehyde, and how it influences the final price point of POM resins. The forecast suggests that while traditional applications in industrial machinery remain stable, the growth frontier lies in advanced consumer electronics and renewable energy infrastructure components.
- Leading Country: China is the global leader in both production capacity and consumption, accounting for a significant portion of the global demand for POM resins.
- Technological Shift: There is a clear trend toward the development of low-emission POM grades to meet Indoor Air Quality (IAQ) standards in automotive interiors.
- Supply Chain Dynamics: Integration of production facilities is becoming a key strategy for major players to mitigate the impact of fluctuating methanol and formaldehyde costs.
- High-Growth Application: The healthcare sector is identified as a high-margin opportunity area, especially for POM used in drug delivery systems such as insulin pens and inhalers.
Polyoxymethylene Pom Market Drivers Analysis
The primary drivers of the Polyoxymethylene market are rooted in the material's unique physical properties which make it indispensable for high-precision engineering. As industries seek to enhance operational efficiency and reduce energy consumption, the demand for lightweight yet durable materials like POM has intensified. The transition toward electric vehicles (EVs) is a critical driver, as POM is used extensively in thermal management systems and battery housing components where chemical resistance and mechanical strength are paramount.
Additionally, the global push for automation in manufacturing has increased the demand for POM-based gears, bearings, and conveyor links. These components benefit from the low coefficient of friction and high wear resistance of POM, leading to longer service lives and reduced maintenance costs for industrial machinery. The rise of the middle class in emerging economies is also fueling the consumption of consumer goods and appliances, many of which utilize POM for internal moving parts.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Automotive Lightweighting & EV Expansion | +1.8% | Global (Strongest in Europe and China) | 2025–2034 |
| Miniaturization of Electronic Components | +1.2% | Asia-Pacific (South Korea, Taiwan) | 2026–2030 |
| Growth in Medical Device Manufacturing | +0.9% | North America and Germany | 2025–2034 |
| Industrial Automation & Precision Engineering | +1.1% | Japan and Germany | 2027–2034 |
Polyoxymethylene Pom Market Restraints Analysis
Despite its robust growth profile, the Polyoxymethylene market faces several restraints, primarily concerning raw material price volatility and environmental regulations. The production of POM is highly dependent on the availability and pricing of methanol and formaldehyde. Any disruption in the petrochemical supply chain or sudden spikes in natural gas prices can significantly impact the production cost of POM, making it less competitive against alternative engineering plastics like PBT or Nylon.
Furthermore, the environmental impact of POM manufacturing, particularly the handling of formaldehyde which is a known carcinogen in its gaseous state, subjects producers to stringent health and safety regulations. These regulations often necessitate significant capital investment in emission control technologies, which can squeeze profit margins. Additionally, the inherent difficulty in recycling POM compared to other thermoplastics poses a challenge in a global economy increasingly focused on circularity and zero-waste initiatives.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Volatility in Methanol Feedstock Prices | -0.6% | Global | 2025–2034 |
| Strict Environmental & Safety Regulations | -0.4% | North America and Europe | 2025–2029 |
| Competition from Alternative Engineering Plastics | -0.3% | Global | 2028–2034 |
Polyoxymethylene Pom Market Opportunities Analysis
The evolution of the Polyoxymethylene market is creating significant opportunities in high-technology sectors and sustainable material development. One of the most promising opportunities lies in the development of bio-based or recycled POM resins. As major OEMs in the automotive and consumer electronics sectors commit to carbon neutrality, the demand for "green" POM is expected to surge, providing a first-mover advantage to companies that can successfully commercialize bio-formaldehyde-derived resins.
Another major opportunity exists in the 3D printing and additive manufacturing sector. While traditionally difficult to print due to its high crystallinity and warping issues, specialized POM filaments and powders are being developed for functional prototyping and small-batch production of industrial parts. Moreover, the expansion of the aerospace and defense sectors in emerging markets provides a niche but high-value opportunity for high-performance POM grades that can withstand extreme temperature fluctuations and mechanical stress.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Bio-based POM Development | +1.5% | Europe and North America | 2027–2034 |
| Additive Manufacturing Applications | +0.7% | United States and Germany | 2026–2032 |
| Aerospace and Defense Components | +0.5% | Global (India, USA) | 2029–2034 |
Polyoxymethylene Pom Market Challenges Impact Analysis
The Polyoxymethylene market is currently grappling with challenges related to technical limitations and geopolitical tensions. POM is sensitive to acid hydrolysis and UV radiation, which limits its use in certain outdoor applications without expensive stabilization additives. Overcoming these chemical limitations while maintaining the material's cost-effectiveness remains a significant technical hurdle for R&D departments across the industry.
Geopolitical challenges also play a major role, as the concentration of production capacity in certain regions makes the supply chain vulnerable to trade disputes and tariffs. The energy crisis in various parts of the world has also led to fluctuating operational costs for POM manufacturing plants, which are energy-intensive. Furthermore, the market must address the "substitution threat" from advanced composites and ceramics in ultra-high-performance applications where POM might reach its mechanical limits.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Sensitivity to UV and Acidic Environments | -0.5% | Global | Continuous |
| Geopolitical Trade Barriers | -0.4% | China, USA, and EU | 2025–2030 |
| Energy-Intensive Production Processes | -0.3% | Europe | 2025–2028 |
Polyoxymethylene Pom Market - Updated Report Scope
This report provides a comprehensive analysis of the global Polyoxymethylene (POM) market, covering historical data from 2020 to 2024 and providing detailed forecasts through 2034. The scope includes an in-depth examination of the two primary types of POM—Homopolymer and Copolymer—across various industrial applications including automotive, electrical and electronics, industrial machinery, and medical technology. The analysis extends to regional market dynamics, identifying key growth drivers, regulatory landscapes, and competitive positioning of the top market participants. By integrating quantitative data with qualitative insights, this report serves as a strategic tool for stakeholders to navigate the complexities of the engineering plastics industry and identify high-yield investment opportunities.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 4.54 Billion |
| Market Forecast in 2034 | USD 7.28 Billion |
| Growth Rate | 5.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Celanese Corporation, Mitsubishi Engineering-Plastics Corporation, BASF SE, Asahi Kasei Corporation, Polyplastics Co., Ltd. (Daicel), Korea Engineering Plastics Co., Ltd. (KEP), DuPont de Nemours, Inc., SABIC, Kolon Plastics, Inc., Thai Polyacetal Co., Ltd., Formosa Plastics Corporation, Zaklady Azotowe Tarnow, Shenhua Ningxia Coal Industry Group Co., Ltd., Yunnan Yuntianhua Co., Ltd., Henan Energy and Chemical Industry Group Co., Ltd., BlueStar New Chemical Materials, PolyMirae, LyondellBasell Industries N.V. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Polyoxymethylene market is segmented based on chemical structure, grade characteristics, and end-use applications to provide a granular view of the industry. The distinction between Homopolymer and Copolymer is fundamental; Homopolymers generally offer higher tensile strength and stiffness, whereas Copolymers provide better long-term thermal stability and chemical resistance. Grade-based segmentation reveals a growing demand for reinforced POM, often blended with glass fibers or carbon fibers, to meet the requirements of heavy-duty industrial and automotive applications. Application-wise, the market is diversifying beyond its traditional strongholds in automotive and electronics into specialized medical and renewable energy components, reflecting the material's versatile performance profile.
- By Type
- POM Copolymer: Dominates the market due to superior processing windows and resistance to thermal-oxidative degradation.
- POM Homopolymer: Preferred in applications requiring maximum mechanical stiffness and fatigue resistance.
- By Grade
- Standard Grade: Broadly used for general-purpose injection molding and extrusion.
- Reinforced Grade: Includes glass-filled and mineral-filled POM for enhanced structural integrity.
- Lubricated Grade: Formulated with PTFE or silicone to further reduce friction and wear.
- Others: Includes impact-modified and UV-stabilized variants.
- By Application
- Automotive: The largest end-user, utilizing POM in fuel tank modules, door lock systems, and seat belt components.
- Electrical & Electronics: Essential for precision parts like printer gears, smartphone components, and circuit breaker housings.
- Industrial Machinery: Widely used in materials handling, heavy-duty gears, and fluid handling systems.
- Consumer Goods: Found in household appliances, sporting goods, and apparel fasteners (zippers).
- Medical: A high-growth segment focusing on disposable medical devices and diagnostic equipment.
Regional Highlights
- Asia-Pacific: This region is the global powerhouse of the POM market, with China serving as the largest producer and consumer. The rapid expansion of the domestic automotive industry and the concentration of the world's electronics manufacturing in this region drive sustained demand.
- Europe: Europe is a leader in the development of high-performance and sustainable POM grades. Germany remains the central hub, supported by its world-class automotive and industrial machinery sectors that demand premium-grade engineering plastics.
- North America: The market is characterized by high demand in the medical and aerospace sectors. The United States is seeing a resurgence in domestic manufacturing, which is boosting the consumption of POM in precision engineering applications.
- Latin America: Growth is primarily driven by the expanding automotive assembly plants in Mexico and the increasing industrialization in Brazil.
- Middle East & Africa: While currently a smaller market, the region is seeing growth in infrastructure projects and the emergence of localized consumer goods manufacturing.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Polyoxymethylene Pom Market.- Celanese Corporation
- Mitsubishi Engineering-Plastics Corporation
- BASF SE
- Asahi Kasei Corporation
- Polyplastics Co., Ltd.
- Korea Engineering Plastics Co., Ltd. (KEP)
- DuPont de Nemours, Inc.
- SABIC
- Kolon Plastics, Inc.
- Thai Polyacetal Co., Ltd.
- Formosa Plastics Corporation
- Zaklady Azotowe Tarnow
- Shenhua Ningxia Coal Industry Group Co., Ltd.
- Yunnan Yuntianhua Co., Ltd.
- Henan Energy and Chemical Industry Group Co., Ltd.
- BlueStar New Chemical Materials
- PolyMirae
- LyondellBasell Industries N.V.
Frequently Asked Questions
What is the difference between POM Homopolymer and POM Copolymer?
POM Homopolymer is made from a single monomer and generally offers higher mechanical strength, stiffness, and impact resistance. POM Copolymer is produced using a comonomer, which provides better resistance to thermal degradation, improved chemical resistance in alkaline environments, and a broader processing window during manufacturing.
Why is Polyoxymethylene extensively used in the automotive industry?
POM is favored in automotive engineering because it can replace metal parts, reducing vehicle weight and improving fuel efficiency. Its excellent creep resistance, low friction, and resistance to fuels and oils make it ideal for fuel system components, door handles, and safety restraint systems.
What are the key factors driving the growth of the POM market in Asia-Pacific?
The growth is primarily driven by the presence of large-scale manufacturing sectors for automobiles and electronics in China, Japan, and South Korea. Additionally, increasing investments in industrial automation and the availability of cost-effective labor and raw materials contribute to the region's market dominance.
What are the environmental concerns associated with POM production?
The main environmental concern is the use and potential emission of formaldehyde during the manufacturing process, which requires strict adherence to safety protocols. Furthermore, as a high-performance thermoplastic, POM is more difficult to recycle through conventional mechanical processes compared to commodity plastics, leading to research into chemical recycling methods.
How is the move toward Electric Vehicles (EVs) impacting the POM market?
The EV transition is positively impacting the market as POM is used in specialized components like battery cooling systems, electrical connectors, and lightweight structural parts. While some traditional internal combustion engine parts may be phased out, the new requirements for EVs offer high-growth opportunities for advanced POM grades.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
