Steel Merchant Rebar Market
Steel Merchant Rebar Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711165 | Published On : October 14, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Steel Merchant Rebar Market Size
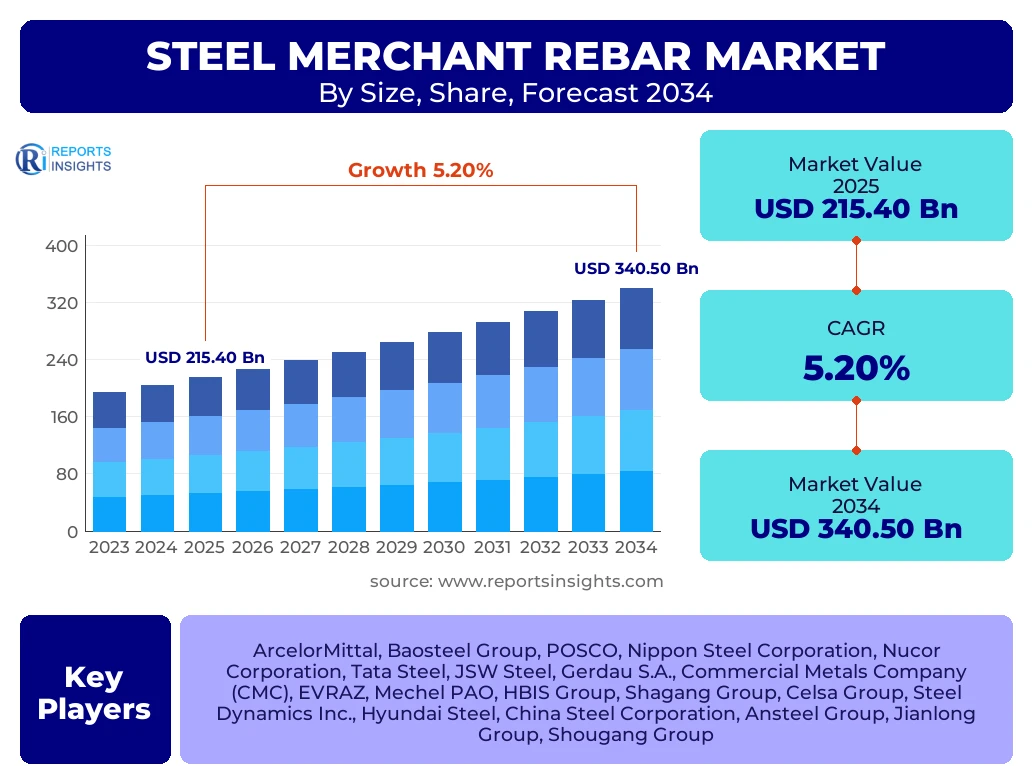
According to Reports Insights Consulting Pvt Ltd, The Steel Merchant Rebar Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.2% between 2025 and 2034. The market is estimated at USD 226.60 Billion in 2026 and is projected to reach USD 340.50 Billion by the end of the forecast period in 2034.
Key Steel Merchant Rebar Market Trends & Insights
The global steel merchant rebar market is undergoing a significant transformation driven by the integration of sustainable manufacturing processes and the escalating demand for high-strength, corrosion-resistant materials in large-scale infrastructure projects. Market participants are increasingly shifting toward Electric Arc Furnace (EAF) technology to reduce carbon footprints, aligning with global net-zero initiatives. Furthermore, the rise of smart cities and the expansion of transportation networks in emerging economies are creating a robust pipeline for rebar consumption. Analysts observe that regional insights point toward a consolidated push for seismic-resistant rebar in earthquake-prone zones, while competitive benchmarking reveals a trend of horizontal integration among top-tier manufacturers to secure raw material supply chains.
- Asia Pacific remains the largest region, accounting for over 50 percent of the global market share, fueled by massive urbanization in China and India.
- The Middle East and Africa is the fastest-growing region, driven by Saudi Arabias Vision 2030 and significant infrastructure investments across the GCC.
- The Infrastructure segment is the largest end-use category, representing the highest share of rebar consumption globally.
- Increasing adoption of Epoxy-coated and Galvanized rebar is a major trend in coastal construction to prevent premature structural failure.
- Digital transformation in supply chain management is enabling real-time tracking of steel shipments, enhancing operational efficiency for distributors.
Key Takeaways Steel Merchant Rebar Market Size & Forecast
The long-term outlook for the steel merchant rebar market remains bullish, supported by a global resurgence in industrial construction and the replacement of aging infrastructure in developed economies. Forecasts indicate that while the residential sector may experience cyclical fluctuations, the non-residential and civil engineering sectors will provide a stable floor for market demand. Strategic shifts toward green steel production are expected to redefine cost structures, as carbon taxes and environmental regulations become more stringent. Stakeholders are focusing on high-grade rebar (such as Grade 60 and Grade 75) to meet the evolving engineering requirements of modern skyscrapers and heavy-duty industrial facilities.
- China continues to be the leading country in both production and consumption, though domestic shifts toward high-quality steel are altering export dynamics.
- India is emerging as a critical growth engine, with the government’s National Steel Policy aiming to significantly increase per capita steel consumption.
- Technological advancements in micro-alloying are allowing manufacturers to produce stronger rebar with less material, optimizing cost-to-performance ratios.
- Sustainable procurement policies in Europe and North America are favoring manufacturers with lower Scope 1 and Scope 2 emissions.
- The market is seeing a rise in pre-fabricated rebar cages, which reduce on-site labor costs and improve construction speed.
Steel Merchant Rebar Market Drivers Analysis
The primary catalysts for the steel merchant rebar market include the global expansion of urban population centers and the subsequent need for housing and commercial spaces. Governments worldwide are prioritizing infrastructure as a means of economic stimulus, leading to massive investments in bridges, tunnels, and dam projects that require enormous volumes of reinforcement steel.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rapid Urbanization in Emerging Economies | +1.8% | India, Southeast Asia | 2025 - 2034 |
| Global Infrastructure Stimulus Packages | +1.5% | United States, EU, China | 2025 - 2030 |
| Demand for Seismic-Resistant Construction | +0.9% | Japan, Turkey, West Coast USA | 2025 - 2034 |
Steel Merchant Rebar Market Restraints Analysis
Market growth is tempered by the extreme volatility of iron ore and scrap steel prices, which complicates long-term budgeting for construction firms. Additionally, the tightening of environmental regulations and the implementation of carbon border adjustment mechanisms are increasing operational costs for traditional blast furnace operators.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Raw Material Price Volatility | -0.7% | Global | Ongoing |
| Stringent Carbon Emission Regulations | -0.5% | European Union, North America | 2026 - 2034 |
Steel Merchant Rebar Market Opportunities Analysis
The transition toward Green Steel presents a massive opportunity for early adopters of hydrogen-based reduction and renewable-powered EAF technology. Furthermore, the growth of the renewable energy sector, specifically wind turbine foundations, creates a niche but high-volume demand for specialized rebar solutions.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adoption of Green Steel Production | +1.2% | Germany, Sweden, USA | 2027 - 2034 |
| Renewable Energy Infrastructure | +0.6% | China, Brazil, Australia | 2025 - 2034 |
Steel Merchant Rebar Market Challenges Impact Analysis
Logistical bottlenecks and trade protectionism remain significant challenges, as tariffs and import quotas disrupt the free flow of steel products across borders. Moreover, the shortage of skilled labor in the construction industry can delay projects, indirectly affecting the demand for rebar in the short to medium term.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Trade Barriers and Tariffs | -0.4% | US-China Trade, EU-Asia Trade | 2025 - 2030 |
| Labor Shortages in Construction | -0.3% | United Kingdom, Germany, USA | 2025 - 2028 |
Steel Merchant Rebar Market - Updated Report Scope
This report provides a comprehensive analysis of the global steel merchant rebar industry, covering production volumes, consumption patterns, and pricing dynamics across all major geographic regions. The scope extends from raw material sourcing to end-use applications in civil engineering, housing, and industrial infrastructure.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 215.40 Billion |
| Market Forecast in 2034 | USD 340.50 Billion |
| Growth Rate | 5.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | ArcelorMittal, Baosteel Group, POSCO, Nippon Steel Corporation, Nucor Corporation, Tata Steel, JSW Steel, Gerdau S.A., Commercial Metals Company (CMC), EVRAZ, Mechel PAO, HBIS Group, Shagang Group, Celsa Group, Steel Dynamics Inc., Hyundai Steel, China Steel Corporation, Ansteel Group, Jianlong Group, Shougang Group |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The steel merchant rebar market is segmented based on manufacturing process, product type, coating technology, and end-use application. Understanding these segments is crucial for stakeholders to identify high-growth niches, such as the surging demand for EAF-produced rebar in Western markets due to sustainability mandates.
- By Process: The Electric Arc Furnace (EAF) segment is gaining significant traction due to its lower carbon footprint compared to traditional Blast Furnaces.
- By Type: Deformed rebar remains the dominant type, preferred for its superior bonding properties with concrete in heavy-load structures.
- By Coating: Epoxy-coated rebar is seeing increased demand in infrastructure projects located in harsh or saline environments to prevent oxidation.
- By End-Use: The Infrastructure segment leads the market, driven by government-funded projects such as highways, railways, and bridges.
- By Grade: High-strength grades (Grade 75 and above) are growing in popularity for high-rise construction to reduce the overall weight of the reinforcement.
Regional Highlights
- Asia Pacific: Holds the largest market share, with China and India acting as the twin engines of growth. China remains the production powerhouse, while India's market is expanding due to the Gati Shakti national master plan.
- North America: Market growth is driven by the Infrastructure Investment and Jobs Act (IIJA), which focuses on refurbishing domestic bridges and transit systems.
- Europe: The region is the leader in the adoption of green steel and low-carbon rebar, influenced by the EU Green Deal and carbon taxation.
- Middle East & Africa: Identified as the fastest-growing region, with mega-projects like NEOM in Saudi Arabia and urban expansion in Egypt creating massive rebar requirements.
- Latin America: Showing steady recovery in the residential sector, particularly in Brazil and Mexico, though economic volatility remains a watch-factor.

Top Key Players
The market research report includes a detailed profile of leading top-wise companies in the Steel Merchant Rebar Market.- ArcelorMittal
- Baosteel Group
- POSCO
- Nippon Steel Corporation
- Nucor Corporation
- Tata Steel
- JSW Steel
- Gerdau S.A.
- Commercial Metals Company (CMC)
- EVRAZ
- Mechel PAO
- HBIS Group
- Shagang Group
- Celsa Group
- Steel Dynamics Inc.
- Hyundai Steel
- China Steel Corporation
- Ansteel Group
- Jianlong Group
- Shougang Group
Frequently Asked Questions
What is the current market size of the Steel Merchant Rebar market?
The Steel Merchant Rebar market is estimated to be valued at USD 215.40 Billion in 2025 and is projected to reach approximately USD 340.50 Billion by 2034.
What is the projected growth rate (CAGR) for the forecast period?
The market is expected to grow at a Compound Annual Growth Rate (CAGR) of 5.2% from 2025 to 2034.
Which region dominates the global Steel Merchant Rebar market?
Asia Pacific is currently the dominant region, accounting for the largest share of global production and consumption, primarily due to rapid industrialization in China and India.
What are the key drivers for market expansion?
The primary drivers include massive government infrastructure investments, rapid global urbanization, and the increasing demand for high-strength steel in seismic zones.
Who are the leading players in the Steel Merchant Rebar industry?
Key market leaders include ArcelorMittal, Nucor Corporation, Baosteel Group, Tata Steel, and POSCO, among others who are focusing on technological innovation and sustainable production.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
