Cold-end Exhaust System Aftermarket Market
Cold-end Exhaust System Aftermarket Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711388 | Published On : October 30, 2026 |
Format : 


 | Author : Ashraf Shehata
Cold-end Exhaust System Aftermarket Market Size
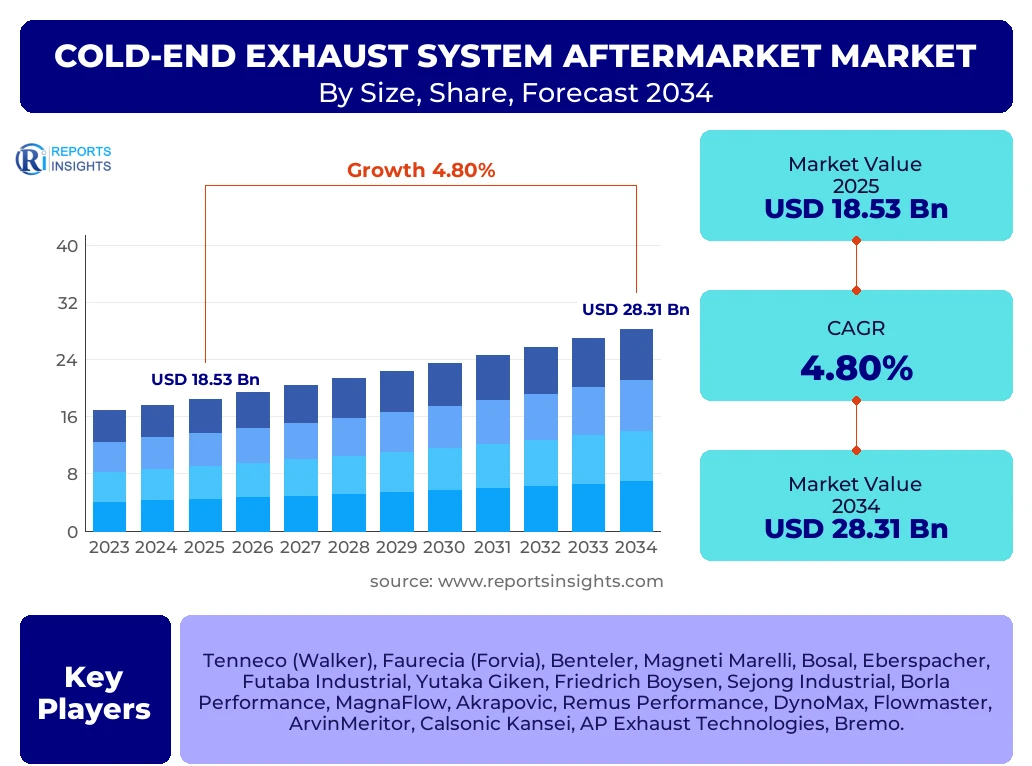
According to Reports Insights Consulting Pvt Ltd, The Cold-end Exhaust System Aftermarket Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 4.8% between 2025 and 2034. The market is estimated at USD 19.42 Billion in 2026 and is projected to reach USD 28.31 Billion by the end of the forecast period in 2034.
Key Cold-end Exhaust System Aftermarket Market Trends & Insights
The global automotive aftermarket for cold-end exhaust systems is undergoing a significant transformation driven by the increasing average age of the global vehicle fleet and a heightening consumer preference for performance-oriented components. Market analysis reveals that while the primary function of the cold-end system—comprising mufflers, resonators, and tailpipes—remains noise attenuation and gas expulsion, modern consumers are increasingly seeking lightweight materials such as high-grade stainless steel and titanium to improve fuel efficiency and aesthetics. Furthermore, the integration of advanced acoustic engineering is allowing manufacturers to offer customizable sound profiles, a trend particularly prevalent in the enthusiast and luxury vehicle segments. Digitalization of the supply chain and the rise of e-commerce platforms have also streamlined the procurement of specific aftermarket parts, reducing lead times for independent repair shops and end-users alike.
- Asia-Pacific is the fastest-growing region due to the massive vehicle parc in China and India and increasing disposable income.
- North America remains the largest region by value, sustained by a high volume of light trucks and SUVs that frequently require exhaust maintenance.
- The Muffler segment holds the largest market share within the cold-end category as it is the component most susceptible to corrosion and internal degradation.
- Stainless steel is rapidly becoming the dominant material segment, replacing traditional aluminized steel due to its superior durability and resistance to road salts.
Key Takeaways Cold-end Exhaust System Aftermarket Market Size & Forecast
The market forecast indicates a steady upward trajectory, supported by the logistical reality that internal combustion engine (ICE) vehicles will remain a dominant presence on roads for the next several decades despite the rise of electric alternatives. Strategic insights suggest that the aftermarket is benefiting from a "repair over replace" consumer mindset in inflationary environments, where vehicle owners opt to maintain existing cars rather than purchasing new ones. The shift toward stringent noise pollution regulations in urban centers is also forcing a replacement cycle for older, non-compliant exhaust systems. Additionally, the proliferation of specialized e-commerce automotive retailers is expanding the reach of premium aftermarket brands into previously underserved rural and emerging markets.
- The United States and China are the leading individual countries, together accounting for over 45 percent of the global market share.
- Passenger cars represent the largest vehicle type segment, though the Heavy Commercial Vehicle (HCV) segment is showing the highest growth rate in specific emerging corridors.
- The average age of vehicles in Europe and North America has reached record highs, directly correlating with increased demand for cold-end system replacements.
- Product innovation focusing on "bolt-on" installation kits is reducing labor costs and driving DIY (Do-It-Yourself) market growth.
- The impact of electric vehicle (EV) penetration is expected to be a long-term challenge but will have a negligible impact on the aftermarket through 2034 due to the massive existing ICE fleet.
Cold-end Exhaust System Aftermarket Market Drivers Analysis
The primary driver of the cold-end exhaust system aftermarket is the aging global vehicle fleet. As vehicles remain in operation longer, the components situated at the rear of the vehicle, which are exposed to moisture, road debris, and corrosive chemicals, inevitably require replacement. Furthermore, the increasing demand for high-performance vehicles and vehicle customization among younger demographics is fueling the sales of premium mufflers and cat-back systems that offer enhanced sound and aesthetic appeal.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Aging Vehicle Fleet Globally | +1.5% | Global (Primarily US & Europe) | 2025 - 2034 |
| Growth in Vehicle Customization Culture | +1.2% | North America, Japan, Germany | 2026 - 2030 |
| Stringent Noise Emission Regulations | +0.9% | European Union, China | 2025 - 2034 |
| Expansion of E-commerce Distribution | +1.2% | India, Brazil, Southeast Asia | 2025 - 2034 |
Cold-end Exhaust System Aftermarket Market Restraints Analysis
The most significant restraint facing the cold-end exhaust system aftermarket is the accelerating transition toward Battery Electric Vehicles (BEVs). Since BEVs do not possess internal combustion engines or exhaust systems, the long-term total addressable market is under threat. Additionally, the increasing quality of OEM stainless steel components in modern ICE vehicles is extending the lifespan of original parts, thereby delaying the first aftermarket replacement cycle.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Penetration of Electric Vehicles | -1.1% | China, Norway, California (US) | 2028 - 2034 |
| Volatility in Raw Material Prices (Steel) | -0.6% | Global | 2025 - 2027 |
| Increased Longevity of OEM Components | -0.4% | Global | 2025 - 2034 |
Cold-end Exhaust System Aftermarket Market Opportunities Analysis
There is a substantial opportunity in the development of lightweight, eco-friendly materials that can assist in overall vehicle weight reduction for hybrid vehicles. Furthermore, the growth of the logistics and e-commerce sectors is increasing the mileage of Light Commercial Vehicles (LCVs), creating a high-frequency replacement market for exhaust components in fleet operations. Manufacturers who specialize in corrosion-resistant coatings for harsh climates also stand to gain significant market share.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Hybrid Vehicle Optimized Exhausts | +0.8% | Japan, European Union | 2026 - 2034 |
| Fleet Maintenance Contracts (LCVs) | +1.3% | India, China, USA | 2025 - 2034 |
| Advanced Coating Technologies | +0.5% | Russia, Canada, Nordic Countries | 2027 - 2034 |
Cold-end Exhaust System Aftermarket Market Challenges Impact Analysis
The market faces challenges from the proliferation of counterfeit and low-quality components that undermine the pricing power of established brands. Additionally, the complexity of modern exhaust designs, which often include integrated sensors and complex hangers, makes it difficult for smaller aftermarket players to produce compatible parts without significant investment in R&D and precision manufacturing.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Counterfeit Product Proliferation | -0.7% | Southeast Asia, Middle East | 2025 - 2034 |
| Technical Complexity of Modern Systems | -0.5% | Global | 2026 - 2034 |
| Supply Chain Disruptions | -0.3% | Global | 2025 - 2026 |
Cold-end Exhaust System Aftermarket Market - Updated Report Scope
This report provides a comprehensive analysis of the cold-end exhaust system aftermarket, covering all essential components that reside after the catalytic converter. The scope encompasses detailed financial forecasting, technological evolution, and competitive landscape mapping. It examines the market through various lenses including vehicle type, material composition, and distribution channels, ensuring a 360-degree view of the industry dynamics from 2025 to 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 18.53 Billion |
| Market Forecast in 2034 | USD 28.31 Billion |
| Growth Rate | 4.8% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Tenneco (Walker), Faurecia (Forvia), Benteler, Magneti Marelli, Bosal, Eberspacher, Futaba Industrial, Yutaka Giken, Friedrich Boysen, Sejong Industrial, Borla Performance, MagnaFlow, Akrapovic, Remus Performance, DynoMax, Flowmaster, ArvinMeritor, Calsonic Kansei, AP Exhaust Technologies, Bremo. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the cold-end exhaust system aftermarket is primarily defined by component type and material durability. Mufflers represent the core of the market as they are functionally critical for noise regulation and are most prone to internal rust. Material-wise, the industry is witnessing a decisive move away from aluminized steel toward stainless steel, as consumers prioritize longevity to avoid frequent labor costs associated with exhaust repairs. Furthermore, the distribution channel is split between Independent Aftermarket (IAM) and OEM Aftermarket (OES), with IAM holding a significant lead due to its competitive pricing and wider availability of parts for older vehicle models.
- By Component: Mufflers dominate the share, followed by exhaust pipes and resonators. Hangers and clamps represent a smaller, high-volume recurring revenue segment.
- By Vehicle Type: Passenger cars account for the largest volume; however, Light Commercial Vehicles (LCVs) are the fastest-growing segment due to high duty cycles in urban delivery.
- By Material: Stainless steel (Series 400 and 300) is the leading segment by value. Titanium is a niche but high-growth segment for high-performance and luxury applications.
- By Distribution: Independent Aftermarket retailers and online marketplaces are growing faster than traditional dealership channels.
Regional Highlights
- North America: The largest market for cold-end systems, driven by the massive fleet of pickups and SUVs in the United States and the high rate of vehicle age (12.5 years average).
- Europe: A mature market focused on high-quality stainless steel replacements and strict adherence to Euro 6/7 noise emission standards. Germany and the UK are the key contributors.
- Asia-Pacific: The fastest-growing region, led by China and India. The rapid motorization and increasing secondary market for vehicles are driving aftermarket demand.
- Latin America: Brazil and Mexico show steady growth, primarily in the LCV segment and budget-friendly aluminized steel components.
- Middle East & Africa: Growth is concentrated in the GCC countries for luxury performance exhausts and in South Africa for general maintenance parts.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Cold-end Exhaust System Aftermarket Market.- Tenneco Inc. (Walker Exhaust)
- Faurecia (Forvia Group)
- Benteler International AG
- Magneti Marelli S.p.A.
- Bosal International
- Eberspacher Group
- Futaba Industrial Co., Ltd.
- Yutaka Giken Co., Ltd.
- Friedrich Boysen GmbH & Co. KG
- Sejong Industrial Co., Ltd.
- Borla Performance Industries
- MagnaFlow
- Akrapovic d.d.
- Remus Performance Sport Exhausts
- DynoMax Performance Exhaust
- Flowmaster (Holley Performance Products)
- ArvinMeritor, Inc.
- Calsonic Kansei Corporation (Marelli)
- AP Exhaust Technologies
- Bremo S.p.A.
Frequently Asked Questions
What is included in the cold-end of an exhaust system?
The cold-end of an exhaust system typically refers to all components located after the catalytic converter or diesel particulate filter. This includes the intermediate pipes, resonators, mufflers, and the tailpipe. These components are primarily responsible for sound dampening and directing gases safely away from the vehicle cabin.
How is the rise of Electric Vehicles (EVs) affecting this market?
While EVs do not use exhaust systems, the impact on the aftermarket is gradual. The massive global fleet of internal combustion engine vehicles, which has an average age of over 12 years in developed markets, ensures a consistent demand for replacement parts for the next 15 to 20 years. However, long-term growth will likely shift toward hybrid vehicle solutions and specialized performance parts.
Why is stainless steel preferred over aluminized steel in the aftermarket?
Stainless steel offers significantly better resistance to corrosion caused by heat, moisture, and road salt. While aluminized steel is cheaper, it typically lasts only 2 to 5 years, whereas high-grade stainless steel can last the remaining lifetime of the vehicle, making it a more cost-effective choice for long-term vehicle owners.
Which region offers the most growth potential for manufacturers?
The Asia-Pacific region, specifically China, India, and Southeast Asia, offers the highest growth potential. This is due to increasing vehicle ownership, the development of a secondary used-car market, and the expansion of local manufacturing hubs for aftermarket components.
What are the key drivers for the performance exhaust segment?
The performance segment is driven by automotive enthusiasts looking to improve vehicle horsepower, torque, and sound. Lightweight materials like titanium and carbon fiber tips, along with "cat-back" systems that provide a more aggressive exhaust note, are highly popular in this sub-sector.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
