Aluminum Tube Market
Aluminum Tube Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2025-2033)
Report ID : RI_700114 | Published On : July 23, 2025 |
Format : 


 | Author : Jonathan Sikka
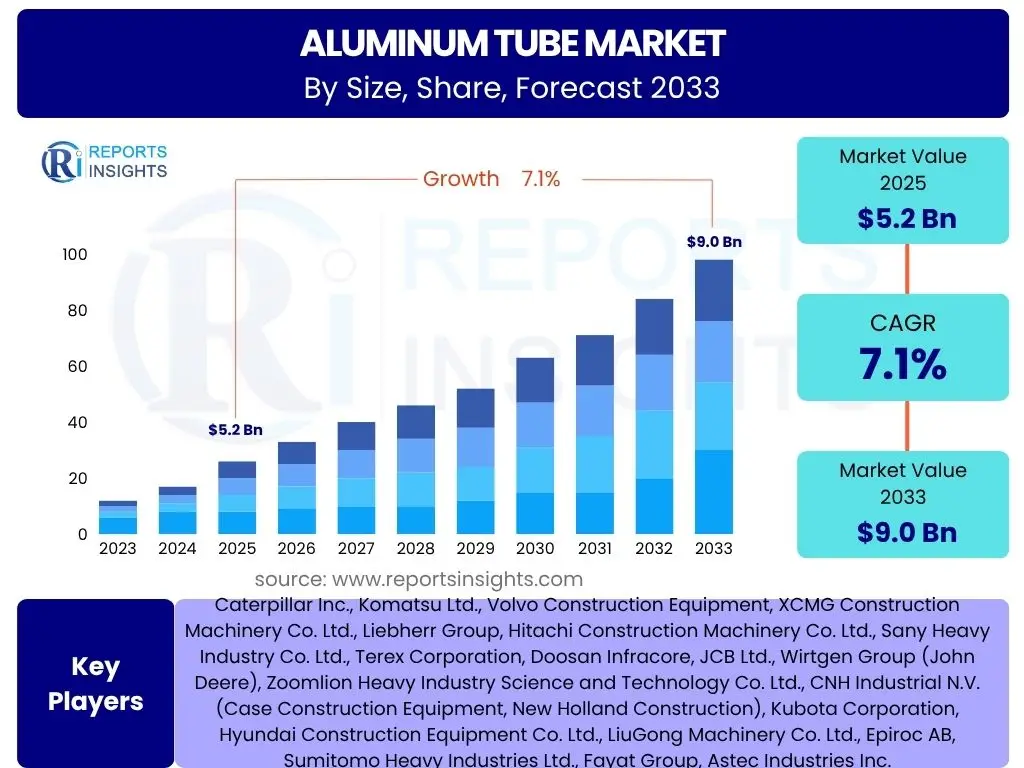
Aluminum Tube Market is projected to grow at a Compound annual growth rate (CAGR) of 7.1% between 2025 and 2033, current valued at USD 5.2 Billion in 2025 and is projected to grow by USD 9.0 Billion by 2033 the end of the forecast period.
Key Aluminum Tube Market Trends & Insights
The Aluminum Tube Market is currently shaped by several transformative trends, driven by evolving industrial demands and sustainability imperatives. Key insights indicate a significant shift towards lightweighting and miniaturization across various applications, fueled by industries such as automotive, aerospace, and electronics seeking enhanced efficiency and reduced material consumption. Concurrently, the increasing emphasis on circular economy principles is boosting the demand for recycled aluminum content in tube manufacturing, aligning with global environmental regulations and corporate sustainability goals. Furthermore, the adoption of advanced manufacturing technologies, including precision extrusion and specialized alloy development, is enabling the production of aluminum tubes with superior strength-to-weight ratios, corrosion resistance, and thermal conductivity, opening new possibilities for their use in high-performance applications. The market is also witnessing a trend towards customization and specialized solutions, as end-user industries require tubes tailored to specific dimensions, surface finishes, and performance characteristics for complex systems. This is supported by:
- Lightweighting initiatives in automotive and aerospace for fuel efficiency and performance enhancement.
- Growing focus on sustainability and the use of recycled aluminum, driving demand for eco-friendly solutions.
- Technological advancements in extrusion and drawing processes for improved material properties and precision.
- Increasing application of aluminum tubes in HVAC&R systems due to their excellent thermal conductivity.
- Expansion into new markets and niche applications, including medical devices and electric vehicle components.
AI Impact Analysis on Aluminum Tube
Artificial Intelligence (AI) is progressively transforming the Aluminum Tube Market by optimizing various stages of the value chain, from raw material sourcing to end-product delivery. AI-driven solutions are enhancing manufacturing efficiency, enabling predictive maintenance for machinery, and improving quality control processes by detecting defects with higher accuracy and speed than traditional methods. Furthermore, AI algorithms are playing a crucial role in demand forecasting and supply chain optimization, helping manufacturers to respond more agilely to market fluctuations, reduce inventory costs, and ensure timely delivery of products. This integration of AI not only streamlines operations but also supports the development of new, more efficient aluminum tube designs through simulation and material science advancements, fostering innovation across the sector. Key impacts include:
- Optimized production schedules and reduced waste through AI-driven process control.
- Enhanced quality assurance with AI-powered visual inspection systems detecting flaws.
- Predictive maintenance for manufacturing equipment, minimizing downtime and operational costs.
- Improved supply chain management and logistics efficiency through AI-driven forecasting and routing.
- Accelerated R&D in new aluminum alloys and tube designs through simulation and data analysis.
Key Takeaways Aluminum Tube Market Size & Forecast
- The Aluminum Tube Market is projected to achieve a robust CAGR of 7.1% from 2025 to 2033.
- The market size is estimated at USD 5.2 Billion in 2025.
- By 2033, the market is forecasted to reach USD 9.0 Billion, indicating significant growth potential.
- Growth is primarily driven by increasing adoption in automotive, construction, and HVAC&R sectors.
- Technological advancements and sustainability trends are key enablers of market expansion.
Aluminum Tube Market Drivers Analysis
The Aluminum Tube Market is propelled by a confluence of robust drivers stemming from various end-use industries, each contributing significantly to the demand for lightweight, corrosion-resistant, and recyclable materials. The global push for energy efficiency and sustainable solutions heavily favors aluminum tubes, particularly in sectors where weight reduction directly translates to performance improvements and lower operational costs. Furthermore, the versatile properties of aluminum, combined with advancements in manufacturing techniques, allow for a broad range of applications, continually expanding the market's reach. As industries worldwide prioritize durability, aesthetic appeal, and environmental responsibility, the intrinsic characteristics of aluminum tubes position them as a preferred choice over traditional materials, cementing their growth trajectory.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Increasing Demand from Automotive & Transportation Industry | +2.5% | Global, particularly Asia Pacific, Europe, North America | Short to Long-term |
| Growth in Building & Construction Sector | +1.8% | Asia Pacific, Middle East & Africa, Latin America | Medium to Long-term |
| Expanding HVAC & Refrigeration Applications | +1.5% | North America, Europe, Asia Pacific | Short to Medium-term |
| Rising Demand for Packaging Solutions | +1.2% | Global, especially emerging economies | Short to Medium-term |
| Focus on Sustainability and Recycling | +1.0% | Europe, North America, developing Asia Pacific | Long-term |
Aluminum Tube Market Restraints Analysis
Despite significant growth prospects, the Aluminum Tube Market faces certain restraints that could temper its expansion. The most notable challenge stems from the inherent volatility of aluminum raw material prices, which are subject to global commodity market fluctuations, geopolitical events, and energy costs. This instability directly impacts manufacturing costs and profit margins, making long-term planning difficult for market players. Furthermore, the market experiences considerable competition from alternative materials such as steel, copper, and various plastics, which may offer cost advantages or specific performance benefits for certain applications. These substitute materials pose a constant threat, especially in cost-sensitive segments. Additionally, the energy-intensive nature of primary aluminum production raises concerns about environmental footprint and operational costs, potentially limiting growth in regions with strict energy regulations or high electricity prices.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Volatility of Aluminum Raw Material Prices | -1.5% | Global | Short to Medium-term |
| Competition from Substitute Materials (e.g., steel, copper, plastics) | -1.0% | Global, varying by application | Medium to Long-term |
| High Initial Capital Investment for Manufacturing Facilities | -0.8% | Developing regions, new entrants | Long-term |
| Energy-Intensive Production Process | -0.7% | Europe, North America (due to stringent regulations) | Medium to Long-term |
Aluminum Tube Market Opportunities Analysis
The Aluminum Tube Market is poised to capitalize on several significant opportunities driven by global technological shifts and sustainability mandates. The accelerated growth of electric vehicles (EVs) and hybrid electric vehicles (HEVs) presents a substantial avenue for aluminum tubes, as they are crucial components for battery cooling systems, structural frames, and lightweight chassis, directly contributing to extending range and improving efficiency. Furthermore, increasing investments in renewable energy infrastructure, such as solar power and concentrated solar thermal systems, require durable and lightweight tubing solutions for heat exchangers and structural supports. The expansion of niche applications in medical devices, sporting goods, and advanced industrial machinery also offers specialized market segments where the unique properties of aluminum tubes are highly valued. Finally, continuous innovation in alloy development and manufacturing processes can unlock new performance characteristics, making aluminum tubes suitable for even more demanding environments and complex designs, thereby fostering market diversification.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Growing Adoption in Electric Vehicles (EVs) and HEVs | +2.0% | Global, particularly North America, Europe, China | Short to Long-term |
| Expansion into New and Niche Applications (e.g., Medical, Sports Equipment) | +1.5% | Developed economies, specific regions with high innovation | Medium to Long-term |
| Advancements in Alloy Development and Manufacturing Techniques | +1.3% | Global, focused on R&D hubs | Long-term |
| Increasing Demand for Sustainable and Recyclable Materials | +1.0% | Europe, North America, progressive Asian markets | Long-term |
Aluminum Tube Market Challenges Impact Analysis
The Aluminum Tube Market faces several significant challenges that require strategic navigation by industry players. Global supply chain disruptions, intensified by geopolitical tensions, natural disasters, and pandemics, pose a constant threat to the timely availability of raw materials and efficient distribution of finished products, leading to increased lead times and operational costs. Furthermore, the industry is grappling with increasingly stringent environmental regulations, particularly concerning carbon emissions and energy consumption during aluminum production, which necessitate substantial investments in greener technologies and compliance measures. The management and disposal of industrial waste, along with the development of effective recycling infrastructure, also present ongoing complexities. Additionally, the high energy consumption required for primary aluminum manufacturing contributes to higher production costs and a larger carbon footprint, making it challenging for manufacturers to balance economic viability with environmental responsibility.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Disruptions and Geopolitical Instabilities | -1.2% | Global | Short to Medium-term |
| Stringent Environmental Regulations and Carbon Emission Targets | -1.0% | Europe, North America, parts of Asia Pacific | Medium to Long-term |
| Managing Industrial Waste and Recycling Infrastructure | -0.9% | Global, with regional variations in infrastructure development | Long-term |
| High Energy Consumption in Primary Aluminum Production | -0.8% | Global, affecting cost competitiveness | Long-term |
Aluminum Tube Market - Updated Report Scope
This comprehensive market research report provides an in-depth analysis of the Aluminum Tube Market, offering critical insights into its current state and future growth trajectory. The scope includes a detailed examination of market dynamics, key trends, drivers, restraints, opportunities, and challenges influencing the industry across various geographical regions and application segments. The report also highlights the competitive landscape, profiling key market players and their strategic initiatives, alongside a robust forecast period to aid stakeholders in informed decision-making. The granular segmentation analysis further dissects the market by material type, manufacturing process, diameter, wall thickness, application, and end-use industry, presenting a holistic view of the market's structure and potential for expansion.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2024 |
| Historical Year | 2019 to 2023 |
| Forecast Year | 2025 - 2033 |
| Market Size in 2025 | USD 5.2 Billion |
| Market Forecast in 2033 | USD 9.0 Billion |
| Growth Rate | 7.1% |
| Number of Pages | 257 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Global Aluminum Solutions Inc., Precision Tube Innovations, Lightweight Alloys Group, Dynamic Metals Corp, Apex Tube Manufacturing, Horizon Extrusions, Universal Aluminum Products, Zenith Metal Tubes, Allied Tube Systems, Prime Aluminum Extrusions, Elite Tube Solutions, Future Metals Manufacturing, High Performance Tubes, Integrated Aluminum Products, Advanced Tube Technologies, Stellar Metal Forming, Pioneer Extrusion Company, Omni Tube Works, Continuum Metals, Core Component Systems |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
:The Aluminum Tube Market is intricately segmented across various dimensions to provide a granular understanding of its structure, growth avenues, and target audiences. Each segmentation offers unique insights into how different types of aluminum tubes are produced, tailored, and consumed across a multitude of industries. Understanding these segments is crucial for stakeholders to identify key market niches, assess competitive landscapes, and formulate effective business strategies. This detailed analysis allows for a precise evaluation of supply and demand dynamics, technological advancements, and regional consumption patterns within the overarching aluminum tube ecosystem.
The market is primarily segmented by Material Type, Manufacturing Process, Wall Thickness, Diameter, Application, and End-Use Industry. Each of these categories reveals distinct market characteristics, driven by specific performance requirements, cost considerations, and regulatory frameworks. For instance, the choice of material alloy directly impacts properties such as strength, corrosion resistance, and weldability, which are critical for various applications. Similarly, the manufacturing process dictates the tube's structural integrity and precision, while dimensions like wall thickness and diameter determine suitability for light-duty or heavy-duty applications. The application and end-use industry segments highlight the diverse utility of aluminum tubes, from automotive fluid lines to sophisticated medical instruments, underscoring the market's versatility and growth potential.
- By Material Type: This segment categorizes aluminum tubes based on the alloy series used, each offering specific properties tailored for distinct applications.
- 1xxx series: Characterized by high purity aluminum, offering excellent corrosion resistance, high thermal and electrical conductivity, and good workability. These are typically used in electrical conductors, chemical equipment, and decorative applications where strength is not a primary concern but purity and conductivity are paramount. Their primary use is where high thermal or electrical conductivity is required, such as heat exchanger tubes and electrical conduit pipes.
- 3xxx series: Primarily aluminum-manganese alloys, known for good formability, moderate strength, and excellent corrosion resistance. This series is widely used in general purpose applications, including HVAC&R systems, heat exchangers, and household goods, due to their balance of properties and cost-effectiveness. The manganese content enhances their strength without significantly compromising ductility, making them suitable for bending and shaping operations.
- 5xxx series: Aluminum-magnesium alloys, offering high strength, excellent corrosion resistance, particularly in marine environments, and good weldability. They are ideal for structural applications where strength and resistance to harsh conditions are critical, such as in marine components, pressure vessels, and certain automotive parts. The magnesium content provides significant strengthening through solid solution hardening.
- 6xxx series: Aluminum-magnesium-silicon alloys, which are heat-treatable, offering good formability, excellent corrosion resistance, and high strength after heat treatment. This series is the most versatile and widely used in construction, architectural applications, automotive structures, and general engineering due to their balanced properties and ease of extrusion. They can be artificially aged to increase their strength considerably.
- 7xxx series: Aluminum-zinc alloys, often with magnesium and copper, known for their exceptionally high strength, making them suitable for aerospace and high-performance structural applications. While offering superior strength, they can be less corrosion resistant and harder to weld compared to other series. Their primary application is in demanding environments where maximum strength-to-weight ratio is crucial.
- By Manufacturing Process: This segmentation reflects the techniques employed to produce aluminum tubes, each impacting the tube's structural integrity, surface finish, and cost.
- Extrusion: This process involves forcing a heated aluminum billet through a die to create a tube of a desired cross-section. Extruded tubes are known for their precision, complex shapes capability, and cost-effectiveness for long runs. They are widely used across almost all end-use industries due to their versatility in dimensions and forms. The process allows for seamless tubes and hollow profiles with consistent wall thickness.
- Drawn: Drawn tubes are produced by pulling extruded or welded tubes through a die. This process improves surface finish, dimensional accuracy, and mechanical properties (like strength and hardness) through cold working. Drawn tubes are highly sought after for applications requiring tight tolerances, such as precision instruments, hydraulic lines, and medical devices. This method often results in a smoother interior and exterior finish.
- Seamless: Seamless aluminum tubes are manufactured without a welded seam, typically through extrusion or by piercing a solid billet. They offer superior structural integrity, burst strength, and resistance to corrosion, making them essential for high-pressure applications in hydraulics, pneumatics, aerospace, and oil & gas. The absence of a weld line eliminates potential weak points.
- Welded: Welded tubes are formed from aluminum strips or sheets that are rolled into a tubular shape and then welded along the seam. While generally more cost-effective for larger diameters and thinner walls, they may have lower pressure ratings than seamless tubes. They are commonly used in applications where high pressure is not a critical factor, such as decorative purposes, some structural applications, and general piping.
- By Wall Thickness: This segment differentiates tubes based on their wall thickness, directly influencing their strength, weight, and thermal properties.
- Thin Wall: Tubes with a relatively small wall thickness compared to their diameter. They are lightweight and often used in applications where weight reduction is critical, such as aerospace components, automotive heat exchangers, and certain consumer goods. Their heat transfer capabilities are also excellent due to reduced material volume.
- Standard Wall: Tubes with a moderate wall thickness, balancing strength, weight, and cost. These are the most commonly used type for a wide range of general industrial, construction, and HVAC&R applications. They provide adequate structural integrity for most conventional uses.
- Thick Wall: Tubes with a substantial wall thickness, offering maximum strength and durability. They are preferred for high-pressure systems, heavy-duty structural applications, and situations requiring high resistance to external forces or internal pressures, such as in hydraulic cylinders and some marine applications.
- By Diameter: This segmentation considers the outer diameter of the aluminum tubes, impacting their flow capacity and structural use.
- Small Diameter: Tubes typically used for precision applications, fluid transfer in confined spaces, or intricate systems. Examples include medical tubing, capillary tubes, and small instrument components.
- Medium Diameter: The most common range, suitable for general industrial piping, automotive fluid lines, and residential HVAC systems. They offer a balance of flow capacity and structural support.
- Large Diameter: Employed in applications requiring high volume fluid transfer or significant structural support, such as large-scale industrial pipelines, ventilation systems, or heavy construction.
- By Application: This segment highlights the diverse functional uses of aluminum tubes across various sectors.
- HVAC&R: Heating, Ventilation, Air Conditioning, and Refrigeration systems, where aluminum tubes are critical for heat exchangers, condensers, and evaporators due to their excellent thermal conductivity and corrosion resistance.
- Automotive: Used extensively for fluid lines (fuel, brake, coolant), structural components, heat exchangers, and battery cooling in traditional and electric vehicles, driven by lightweighting mandates.
- Aerospace: Essential for lightweight structural components, hydraulic systems, and fuel lines, where the strength-to-weight ratio is paramount for aircraft performance and fuel efficiency.
- Industrial Pneumatic & Hydraulic: Used in cylinders, actuators, and fluid power systems due to their smooth internal finish and pressure resistance.
- Consumer Goods: Found in various household items, sporting equipment (e.g., bicycle frames), and furniture for their lightweight and aesthetic properties.
- Medical Devices: Employed in precision medical instruments, diagnostic equipment, and fluid delivery systems due requiring inert and sterile materials.
- Construction: Utilized for structural elements, architectural designs, window frames, and scaffolding due to their durability, corrosion resistance, and aesthetic appeal.
- Packaging (Aerosol Cans, Collapsible Tubes): Widely used for packaging cosmetics, pharmaceuticals, food, and industrial products due to their barrier properties, recyclability, and ability to be shaped into various forms.
- Others: Includes applications in marine, electronics (heat sinks), solar energy, and various custom industrial requirements.
- By End-Use Industry: This category defines the ultimate sectors that consume aluminum tubes for their products or infrastructure.
- Automotive & Transportation: Encompasses all vehicles (cars, trucks, trains, marine vessels, aircraft) and their related infrastructure where aluminum tubes contribute to lightweighting, fuel efficiency, and structural integrity.
- Building & Construction: Includes residential, commercial, and industrial buildings, where aluminum tubes are used in structural frameworks, windows, doors, facades, and various architectural elements for their durability and aesthetic qualities.
- HVAC & Refrigeration: Covers the manufacturing and installation of heating, ventilation, air conditioning, and refrigeration units for commercial, industrial, and residential purposes, relying on aluminum tubes for heat exchange and fluid conveyance.
- Electrical & Electronics: Involves applications in electrical conduits, heat sinks for electronic components, and casings for sensitive equipment, leveraging aluminum's electrical conductivity and thermal dissipation properties.
- Packaging: This industry utilizes aluminum tubes extensively for aerosol cans, collapsible tubes for toothpaste, creams, and adhesives, due to aluminum's barrier properties, recyclability, and light weight.
- Medical & Pharmaceutical: Encompasses the use of aluminum tubes in medical devices, drug delivery systems, laboratory equipment, and sterile packaging, where material purity, non-reactivity, and precision are critical.
- Consumer Durables: Includes the manufacturing of appliances, furniture, and sporting goods where aluminum tubes offer lightweight, durable, and often aesthetically pleasing components.
- Marine: Applications in shipbuilding and marine structures where aluminum tubes offer corrosion resistance in saltwater environments and contribute to vessel lightweighting.
- Others: Covers miscellaneous industries such as renewable energy (solar panel frames), general industrial machinery, and specialized custom applications.
Regional Highlights
The Aluminum Tube Market exhibits significant regional variations, influenced by industrial development, regulatory frameworks, technological adoption, and consumer preferences. Each major geographical segment contributes uniquely to the global market landscape, driven by specific demand patterns from key end-use industries within their respective regions. Understanding these regional dynamics is essential for market players to tailor their strategies, optimize supply chains, and identify high-growth opportunities. The diverse economic landscapes and industrial priorities across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa collectively shape the global demand and supply of aluminum tubes.
For instance, while mature economies like North America and Europe focus on innovation, lightweighting, and high-value applications, emerging economies in Asia Pacific and Latin America are characterized by rapid industrialization and infrastructure development, driving demand for more foundational uses of aluminum tubes. The Middle East & Africa, on the other hand, presents opportunities driven by investments in construction and industrial diversification. These regional spotlights underscore the importance of localized market insights for successful market penetration and sustained growth.
- North America: This region is a significant market for aluminum tubes, driven by robust demand from the automotive, aerospace, and HVAC&R sectors. The emphasis on lightweighting in the automotive industry, particularly with the growth of electric vehicles, continues to fuel demand for aluminum tubes in battery cooling systems and structural components. Strict energy efficiency regulations also bolster the adoption of aluminum in residential and commercial HVAC systems. Furthermore, the presence of a mature aerospace industry contributes substantially to the market, requiring high-performance aluminum tubes for aircraft manufacturing. Technological advancements and the increasing adoption of sustainable manufacturing practices are also key drivers in this region.
- Europe: Europe represents a highly advanced market, characterized by stringent environmental regulations and a strong focus on sustainability and circular economy principles. This drives the demand for recycled aluminum content in tubes and encourages innovation in manufacturing processes to reduce carbon footprint. Key industries include automotive (especially premium and electric vehicles), construction (sustainable building materials), and industrial machinery. Germany, France, and the UK are leading consumers, with significant investments in green technologies and smart infrastructure projects further boosting market growth. The region's emphasis on energy efficiency in buildings also supports the use of aluminum tubes in modern HVAC systems.
- Asia Pacific (APAC): APAC is the largest and fastest-growing market for aluminum tubes, propelled by rapid industrialization, urbanization, and significant investments in infrastructure development, particularly in countries like China, India, Japan, and South Korea. The burgeoning automotive sector, vast construction projects, and expanding electronics manufacturing contribute immensely to the demand. Emerging economies within APAC are also witnessing increased adoption of HVAC&R systems and packaged consumer goods, further accelerating market expansion. The region benefits from lower manufacturing costs and a large consumer base, making it a pivotal hub for both production and consumption of aluminum tubes.
- Latin America: This region is experiencing steady growth in the aluminum tube market, primarily driven by investments in infrastructure, growth in the automotive sector (especially Brazil and Mexico), and expanding construction activities. The demand for industrial and commercial refrigeration units also contributes to market expansion. While not as mature as North America or Europe, Latin America offers significant growth potential as industrialization continues and disposable incomes rise, leading to increased demand for various end-use products incorporating aluminum tubes. The focus on raw material extraction and processing also plays a role in demand for industrial tubing.
- Middle East and Africa (MEA): The MEA region presents a developing market for aluminum tubes, characterized by large-scale construction projects, diversification of economies away from oil, and growing investments in industrial and commercial infrastructure. Countries like UAE, Saudi Arabia, and South Africa are key contributors. The demand is particularly strong from the building and construction sector for architectural applications, as well as from emerging HVAC&R and packaging industries. While the market is still in its nascent stages compared to other regions, ongoing urbanization and industrial development initiatives are expected to foster considerable growth in the forecast period.

Top Key Players:
The market research report covers the analysis of key stake holders of the Aluminum Tube Market. Some of the leading players profiled in the report include -:- Global Aluminum Solutions Inc.
- Precision Tube Innovations
- Lightweight Alloys Group
- Dynamic Metals Corp
- Apex Tube Manufacturing
- Horizon Extrusions
- Universal Aluminum Products
- Zenith Metal Tubes
- Allied Tube Systems
- Prime Aluminum Extrusions
- Elite Tube Solutions
- Future Metals Manufacturing
- High Performance Tubes
- Integrated Aluminum Products
- Advanced Tube Technologies
- Stellar Metal Forming
- Pioneer Extrusion Company
- Omni Tube Works
- Continuum Metals
- Core Component Systems
Frequently Asked Questions:
What is the projected growth rate for the Aluminum Tube Market?
The Aluminum Tube Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.1% between 2025 and 2033. This growth is primarily driven by increasing demand from key end-use industries such as automotive, construction, and HVAC&R, coupled with a global emphasis on lightweighting and sustainable materials. The market is witnessing continuous innovation in alloy development and manufacturing processes to meet diverse application requirements.
What is the market size of Aluminum Tube in 2025 and its forecast for 2033?
The Aluminum Tube Market is estimated at USD 5.2 Billion in 2025. It is projected to experience substantial growth, reaching an estimated value of USD 9.0 Billion by the end of the forecast period in 2033. This expansion is attributed to the versatility of aluminum tubes, their recyclability, and their increasing adoption across a wide range of industrial and consumer applications.
Which key industries are driving the demand for aluminum tubes?
The demand for aluminum tubes is significantly driven by several key industries. The automotive and transportation sector leads due to the push for lightweighting and the growth of electric vehicles. The building and construction industry utilizes aluminum tubes for structural and architectural applications. Additionally, the HVAC&R (Heating, Ventilation, Air Conditioning, and Refrigeration) sector, packaging industry, and medical devices industry are significant consumers, leveraging aluminum's thermal conductivity, barrier properties, and inertness respectively.
How do sustainability trends impact the Aluminum Tube Market?
Sustainability trends profoundly impact the Aluminum Tube Market by increasing the demand for recycled aluminum and promoting eco-friendly manufacturing processes. Aluminum is highly recyclable without loss of quality, making aluminum tubes a preferred choice for companies aiming to reduce their environmental footprint and align with circular economy principles. This focus on sustainability not only enhances aluminum's appeal but also drives innovation in responsible sourcing and production techniques, influencing market dynamics positively.
What are the primary manufacturing processes for aluminum tubes?
The primary manufacturing processes for aluminum tubes include extrusion, drawing, and welding. Extrusion involves forcing aluminum through a die to create a desired profile, offering precision and versatility. Drawing further refines extruded or welded tubes, enhancing dimensional accuracy and surface finish. Welded tubes are formed from rolled aluminum sheets with a seam, often used for cost-effectiveness, while seamless tubes, typically produced via extrusion or piercing, offer superior integrity for high-pressure applications. Each process caters to specific application requirements and performance criteria.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
