Traction Transformers Market
Traction Transformers Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711366 | Published On : October 29, 2026 |
Format : 


 | Author : Seema Bhateja
Traction Transformers Market Size
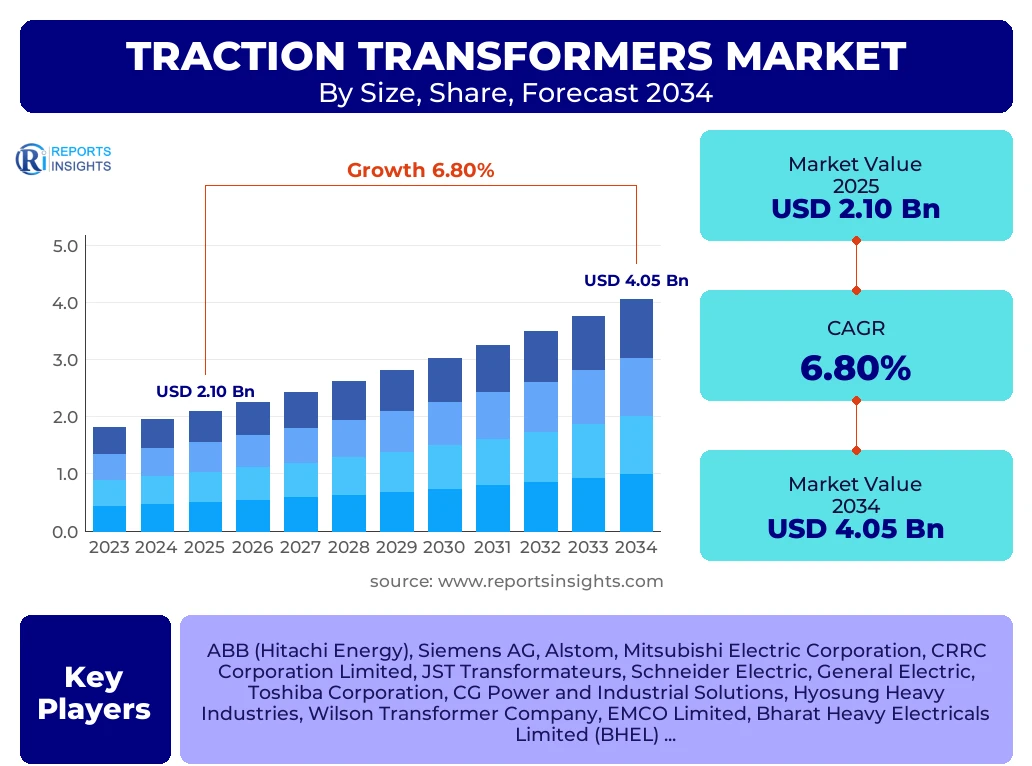
According to Reports Insights Consulting Pvt Ltd, The Traction Transformers Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.8% between 2025 and 2034. The market is estimated at USD 2.24 Billion in 2026 and is projected to reach USD 4.05 Billion by the end of the forecast period in 2034.
Key Traction Transformers Market Trends & Insights
The Traction Transformers market is currently undergoing a significant technological transformation driven by the global imperative for decarbonization and the rapid expansion of high-speed rail networks. Market participants are increasingly focusing on the development of lightweight, compact, and high-efficiency transformers that utilize sustainable insulating materials, such as ester-based fluids, to replace traditional mineral oils. Furthermore, the integration of digital monitoring systems and Internet of Things (IoT) sensors into traction units is enabling predictive maintenance, reducing downtime, and extending the operational lifecycle of rolling stock. The shift toward multi-system locomotives capable of operating across various voltage standards (AC and DC) is also a prominent trend, particularly in Europe and Asia, where cross-border rail connectivity is being prioritized to enhance logistics and passenger transit efficiency.
- Largest Region: Asia Pacific remains the dominant market, accounting for over 45% of the global share due to massive infrastructure projects in China and India.
- Fastest Growing Region: Asia Pacific is also expected to witness the highest CAGR, fueled by rapid urbanization and the proliferation of metro and light rail transit systems.
- Largest Segment by Type: Tap changing traction transformers hold the largest market share owing to their versatility and widespread application in diverse locomotive types.
- Leading Application: The high-speed train segment is the fastest-growing application area, supported by government investments in sustainable long-distance transport.
Key Takeaways Traction Transformers Market Size & Forecast
The global traction transformers market is characterized by a high degree of technical specialization and a consolidated competitive landscape. Key market drivers include the accelerating electrification of railway tracks in emerging economies and the modernization of aging rolling stock in developed nations. The forecast period 2026-2034 is expected to see a surge in demand for specialized transformers designed for metros and urban transit, as cities seek to mitigate traffic congestion and lower carbon emissions. Strategically, manufacturers are forming long-term partnerships with railway operators and government bodies to secure multi-year procurement contracts, which provides stability in a capital-intensive industry.
- Global Electrification: Increasing government mandates to phase out diesel locomotives in favor of electric rolling stock are the primary catalysts for market expansion.
- Technological Innovation: The adoption of Silicon Carbide (SiC) based power electronics is beginning to influence transformer design, aiming for higher power density and reduced weight.
- China Dominance: China continues to be the largest national market, driven by its expansive high-speed rail (HSR) network and domestic manufacturing capabilities.
- Sustainability Focus: Bio-degradable insulating fluids and recyclable materials are becoming standard requirements in European procurement tenders.
- Market Stability: Long-term infrastructure projects provide a resilient pipeline for traction transformer demand despite short-term economic fluctuations.
Traction Transformers Market Drivers Analysis
The primary growth engine for the traction transformers market is the massive global investment in railway electrification. As nations strive to meet net-zero emissions targets, the transition from diesel-electric to fully electric locomotives has become a strategic priority. This is particularly evident in the European Union's Green Deal and India's Mission 100% Electrification, which necessitate a vast number of new traction units. Additionally, the rise of "Mega-Cities" in developing regions is driving the demand for efficient metro and light rail systems to manage urban mobility, directly boosting the requirement for specialized onboard traction transformers that can withstand frequent start-stop cycles and high load variations.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of High-Speed Rail Networks | +2.4% | China, Japan, France, Spain | 2025 - 2034 |
| Government Initiatives for Rail Electrification | +1.9% | India, Germany, United Kingdom | 2025 - 2030 |
| Urbanization and Metro Project Proliferation | +1.5% | Southeast Asia, Brazil, GCC Countries | 2026 - 2034 |
| Replacement of Legacy Rolling Stock | +1.0% | United States, Russia, Italy | 2025 - 2032 |
Traction Transformers Market Restraints Analysis
Despite strong growth drivers, the market faces significant hurdles, primarily centered around high initial capital expenditure (CAPEX) and the technical complexity of modernizing old infrastructure. The installation of traction transformers and associated electrification infrastructure requires multi-billion dollar investments, which can be deterred by economic instability or shifting political priorities. Furthermore, the technical challenge of integrating new transformers with varying legacy signaling and power systems across different national borders remains a significant bottleneck for international rail projects, particularly in fragmented markets like Eastern Europe and Africa.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Capital Expenditure | -1.2% | Global (Impactful in Developing Nations) | 2025 - 2034 |
| Technical Barriers in Multi-System Interoperability | -0.8% | European Union, Cross-border projects | 2025 - 2030 |
Traction Transformers Market Opportunities Analysis
The market is ripe with opportunities stemming from the digital revolution and the development of alternative propulsion systems. The rise of hybrid battery-electric and hydrogen fuel cell trains presents a new frontier for traction transformer manufacturers to design specialized units that can manage power flow between multiple energy sources. Additionally, the implementation of "Digital Twins" and advanced simulation software allows manufacturers to optimize transformer designs for specific routes and environmental conditions, offering a competitive edge in performance and reliability. The growing trend of "Rail-as-a-Service" also opens doors for long-term service and maintenance contracts, providing recurring revenue streams beyond the initial sale.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Eco-friendly Ester-filled Transformers | +1.6% | Western Europe, North America | 2026 - 2034 |
| Digitalization and IoT Integration | +1.3% | Japan, South Korea, Germany | 2025 - 2034 |
| Adoption of Hybrid-Electric Rolling Stock | +1.1% | Global | 2027 - 2034 |
Traction Transformers Market Challenges Impact Analysis
Strategic challenges in the traction transformers market include the volatility of raw material prices and the necessity for extreme durability in harsh operational environments. Materials such as high-grade copper and electrical steel are subject to significant price fluctuations, which can erode profit margins for manufacturers locked into long-term fixed-price contracts. Moreover, traction transformers must be engineered to withstand extreme vibrations, thermal cycling, and space constraints, necessitating constant R&D investment. Compliance with varying international safety and noise emission standards also adds a layer of complexity to global product distribution.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Fluctuation in Copper and Steel Prices | -0.9% | Global Manufacturers | 2025 - 2034 |
| Stringent Noise and Vibration Regulations | -0.5% | Urbanized Regions (EU, Japan) | 2025 - 2028 |
Traction Transformers Market - Updated Report Scope
This report provides a comprehensive analysis of the global traction transformers industry, covering technological advancements, competitive dynamics, and regional investment patterns. The scope includes a detailed breakdown of market size by voltage, mounting position, and rolling stock application, ensuring a granular view of the sector's trajectory from 2020 through 2034. It evaluates the impact of macroeconomic factors and environmental regulations on manufacturing strategies and procurement cycles across major geographies.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 2.10 Billion |
| Market Forecast in 2034 | USD 4.05 Billion |
| Growth Rate | 6.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | ABB (Hitachi Energy), Siemens AG, Alstom, Mitsubishi Electric Corporation, CRRC Corporation Limited, JST Transformateurs, Schneider Electric, General Electric, Toshiba Corporation, CG Power and Industrial Solutions, Hyosung Heavy Industries, Wilson Transformer Company, EMCO Limited, Bharat Heavy Electricals Limited (BHEL), Kirloskar Electric Company |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the traction transformers market reflects the diverse engineering requirements of the modern railway industry. By mounting position, the market is divided into roof, underframe, and machine room installations, with underframe and roof-mounted units gaining traction due to the rise of Electric Multiple Units (EMUs) where space optimization is critical. Voltage segmentation remains divided between AC and DC systems, though AC systems dominate the long-distance and high-speed segments due to their efficiency over long distances. The application segment is seeing a significant shift toward metros and high-speed rail as urban centers invest in mass transit infrastructure to combat congestion and pollution.
- By Type:
- Tap Changing: Predominant in varied voltage environments.
- Tapped: Used for specific, constant voltage applications.
- Rectifier: Essential for converting AC to DC for onboard electronic systems.
- By Mounting Position:
- Underframe: Maximizes cabin space for passengers; widely used in EMUs.
- Roof-mounted: Preferred for low-floor tramways and specific light rail designs.
- Machine Room: Standard in traditional locomotives where space is less constrained.
- By Application:
- High-speed Trains: High-power demand units for speeds exceeding 250 km/h.
- Metros: Compact and lightweight transformers for urban transit.
- Electric Locomotives: Heavy-duty units for freight and long-distance passenger rail.
- Tramways: Specialized small-scale transformers for city-wide light rail.
Regional Highlights
- Asia Pacific: The largest and fastest-growing market, led by China's continuous expansion of its high-speed rail network and India's aggressive rail electrification targets. The region accounts for the highest volume of new rolling stock orders globally.
- Europe: A mature market focused on replacement and modernization. Germany, France, and the UK are leaders in adopting eco-friendly transformer technologies and high-speed rail interoperability standards (ERTMS).
- North America: Driven primarily by the modernization of aging commuter rail systems and the development of new high-speed corridors like the Brightline in Florida and projects in California.
- Middle East & Africa: An emerging market with significant investments in high-speed rail projects in Saudi Arabia (Haramain) and North Africa, aimed at diversifying economies and improving logistics.
- Latin America: Growth is centered around urban metro projects in major capitals like Sao Paulo, Santiago, and Mexico City to improve urban mobility.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Traction Transformers Market.- ABB (Hitachi Energy)
- Siemens AG
- Alstom
- Mitsubishi Electric Corporation
- CRRC Corporation Limited
- JST Transformateurs
- Schneider Electric
- General Electric
- Toshiba Corporation
- CG Power and Industrial Solutions
- Hyosung Heavy Industries
- Wilson Transformer Company
- EMCO Limited
- Bharat Heavy Electricals Limited (BHEL)
- Kirloskar Electric Company
- Setrans Holding
- Hind Rectifiers Limited
Frequently Asked Questions
What is the current market size of the global traction transformers industry?
The global traction transformers market is estimated at USD 2.10 Billion in 2025 and is expected to reach USD 4.05 Billion by 2034, growing at a CAGR of 6.8%.
Which region holds the largest share of the traction transformers market?
Asia Pacific is the largest market, driven by extensive rail infrastructure projects and rapid urbanization in China and India, accounting for over 45% of the global market share.
What are the primary drivers for the growth of this market?
Key drivers include the global shift toward electric rolling stock to meet climate goals, the expansion of high-speed rail networks, and the proliferation of metro systems in emerging economies.
How is technology changing the design of traction transformers?
Innovation is focused on weight reduction, the use of biodegradable ester oils for insulation, and the integration of IoT sensors for predictive maintenance and enhanced operational reliability.
What are the different mounting positions for traction transformers?
Traction transformers are typically mounted in three positions: on the roof, under the frame (underfloor), or within the machine room of the locomotive, depending on the rolling stock design and space availability.
Author
S
Seema Bhateja is a Manger Energy and Power Research Industry with 7+ years of experience in the Energy and Power Industry. She specializes in energy market intelligence, power generation analysis, renewable energy assessment, demand forecasting, competitive benchmarking, grid infrastructure evaluation, regulatory landscape analysis, market sizing, and investment trend analysis across conventional and clean energy sectors. Her research integrates industry expertise with data-driven methodologies to help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, anticipate evolving market trends, and strengthen their competitive positioning in the global energy and power market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
