Electrodeionization Market
Electrodeionization Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711026 | Published On : September 29, 2026 |
Format : 


 | Author : Seema Bhateja
Electrodeionization Market Size
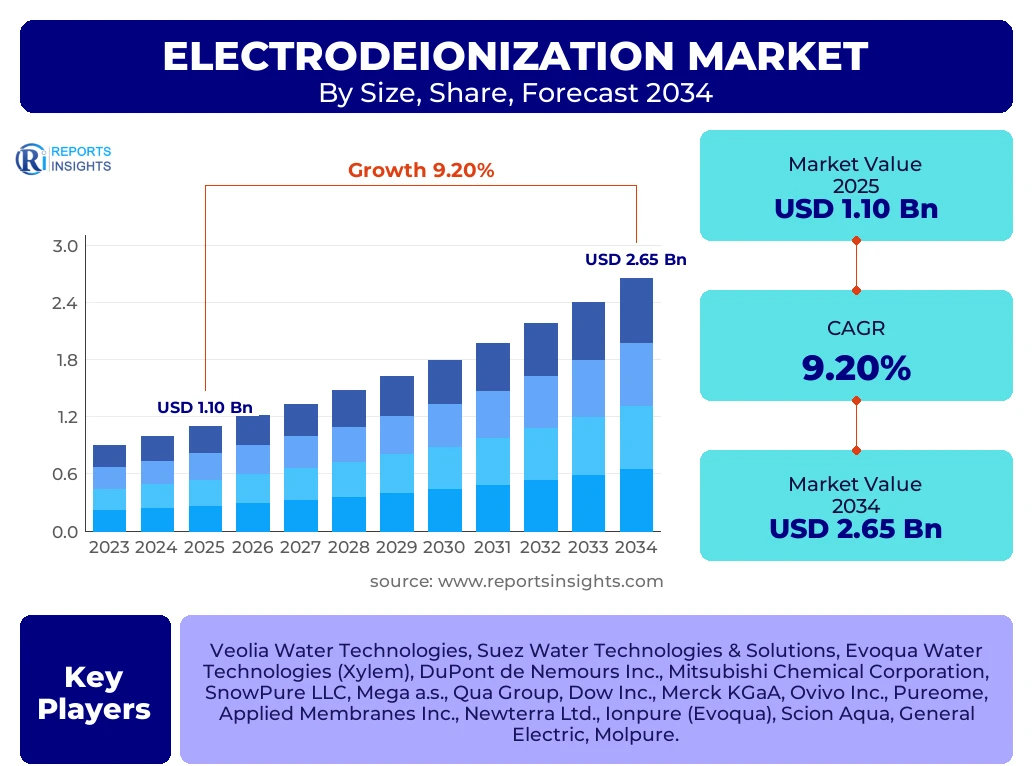
According to Reports Insights Consulting Pvt Ltd, The Electrodeionization Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 9.2% between 2026 and 2034. The market is estimated at USD 1.20 Billion in 2026 and is projected to reach USD 2.65 Billion by the end of the forecast period in 2034.
Key Electrodeionization Market Trends & Insights
The global Electrodeionization market is undergoing a significant transformation driven by the transition toward chemical-free water treatment solutions and the increasing demand for ultrapure water (UPW) in high-precision manufacturing. Market trends indicate a strong shift toward integrated membrane systems, where electrodeionization is coupled with reverse osmosis to provide a continuous, reliable, and environmentally sustainable purification process. Regional insights highlight that while North America remains a dominant force due to its established pharmaceutical and semiconductor industries, the Asia-Pacific region is experiencing the highest growth rate, fueled by rapid industrialization and government initiatives for wastewater management. Competitive benchmarking reveals that leading companies are focusing on modular system designs and digitalization, incorporating IoT sensors to monitor stack performance and water conductivity in real-time, thereby reducing operational downtime and optimizing energy consumption.
- Asia-Pacific is the fastest-growing region, driven by massive investments in semiconductor fabrication and pharmaceutical manufacturing in China and India.
- North America currently holds the largest market share, supported by stringent EPA regulations and the presence of major technology providers.
- The Power Generation Segment remains the largest end-user by value, requiring consistent ultrapure water for high-pressure boiler feed to prevent scaling and corrosion.
- Modular CEDI Systems are becoming the preferred technology choice for small-to-medium enterprises due to their scalability and ease of maintenance.
Key Takeaways Electrodeionization Market Size & Forecast
The market for electrodeionization is characterized by robust growth in industries where water purity is non-negotiable. The forecast indicates that the pharmaceutical and microelectronics sectors will be the primary engines of market expansion, as both industries require water with resistivity levels reaching 18.2 MOhm-cm. Strategic analysis suggests that the market will benefit from the global push for "Green Chemistry," as EDI eliminates the need for hazardous bulk chemical regeneration associated with traditional ion exchange beds. Stakeholders are increasingly prioritizing systems that offer lower total cost of ownership (TCO) and a reduced physical footprint, leading to the obsolescence of older, labor-intensive deionization technologies in developed economies.
- The United States is the leading country in market value, supported by a high density of biotechnology and power facilities.
- Continuous Electrodeionization (CEDI) accounts for over 85% of the product segment, preferred for its ability to operate without interruption for regeneration.
- Sustainability is a primary market driver, with corporations adopting EDI to meet Environmental, Social, and Governance (ESG) targets by reducing chemical discharge.
- Strategic Partnerships between membrane manufacturers and system integrators are accelerating the deployment of advanced water recovery systems in water-stressed regions.
Electrodeionization Market Drivers Analysis
The primary driver for the Electrodeionization market is the intensifying demand for ultrapure water across high-tech manufacturing sectors. In the semiconductor industry, as nodes shrink, the tolerance for ionic contaminants becomes virtually zero, necessitating the high-efficiency removal provided by EDI. Furthermore, the pharmaceutical industry is increasingly adopting EDI to comply with rigorous standards such as the United States Pharmacopeia (USP) and European Pharmacopoeia (Ph. Eur.), which emphasize the reliability and consistency of water for injection (WFI) and purified water (PW) systems.
Environmental regulations also play a critical role in driving adoption. Traditional ion exchange processes require the storage and handling of large quantities of sulfuric acid and caustic soda for resin regeneration, posing significant safety and disposal risks. Electrodeionization offers a sustainable alternative that uses electricity for regeneration, significantly reducing the environmental footprint and simplifying compliance with wastewater discharge limits. This shift is particularly evident in the European Union and North America, where industrial discharge standards are becoming progressively more stringent.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Semiconductor Industry Expansion | +2.5% | Taiwan, South Korea, USA | 2025 - 2034 |
| Shift from Chemical to Electrical Regeneration | +2.1% | Global | 2025 - 2030 |
| Stringent Pharmaceutical Water Standards | +1.8% | Europe, USA, India | 2025 - 2034 |
Electrodeionization Market Restraints Analysis
A significant restraint facing the Electrodeionization market is the high initial capital expenditure compared to conventional ion exchange systems. While the long-term operational costs of EDI are lower due to reduced chemical consumption and labor, the upfront investment for high-quality membrane stacks and power supply units can be a barrier for small-scale industrial players. This financial hurdle is particularly pronounced in price-sensitive markets within the developing world, where traditional methods are still viewed as more accessible in the short term.
Technical limitations regarding feedwater quality also act as a constraint. EDI systems are sensitive to feedwater hardness, silica content, and organic carbon levels. If the pretreatment stage (typically reverse osmosis) is not functioning optimally, the EDI membranes and resin can become fouled or scaled, leading to expensive repairs and stack replacements. This dependency on high-quality pretreatment adds complexity to system design and requires specialized technical expertise for maintenance, which may not be readily available in all geographical regions.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Capital Expenditure | -1.2% | Developing Economies (APAC, LATAM) | 2025 - 2028 |
| Sensitivity to Feedwater Impurities | -0.8% | Global | Continuous |
Electrodeionization Market Opportunities Analysis
The burgeoning green hydrogen economy presents a massive opportunity for the Electrodeionization market. The production of hydrogen via electrolysis requires massive quantities of high-purity water to protect the electrolyzer membranes and electrodes from degradation. As governments worldwide commit to decarbonization and invest billions in hydrogen infrastructure, the demand for industrial-scale EDI systems to provide feedwater for electrolyzers is expected to surge, creating a new and highly lucrative vertical for market participants.
Advancements in membrane technology and modularity offer further opportunities for market penetration. Innovations in thin-film membranes and low-energy EDI stacks are making the technology more efficient and cost-effective. Furthermore, the development of specialized EDI systems for the recovery and recycling of industrial wastewater in "Zero Liquid Discharge" (ZLD) plants provides a significant growth path. As water scarcity becomes a global crisis, industries are looking for ways to close the water loop, and EDI’s ability to polish reclaimed water to high standards makes it a vital component of circular water management strategies.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Green Hydrogen Production Feedwater | +3.2% | Germany, Australia, USA, Chile | 2027 - 2034 |
| Zero Liquid Discharge (ZLD) Adoption | +1.5% | China, India, Middle East | 2026 - 2034 |
| Digitalization & IoT Integration | +0.9% | Global | 2025 - 2030 |
Electrodeionization Market Challenges Impact Analysis
A primary challenge for the market is the presence of established alternative technologies. While EDI is superior in many ultrapure water applications, advances in Mixed Bed Ion Exchange (MBDI) resins and the emergence of other membrane-based technologies continue to provide competition. In sectors where water purity requirements are less stringent, or where capital budgets are restricted, these alternative solutions remain strong contenders, slowing the universal adoption of EDI.
Logistical and supply chain issues related to specialized ion-exchange membranes also pose a challenge. The manufacturing of high-performance EDI membranes involves complex chemical processes and a limited number of specialized global suppliers. Any disruption in the supply of these critical components can lead to project delays and price volatility. Additionally, the lack of standardized training for service technicians in emerging markets can lead to improper system operation, negatively impacting the reputation of EDI technology among local industrial users.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Competition from Mixed Bed Deionization | -1.0% | Global | Continuous |
| Supply Chain Volatility for Ion-Exchange Resins | -0.5% | Global | 2025 - 2027 |
Electrodeionization Market - Updated Report Scope
This report provides a comprehensive analysis of the global Electrodeionization market, covering technical specifications, economic factors, and competitive dynamics. It evaluates the shift from traditional deionization to electrical-based systems, analyzing the market through multiple lenses including product type, application, end-user, and geography. The scope includes a detailed assessment of the impact of environmental regulations and the role of EDI in the emerging green energy sector, providing stakeholders with actionable insights for strategic planning and investment.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.10 Billion |
| Market Forecast in 2034 | USD 2.65 Billion |
| Growth Rate | 9.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Veolia Water Technologies, Suez Water Technologies & Solutions, Evoqua Water Technologies (Xylem), DuPont de Nemours Inc., Mitsubishi Chemical Corporation, SnowPure LLC, Mega a.s., Qua Group, Dow Inc., Merck KGaA, Ovivo Inc., Pureome, Applied Membranes Inc., Newterra Ltd., Ionpure (Evoqua), Scion Aqua, General Electric, Molpure. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented by type, application, and end-user, with Continuous Electrodeionization (CEDI) dominating the technology landscape due to its ability to maintain water quality without downtime. The microelectronics and pharmaceutical sectors represent the highest quality demand, while the power sector provides the highest volume demand. Recent analysis shows a growing sub-segment for "Small-scale EDI" used in laboratory environments where space and ease of use are prioritized over high throughput.
- By Product Type: Continuous Electrodeionization (CEDI), Batch Electrodeionization.
- By Application: Boiler Feed Water, Ultra-Pure Water (UPW), Process Water, Wastewater Treatment & Recovery.
- By End-User Industry: Pharmaceuticals, Biotechnology, Microelectronics, Semiconductors, Power Plants, Chemical Processing, Food & Beverage, Research Laboratories.
- By Component: Membrane Stacks, Power Supplies, Control Systems, Ancillary Skid Equipment.
Regional Highlights
- North America: The largest market share holder, dominated by the United States due to the high concentration of advanced semiconductor fabs and world-leading pharmaceutical companies.
- Asia-Pacific: The fastest-growing region with an expected CAGR of over 11%. China, India, and Taiwan are major hubs for electronics manufacturing and are rapidly upgrading their power infrastructure.
- Europe: A mature market characterized by high adoption of sustainable technologies. Germany and the UK are leading in the integration of EDI for green hydrogen production.
- Middle East & Africa: Growing demand for industrial water treatment in desalination-dependent nations, particularly in the oil and gas and power sectors.
- Latin America: Steady growth driven by the pharmaceutical manufacturing base in Brazil and Mexico.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Electrodeionization Market.- Veolia Water Technologies
- Suez Water Technologies & Solutions
- Evoqua Water Technologies (Xylem Inc.)
- DuPont de Nemours, Inc.
- Mitsubishi Chemical Corporation
- SnowPure, LLC
- Mega a.s.
- Qua Group
- Dow Inc.
- Merck KGaA
- Ovivo Inc.
- Applied Membranes Inc.
- Newterra Ltd.
- Scion Aqua
- Toray Industries, Inc.
- Hydro-Electrodeionization Technologies
- OriginClear Inc.
- Pure Aqua, Inc.
Frequently Asked Questions
What is the primary advantage of Electrodeionization over traditional Ion Exchange?
The primary advantage is the continuous regeneration of ion-exchange resins using an electrical current, which eliminates the need for hazardous regeneration chemicals (acid and caustic), reduces downtime, and lowers long-term operational costs.
Which industry is the largest consumer of Electrodeionization systems?
The Power Generation industry is historically the largest consumer, utilizing EDI for high-pressure boiler feed water. However, the Semiconductor and Pharmaceutical industries are the fastest-growing sectors due to their requirement for consistent 18.2 MOhm-cm water quality.
How does the growth of the Green Hydrogen market impact the EDI market?
Green Hydrogen production requires extremely pure water to ensure the longevity and efficiency of electrolyzers. EDI is the preferred technology for this polishing step, creating a significant new revenue stream for EDI manufacturers as the hydrogen economy expands.
What are the key technical challenges in maintaining an EDI system?
The main challenges include ensuring high-quality feedwater (usually RO permeate) to prevent scaling from hardness or silica and fouling from organic carbons. Proper maintenance of the DC power supply and monitoring of stack pressure drops are also critical for system longevity.
What is the expected market growth rate for the forecast period 2025-2034?
The Electrodeionization market is expected to grow at a CAGR of 9.2%, reaching a projected value of USD 2.65 Billion by 2034, driven by industrial modernization and environmental sustainability trends.
Author
S
Seema Bhateja is a Manger Energy and Power Research Industry with 7+ years of experience in the Energy and Power Industry. She specializes in energy market intelligence, power generation analysis, renewable energy assessment, demand forecasting, competitive benchmarking, grid infrastructure evaluation, regulatory landscape analysis, market sizing, and investment trend analysis across conventional and clean energy sectors. Her research integrates industry expertise with data-driven methodologies to help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, anticipate evolving market trends, and strengthen their competitive positioning in the global energy and power market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted