Takaful Insurance Market
Takaful Insurance Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711887 | Published On : November 20, 2026 |
Format : 


 | Author : Ram Krishnan
Takaful Insurance Market Size
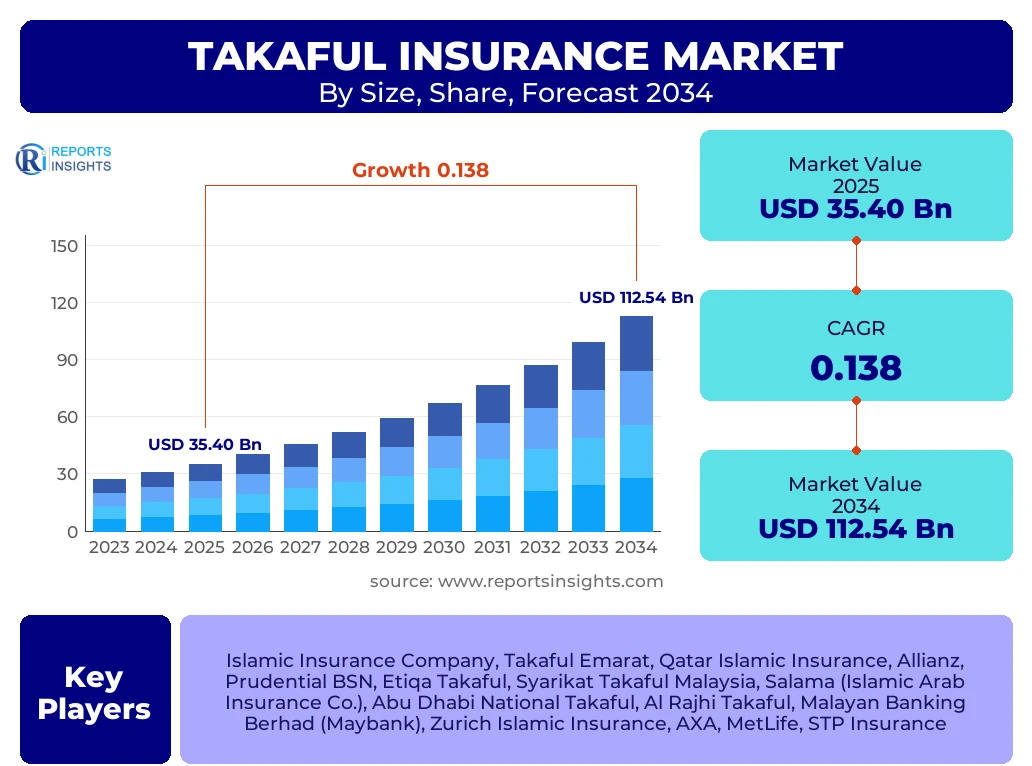
According to Reports Insights Consulting Pvt Ltd, The Takaful Insurance Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 13.8% between 2025 and 2034. The market is estimated at USD 40.28 Billion in 2026 and is projected to reach USD 112.54 Billion by the end of the forecast period in 2034.
Key Takaful Insurance Market Trends & Insights
The Takaful insurance landscape is undergoing a profound transformation driven by the convergence of digital innovation and an increasing global preference for ethical, Sharia-compliant financial products. As modern consumers seek transparency and mutual risk-sharing over traditional risk-transfer models, Takaful providers are leveraging advanced data analytics and blockchain technology to streamline claims processing and enhance surplus distribution mechanisms. This evolution is particularly visible in the Middle East and Southeast Asia, where regulatory frameworks are becoming more sophisticated, fostering an environment conducive to cross-border expansion and the introduction of hybrid Takaful models that cater to diverse risk appetites. Furthermore, the integration of Environmental, Social, and Governance (ESG) criteria into Takaful investment portfolios is aligning Islamic insurance with the global sustainable finance movement, attracting a broader demographic of ethically conscious investors beyond the traditional Muslim population.
- Middle East and Africa (MEA) remains the largest region in terms of market share, underpinned by high Sharia-compliance awareness and sovereign wealth support.
- Asia Pacific (APAC), led by Malaysia and Indonesia, is the fastest-growing region due to favorable government mandates and a rapidly expanding middle-class population.
- The Life/Family Takaful segment represents the largest market share, driven by increasing long-term financial planning and mortality protection needs in emerging economies.
- Digital Takaful and Insurtech integrations are emerging as the most significant trend, reducing operational costs and improving accessibility for underserved rural populations.
Key Takeaways Takaful Insurance Market Size & Forecast
The global Takaful insurance market is entering a high-growth phase, characterized by structural shifts from niche religious offerings to mainstream financial solutions. The forecast period indicates a robust CAGR, supported by the digitalization of distribution channels and the implementation of more rigorous capital adequacy frameworks by central banks. Stakeholders are focusing on product diversification, moving beyond basic motor and health Takaful into specialized areas such as cyber Takaful, marine, and agricultural coverage. The market's expansion is not limited to Islamic majority nations; significant interest is emerging in Western markets with substantial Muslim minorities, presenting untapped opportunities for global insurers to offer inclusive products. The synergy between Takaful and the broader Islamic fintech ecosystem is expected to be a primary catalyst for capital accumulation and market penetration through 2034.
- Saudi Arabia holds the leading position in the MEA region, contributing significantly to the global market value through its mandatory health and motor insurance policies.
- Malaysia continues to be the global benchmark for Takaful regulation and innovation, serving as a hub for product development and Sharia governance excellence.
- The shift toward hybrid models (Wakala-Mudaraba) is optimizing the balance between management fees and profit-sharing, enhancing the competitiveness of Takaful against conventional insurance.
- Technological adoption, particularly AI-driven underwriting, is expected to reduce the protection gap by offering more personalized and affordable Takaful solutions.
Takaful Insurance Market Drivers Analysis
The growth of the Takaful insurance market is fundamentally anchored by demographic shifts and the modernization of Islamic financial regulations. As the global Muslim population continues to grow, particularly in youth demographics, the demand for financial products that align with religious values is surging. This is further bolstered by government initiatives in countries like Indonesia and Saudi Arabia, where national visions for Islamic finance are prioritizing Takaful as a key pillar of economic stability and financial inclusion. Additionally, the inherent ethical nature of the Takaful model, which emphasizes mutual cooperation and the absence of uncertainty (Gharar), is gaining traction among non-Muslim consumers who are disillusioned with the opacity of traditional financial institutions.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expanding Muslim Demographic & Financial Literacy | +4.2% | Global (High in MEA and APAC) | 2025 - 2034 |
| Government Support & Regulatory Standardization | +3.5% | Saudi Arabia, UAE, Malaysia | 2025 - 2030 |
| Digital Transformation & Insurtech Adoption | +3.1% | UAE, Indonesia, United Kingdom | 2026 - 2034 |
| Growth in Sharia-Compliant Investment Opportunities | +3.0% | Qatar, Kuwait, Malaysia | 2025 - 2034 |
Takaful Insurance Market Restraints Analysis
Despite the optimistic growth trajectory, the Takaful market faces significant headwinds related to regulatory fragmentation and a lack of standardized Sharia interpretations across different jurisdictions. The absence of a global unified regulatory body leads to inconsistencies in how Takaful products are structured and governed, which can confuse international investors and limit cross-border scalability. Furthermore, Takaful operators often struggle with lower economies of scale compared to their conventional counterparts, leading to higher operational costs that are sometimes passed on to the participants, potentially making the products less competitive in price-sensitive markets.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Lack of Global Sharia Standardization | -2.1% | Global | 2025 - 2034 |
| Limited Awareness in Non-OIC Countries | -1.5% | Europe, North America | 2025 - 2028 |
| High Operational Costs & Lack of Scale | -1.2% | Emerging African Markets | 2025 - 2030 |
Takaful Insurance Market Opportunities Analysis
The emergence of Micro-Takaful and the integration of sustainable finance represent two of the most significant opportunities for the market in the coming decade. Micro-Takaful offers a pathway to reach millions of low-income individuals in developing nations who are currently excluded from the formal insurance sector, providing them with affordable protection against health crises, agricultural losses, and natural disasters. Moreover, the alignment of Takaful principles with ESG investing creates a unique value proposition for institutional investors looking for ethical assets. By focusing on green Takaful and socially responsible investment (SRI) Sukuk, operators can attract significant capital from global sustainability funds.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Micro-Takaful for Underserved Populations | +4.8% | Indonesia, Pakistan, Nigeria | 2026 - 2034 |
| ESG-Aligned Takaful Products | +3.9% | EU, UAE, Malaysia | 2025 - 2034 |
| Corporate & Commercial Takaful Expansion | +2.5% | GCC Countries | 2027 - 2034 |
Takaful Insurance Market Challenges Impact Analysis
One of the primary challenges facing Takaful operators is the shortage of qualified professionals who possess expertise in both actuarial science and Sharia law. This talent gap hinders the development of sophisticated risk models and the innovation of complex commercial products. Additionally, the industry faces intense competition from established conventional insurers who are increasingly launching Islamic "windows" or subsidiaries. These conventional players often have deeper pockets, better technological infrastructure, and more extensive distribution networks, making it difficult for pure-play Takaful companies to maintain their market share without significant investment in branding and technology.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Talent Shortage in Sharia-Actuarial Disciplines | -1.8% | Global | 2025 - 2034 |
| Intense Competition from Conventional Windows | -1.4% | Malaysia, UAE, Qatar | 2025 - 2034 |
| Cybersecurity Risks in Digital Takaful Platforms | -0.9% | Global | 2026 - 2034 |
Takaful Insurance Market - Updated Report Scope
This report provides an exhaustive analysis of the global Takaful insurance market, encompassing life and non-life segments across primary geographic regions. It evaluates the impact of macroeconomic factors, regulatory changes, and technological advancements on market growth. The scope includes a detailed breakdown of different Takaful models—including Wakala, Mudaraba, and Hybrid models—and provides actionable insights for stakeholders ranging from insurance providers to regulatory bodies and technology partners.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 35.40 Billion |
| Market Forecast in 2034 | USD 112.54 Billion |
| Growth Rate | 13.8% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Islamic Insurance Company, Takaful Emarat, Qatar Islamic Insurance, Allianz, Prudential BSN, Etiqa Takaful, Syarikat Takaful Malaysia, Salama (Islamic Arab Insurance Co.), Abu Dhabi National Takaful, Al Rajhi Takaful, Malayan Banking Berhad (Maybank), Zurich Islamic Insurance, AXA, MetLife, STP Insurance |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Takaful insurance market reflects the diverse needs of both individual and corporate participants. The Life or Family Takaful segment continues to dominate the market as more individuals seek long-term savings and protection plans that comply with Sharia principles. In the General Takaful segment, Motor and Health remain the primary contributors due to mandatory insurance requirements in major markets like Saudi Arabia and the UAE. On the distribution side, Bancatakaful—the sale of Takaful products through Islamic banks—is witnessing rapid growth, leveraging the existing trust and large customer bases of Sharia-compliant financial institutions to reach a wider audience.
- By Type:
- Family Takaful (Life Insurance)
- General Takaful:
- Motor Takaful
- Health Takaful
- Fire/Property Takaful
- Marine, Aviation & Transport Takaful
- Other General Takaful
- By Model:
- Wakala (Agency Model)
- Mudaraba (Profit-Sharing Model)
- Hybrid (Wakala-Mudaraba)
- Waqf-based Model
- By Distribution Channel:
- Agents & Brokers
- Bancatakaful (Banking Channel)
- Direct Sales (Digital & Physical)
- Corporate Channels
Regional Highlights
- Middle East: The largest market globally, with Saudi Arabia and the UAE serving as the primary engines of growth. The region benefits from a 100% Sharia-compliant environment in several jurisdictions and high per-capita insurance spending.
- Asia Pacific: The fastest-growing region, driven by Indonesia's massive population and Malaysia's sophisticated regulatory ecosystem. Malaysia is the global leader in Takaful innovation and standardized practices.
- Africa: An emerging frontier for Takaful, particularly in Nigeria and Kenya, where high Muslim populations and a push for financial inclusion are driving the adoption of Micro-Takaful products.
- Europe: Growth is concentrated in the United Kingdom, which acts as a hub for Islamic finance in the West, catering to both the domestic Muslim population and international high-net-worth individuals.
- Latin America: A nascent market with growing interest in ethical finance, although current penetration remains low compared to other regions.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Takaful Insurance Market.- Islamic Insurance Company
- Takaful Emarat
- Qatar Islamic Insurance Company
- Allianz SE (Islamic Division)
- Prudential BSN Takaful Berhad
- Etiqa Takaful Berhad
- Syarikat Takaful Malaysia Keluarga Berhad
- Salama (Islamic Arab Insurance Co.)
- Abu Dhabi National Takaful Co.
- Al Rajhi Takaful
- Malayan Banking Berhad (Maybank)
- Zurich Islamic Insurance
- AXA (Islamic Windows)
- MetLife (Takaful Operations)
- STP Insurance
- Bupa (Takaful Health Services)
- Wafa Assurance
- Dhofar Insurance
- Al-Sagr National Insurance Company
- First Takaful Insurance Company
Frequently Asked Questions
What is the primary difference between Takaful and conventional insurance?
The primary difference lies in the underlying structure; Takaful is based on mutual risk-sharing and cooperation among participants, where premiums are considered contributions to a communal fund, whereas conventional insurance is based on risk-transfer from the insured to the insurer for a profit. Takaful also strictly prohibits interest (Riba) and uncertainty (Gharar).
Which region is expected to witness the highest growth in the Takaful market?
Asia Pacific (APAC) is projected to be the fastest-growing region during the forecast period. This is due to the large Muslim populations in Indonesia, Malaysia, and Pakistan, coupled with supportive government policies and the rapid digitalization of financial services in these countries.
How does the Wakala model work in Takaful?
In the Wakala model, the Takaful operator acts as an agent (Wakeel) for the participants. The operator receives a pre-agreed fee (Wakala fee) for managing the Takaful operations, underwriting, and claims. Any surplus in the Takaful fund after paying claims and expenses belongs to the participants, not the operator.
What are the main growth drivers for the Family Takaful segment?
The Family Takaful segment is driven by increasing awareness of long-term financial security, the growth of the middle class in emerging economies, and the development of education and retirement-linked Sharia-compliant savings products that offer both protection and investment returns.
Can non-Muslims participate in Takaful insurance?
Yes, Takaful insurance is available to everyone regardless of religious affiliation. Many non-Muslims choose Takaful because of its ethical structure, transparency in how funds are managed, and the potential to receive a share of the surplus if claims remain low during the policy period.
Author
R
Ram Krishnan is a Manger Industry Services Research with 7+ years of experience in the Industry Services Industry. He specializes in industrial services market intelligence, service demand forecasting, competitive benchmarking, outsourcing and managed services analysis, operational performance assessment, market sizing, customer behavior analysis, pricing strategy evaluation, and industry trend forecasting across diverse service sectors. His analytical expertise transforms complex market data into actionable insights, enabling organizations to make strategic business decisions, identify growth opportunities, optimize operations, understand evolving market dynamics, and strengthen their competitive positioning in global industry services markets.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
