Long Term Care Private Insurance Market
Long Term Care Private Insurance Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711491 | Published On : November 03, 2026 |
Format : 


 | Author : Ram Krishnan
Long Term Care Private Insurance Market Size
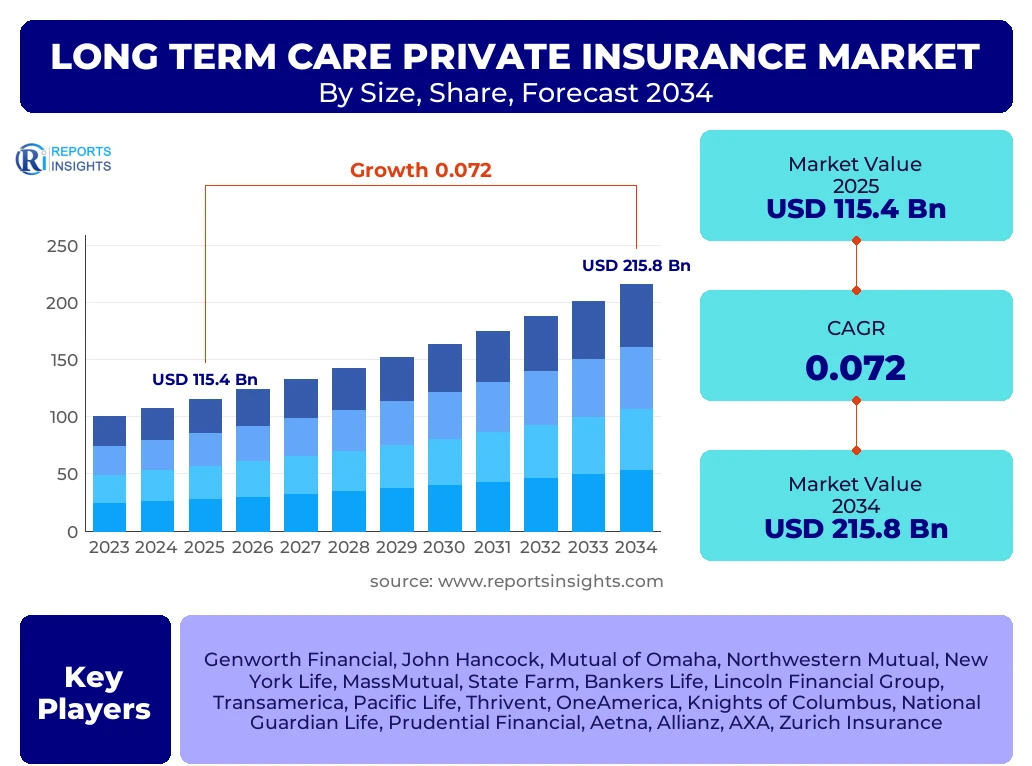
According to Reports Insights Consulting Pvt Ltd, The Long Term Care Private Insurance Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.2% between 2025 and 2034. The market is estimated at USD 123.7 Billion in 2026 and is projected to reach USD 215.8 Billion by the end of the forecast period in 2034.
The global landscape for long term care private insurance is undergoing a significant transformation driven by the fundamental demographic shift often referred to as the Silver Tsunami. As life expectancy increases globally due to advancements in medical technology and public health, the demand for sustained care services—ranging from in-home assistance to specialized nursing facilities—has surged. Private insurance providers are increasingly filling the gap left by overstretched public social safety nets. This market is characterized by a transition from traditional stand-alone policies to more flexible, hybrid products that combine life insurance or annuities with long-term care benefits, providing consumers with more versatile financial planning tools.
Financial volatility and the rising costs of medical services have also necessitated a more robust private insurance framework. In developed economies, the cost of professional care is outpacing general inflation, making out-of-pocket payments unsustainable for the majority of the middle-class population. Consequently, private insurance is viewed no longer as a luxury but as a critical component of comprehensive retirement planning. The market is also seeing a geographic expansion, with emerging economies in the Asia-Pacific region showing heightened interest in private care solutions as traditional family-based care structures begin to dissolve under the pressure of urbanization and changing social norms.
Key Long Term Care Private Insurance Market Trends & Insights
The current market trajectory is heavily influenced by the rise of hybrid insurance products, which integrate long-term care riders with life insurance or deferred annuities. This trend addresses the primary consumer objection to traditional use-it-or-lose-it policies, where premiums are lost if care is never required. By offering a death benefit or cash value alongside care coverage, insurers have successfully expanded their reach into younger demographics, particularly those in their 40s and 50s. Furthermore, the integration of data analytics and wearable technology is allowing insurers to move toward proactive risk management, incentivizing healthy behaviors among policyholders to delay the onset of chronic conditions requiring intensive care.
- Largest Region: North America, specifically the United States, remains the largest market due to high healthcare costs and a well-established private insurance infrastructure.
- Fastest Growing Region: Asia-Pacific is the fastest-growing region, led by Japan, China, and South Korea, where rapidly aging populations and rising middle-class wealth are driving demand.
- Largest Segment: Hybrid Policies (Life + LTC) currently hold the largest market share as they provide perceived value for money and asset protection.
- Key Consumer Trend: Increasing preference for In-Home Care coverage over institutional nursing home coverage, reflecting a global desire for aging-in-place.
Key Takeaways Long Term Care Private Insurance Market Size & Forecast
The market is poised for steady growth as the global population aged 65 and older is expected to double by 2050, creating a massive addressable market for long-term care solutions. Insurers are focusing on refining underwriting processes and utilizing predictive modeling to manage the long-tail risks associated with cognitive impairments like Alzheimers and dementia, which are primary drivers of claims. The shift toward digital distribution channels and simplified underwriting is also lowering the barrier to entry for new policyholders, particularly those looking for supplemental coverage to augment employer-sponsored benefits.
- Dominant Market Position: The United States accounts for over 45% of the global private insurance revenue, supported by tax incentives such as the Long-Term Care Insurance Partnership Program.
- Economic Impact: Rising interest rates in several major economies are improving the profitability of insurers' investment portfolios, allowing for more stable premium pricing compared to the previous decade.
- Service Evolution: The expansion of "Care Coordination" services as a value-added feature is becoming a standard differentiator among top-tier private insurers.
- Regulatory Influence: Government-led initiatives in Europe (e.g., Germany and France) to encourage private-public partnerships are creating a more favorable environment for private market expansion.
Long Term Care Private Insurance Market Drivers Analysis
The primary catalyst for the long-term care private insurance market is the unsustainable trajectory of public healthcare spending. As governments face fiscal constraints, the onus of funding late-life care is shifting toward the individual, making private insurance a vital safety net. Additionally, the increasing prevalence of chronic diseases and the globalization of the nuclear family model have reduced the availability of informal, unpaid family caregivers, necessitating professional, insured services.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Demographic Aging (Silver Tsunami) | +2.8% | Global (Strongest in Japan/Europe) | 2025 - 2034 |
| Shift to Hybrid Product Offerings | +1.5% | United States and Canada | 2025 - 2030 |
| Rising Costs of Professional Nursing Care | +1.2% | United Kingdom and Germany | 2026 - 2034 |
| Digitalization and Underwriting Efficiency | +0.9% | Asia-Pacific (China and India) | 2027 - 2034 |
Long Term Care Private Insurance Market Restraints Analysis
Despite strong demand, the market faces significant headwinds from premium volatility and the historical challenges of accurately pricing long-term risk. Many legacy carriers have exited the market or raised premiums substantially, which has created a degree of consumer skepticism. Strict underwriting criteria also exclude a significant portion of the elderly population who have pre-existing conditions, limiting the market's total reach.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Premium Costs and Inflation Adjustments | -1.1% | United States and France | 2025 - 2034 |
| Stringent Medical Underwriting Barriers | -0.8% | Global | 2025 - 2029 |
| Low Public Awareness of Funding Gaps | -0.5% | Latin America and SE Asia | 2025 - 2034 |
Long Term Care Private Insurance Market Opportunities Analysis
The integration of InsurTech and artificial intelligence presents a massive opportunity for market expansion. AI can help insurers better predict cognitive decline risks, allowing for earlier intervention and care management that can lower the total cost of claims. Furthermore, there is a significant untapped opportunity in the middle-market segment, where consumers require affordable, scaled-down insurance products that focus on home care rather than comprehensive institutional coverage.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into Middle-Income APAC Markets | +1.8% | China and South Korea | 2026 - 2034 |
| Integration of AI for Risk Assessment | +1.2% | United States and Japan | 2027 - 2034 |
| Development of Employer-Sponsored Group Plans | +0.7% | European Union | 2025 - 2032 |
Long Term Care Private Insurance Market Challenges Impact Analysis
The market must navigate a complex regulatory environment that varies significantly by jurisdiction, often complicating the launch of unified global products. Additionally, the long-tail nature of the claims—where a policy might be purchased 30 years before a claim is filed—creates significant interest rate and longevity risk for insurers. Managing these balance sheet exposures remains a central challenge for the industry's long-term sustainability.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Interest Rate Fluctuations | -0.6% | Global (Primarily Mature Markets) | 2025 - 2034 |
| Changing Regulatory Compliance Frameworks | -0.4% | United States (State-level) | 2025 - 2030 |
| Shortage of Skilled Healthcare Workers | -0.7% | Germany and Japan | 2028 - 2034 |
Long Term Care Private Insurance Market - Updated Report Scope
This report provides a comprehensive analysis of the global long-term care private insurance sector, detailing market dynamics across various policy types and payout structures. It includes a deep dive into the shift from traditional to hybrid models, regional regulatory influences, and the impact of technological integration on underwriting and claim management. The scope covers the entire value chain, from major global insurers to niche regional providers, providing a 360-degree view of the market forecast through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 115.4 Billion |
| Market Forecast in 2034 | USD 215.8 Billion |
| Growth Rate | 7.2% CAGR |
| Number of Pages | 254 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Genworth Financial, John Hancock, Mutual of Omaha, Northwestern Mutual, New York Life, MassMutual, State Farm, Bankers Life, Lincoln Financial Group, Transamerica, Pacific Life, Thrivent, OneAmerica, Knights of Columbus, National Guardian Life, Prudential Financial, Aetna, Allianz, AXA, Zurich Insurance |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Long Term Care Private Insurance market is segmented into several critical categories that reflect consumer behavior and financial planning strategies. The most significant shift in recent years has been the move toward Hybrid LTC Products, which now dominate new policy sales. These products appeal to a broader demographic by ensuring that if long-term care is not needed, the policy still provides a death benefit or a return of premium, thus solving the use-it-or-lose-it dilemma. Individual Policies remain the primary revenue generator, although Employer-Sponsored Group Plans are gaining traction as companies look for ways to enhance employee retention in a competitive labor market.
- By Product Type:
- Traditional Long-Term Care Insurance (Indemnity or Reimbursement)
- Hybrid Life Insurance with LTC Rider
- Hybrid Annuities with LTC Rider
- By Payer Type:
- Individual Market
- Group/Employer-Sponsored Market
- By Service Type:
- Institutional Care (Nursing Homes)
- Community-Based Care (Assisted Living)
- Home-Based Care (Professional Home Nursing and Personal Care)
- Adult Day Care Services
- By Demographic:
- Early Planners (Aged 40-54)
- Pre-Retirees (Aged 55-64)
- Retirees (Aged 65+)
Regional Highlights
North America continues to lead the market, primarily due to the high cost of institutional care in the United States, which can exceed USD 100,000 per year for a private room. The presence of tax-qualified policies and the Long-Term Care Partnership programs between state governments and private insurers provide a strong incentive for consumer participation. Europe follows as the second-largest market, with countries like Germany and France having sophisticated private insurance markets that complement mandatory social insurance schemes. In Germany, the private sector plays a crucial role in providing "top-up" coverage for individuals seeking a higher standard of care than provided by the statutory system.
The Asia-Pacific region is identified as the high-growth frontier. Japan has a well-developed market due to its super-aged population, while China is seeing rapid investment in private insurance as its population ages at an unprecedented rate. The Chinese government’s pilot programs for long-term care insurance have paved the way for private insurers to offer supplemental products. Meanwhile, in Latin America and the Middle East, the market is in its nascent stages but is expected to grow as private healthcare infrastructure expands and consumer awareness regarding the financial risks of longevity increases.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Long Term Care Private Insurance Market.- Genworth Financial, Inc.
- John Hancock Life Insurance Company
- Mutual of Omaha Insurance Company
- Northwestern Mutual Life Insurance Company
- New York Life Insurance Company
- Massachusetts Mutual Life Insurance Company (MassMutual)
- State Farm Mutual Automobile Insurance Company
- Bankers Life and Casualty Company
- Lincoln National Corporation (Lincoln Financial Group)
- Transamerica Corporation
- Pacific Life Insurance Company
- Thrivent Financial for Lutherans
- OneAmerica Financial Partners, Inc.
- Knights of Columbus
- National Guardian Life Insurance Company
- Prudential Financial, Inc.
- Aetna (CVS Health)
- Allianz SE
- AXA SA
- Zurich Insurance Group
Frequently Asked Questions
What is the main difference between traditional and hybrid long-term care insurance?
Traditional long-term care insurance policies operate on a "use-it-or-lose-it" basis, similar to auto insurance. Hybrid policies combine long-term care coverage with a life insurance policy or an annuity. If the policyholder does not require care, the policy pays out a death benefit to beneficiaries or maintains a cash value, providing more comprehensive asset protection.
Why is the Asia-Pacific region seeing the fastest growth in this market?
The growth in APAC is driven by rapid demographic aging, particularly in Japan and China, coupled with rising disposable incomes and a shift away from traditional multi-generational living arrangements. As family-based care becomes less feasible, the demand for professional, insured care services is accelerating.
How do rising interest rates affect long-term care insurance premiums?
Rising interest rates generally benefit insurers as they can earn higher returns on the premiums they invest. This often leads to more stable premium pricing for new policies and can reduce the need for future premium hikes on existing policies, making the market more attractive for both providers and consumers.
What role does technology play in the modern long-term care insurance market?
Technology is revolutionizing the market through the use of AI for more accurate risk underwriting and wearable devices for real-time health monitoring. These tools help insurers identify early signs of health decline, allowing for interventions that can improve policyholder outcomes and reduce the cost and duration of long-term care claims.
Are long-term care insurance premiums tax-deductible?
In many jurisdictions, such as the United States, premiums for "Tax-Qualified" long-term care insurance policies are deductible as a medical expense once they exceed a certain percentage of adjusted gross income. Additionally, benefits paid out under these policies are generally received tax-free, further enhancing their value as a financial planning tool.
Author
R
Ram Krishnan is a Manger Industry Services Research with 7+ years of experience in the Industry Services Industry. He specializes in industrial services market intelligence, service demand forecasting, competitive benchmarking, outsourcing and managed services analysis, operational performance assessment, market sizing, customer behavior analysis, pricing strategy evaluation, and industry trend forecasting across diverse service sectors. His analytical expertise transforms complex market data into actionable insights, enabling organizations to make strategic business decisions, identify growth opportunities, optimize operations, understand evolving market dynamics, and strengthen their competitive positioning in global industry services markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
