Commercial Insurance Market
Commercial Insurance Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711596 | Published On : November 07, 2026 |
Format : 


 | Author : Ram Krishnan
Commercial Insurance Market Size
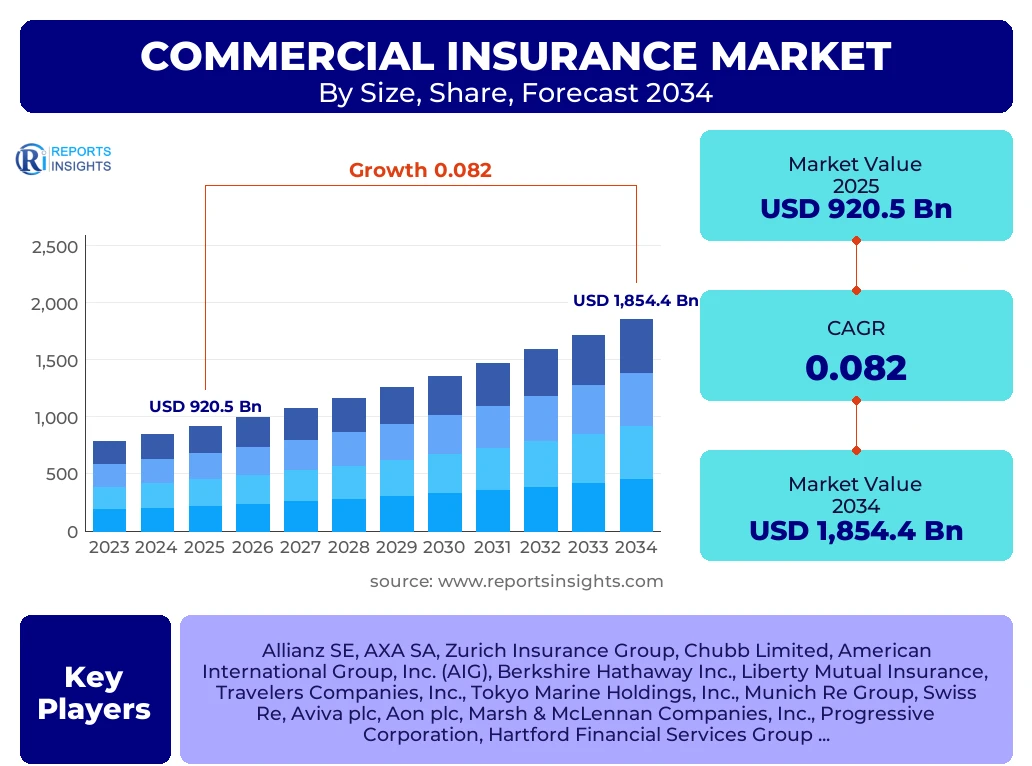
According to Reports Insights Consulting Pvt Ltd, The Commercial Insurance Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.2% between 2025 and 2034. The market is estimated at USD 995.8 Billion in 2026 and is projected to reach USD 1,854.4 Billion by the end of the forecast period in 2034.
Key Commercial Insurance Market Trends & Insights
The global commercial insurance landscape is undergoing a radical transformation driven by the convergence of advanced data analytics, shifting regulatory frameworks, and an evolving risk environment. Organizations are increasingly seeking comprehensive coverage that addresses non-traditional risks such as cyber threats, environmental liabilities, and supply chain disruptions. As businesses pivot toward digital-first models, the demand for modular and usage-based insurance products has surged, allowing for more precise risk pricing and capital allocation. Furthermore, the integration of Artificial Intelligence (AI) and Machine Learning (ML) in underwriting processes is enabling insurers to move away from historical data reliance toward predictive modeling, significantly improving loss ratios and operational efficiency. Competitive benchmarking reveals that industry leaders are prioritizing customer-centric digital interfaces and automated claims processing to differentiate themselves in a hardening market characterized by rising premiums and tighter capacity.
- Largest Region: North America remains the dominant force in the commercial insurance market, supported by a mature regulatory environment and high corporate awareness regarding liability and property risks.
- Fastest Growing Region: Asia-Pacific is anticipated to exhibit the highest growth rate through 2034, fueled by rapid industrialization, increasing infrastructure investments, and expanding SME sectors in China and India.
- Largest Segment by Share: Commercial Property and Casualty (P&C) continues to hold the largest market share, driven by the essential nature of fire, theft, and natural disaster coverage for global enterprises.
- Emerging Trend: The rise of ESG (Environmental, Social, and Governance) integrated underwriting is becoming a standard practice, with insurers assessing the carbon footprint and social impact of their clients before committing capacity.
- Digital Transformation: InsurTech partnerships are accelerating, with traditional carriers adopting cloud-native platforms to streamline the distribution of commercial policies through direct-to-business channels.
Key Takeaways Commercial Insurance Market Size & Forecast
The forecast for the commercial insurance market indicates sustained growth as enterprises grapple with a more complex and volatile global economy. The transition from a soft to a hard market in several jurisdictions has led to increased premium rates, particularly in lines such as directors and officers (D&O) liability and professional indemnity. However, the market size is being bolstered by the emergence of new economic sectors, including the green energy transition and the gig economy, both of which require specialized commercial coverage. Investors and stakeholders are closely monitoring the impact of inflation on claims costs, which is necessitating a more disciplined approach to pricing and portfolio management. The strategic focus is shifting toward long-term resilience, with a focus on narrowing the protection gap for small and medium-sized enterprises (SMEs) that have historically been underinsured.
- Global Market Leadership: The United States and China are the two primary drivers of global premium volume, accounting for a significant portion of the total market valuation.
- High-Growth Verticals: Cyber insurance is projected to be the fastest-growing sub-segment within the commercial sector due to the rising frequency and severity of ransomware and data breach incidents.
- Economic Impact: Rising interest rates in major economies are providing insurers with better investment income on their float, partially offsetting the impact of high claims inflation.
- SME Opportunity: Small and Medium Enterprises represent the largest untapped segment, with a growing demand for digital platforms that offer simplified, bundled insurance solutions.
- Strategic Consolidation: Increased M&A activity among brokers and carriers is aimed at achieving economies of scale and expanding geographic footprints to better serve multinational corporate clients.
Commercial Insurance Market Drivers Analysis
The expansion of the commercial insurance market is primarily driven by the increasing complexity of the global business environment and the subsequent need for sophisticated risk transfer mechanisms. As enterprises expand their operations across borders, they encounter a diverse array of legal and regulatory requirements that necessitate comprehensive liability and property coverage. Additionally, the rapid pace of technological innovation is creating new risk categories that were non-existent a decade ago, driving the development of specialized insurance products. The following table outlines the key drivers influencing the market trajectory and their anticipated impact on the forecast period.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Digital Transformation and AI Integration | +2.4% | Global (Strongest in North America/Europe) | 2025 - 2034 |
| Rising Awareness of Cyber Threats | +1.8% | Western Europe and North America | 2025 - 2030 |
| Infrastructure Growth in Emerging Economies | +1.5% | Asia-Pacific (India, SE Asia) | 2026 - 2034 |
| Stringent Regulatory Compliance Mandates | +1.2% | European Union and North America | 2025 - 2034 |
Commercial Insurance Market Restraints Analysis
Despite the positive growth outlook, several factors act as significant headwinds for the commercial insurance industry. The increasing frequency of catastrophic events, often attributed to climate change, has led to substantial payouts, putting pressure on insurer solvency and leading to higher reinsurance costs. Furthermore, the legal environment in certain regions is becoming increasingly litigious, resulting in social inflation where jury awards and settlements outpace the standard rate of economic inflation. This complexity makes it difficult for insurers to accurately price long-tail risks, leading to capacity withdrawals in certain high-risk segments.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Escalating Social Inflation and Litigation Costs | -1.3% | United States | 2025 - 2034 |
| High Volatility in Reinsurance Markets | -1.1% | Global | 2025 - 2028 |
| Complex Cross-Border Regulatory Variations | -0.8% | Emerging Markets (MEA, LATAM) | 2025 - 2034 |
Commercial Insurance Market Opportunities Analysis
The evolving market dynamics present numerous opportunities for forward-thinking insurance providers to capture new value streams. One of the most significant opportunities lies in the development of parametric insurance products, which offer payouts based on pre-defined triggers rather than traditional loss assessments, providing businesses with faster access to capital after a disaster. Additionally, the transition to a low-carbon economy provides a massive opportunity for insuring renewable energy projects, carbon capture technologies, and green supply chains. Insurers that can leverage real-time data from IoT devices to provide risk mitigation services alongside traditional coverage are likely to see higher customer retention and improved profitability.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into Parametric Insurance Models | +1.6% | Coastal Regions and Agriculture sectors | 2026 - 2034 |
| Renewable Energy and Green Tech Coverage | +1.4% | Europe and China | 2025 - 2034 |
| SME Digital Distribution Platforms | +1.2% | Asia-Pacific and Latin America | 2026 - 2032 |
Commercial Insurance Market Challenges Impact Analysis
Challenges in the commercial insurance market revolve around the difficulty of maintaining technical underwriting profit in an era of unpredictable systemic risks. The interconnectedness of global supply chains means that a single event can trigger losses across multiple lines of insurance and geographic regions. Furthermore, the talent gap in the insurance industry remains a significant hurdle, as the sector competes with tech firms for data scientists and digital architects necessary for modernizing legacy systems. Balancing the need for rapid digitalization with the maintenance of rigorous data privacy and security standards also presents a continuous challenge for global carriers.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Legacy System Modernization Costs | -0.9% | Global (Established Carriers) | 2025 - 2029 |
| Shortage of Skilled Underwriting Talent | -0.7% | North America and Europe | 2025 - 2034 |
| Systemic Risk Accumulation in Cyber/Pandemic | -1.2% | Global | 2025 - 2034 |
Commercial Insurance Market - Updated Report Scope
This report provides a granular analysis of the global commercial insurance market, covering a wide array of product types and distribution channels across five major geographic regions. The scope includes an in-depth evaluation of the competitive landscape, identifying the strategies employed by market leaders to navigate the current hardening cycle. We analyze the impact of macroeconomic variables such as inflation, interest rate fluctuations, and trade policies on premium growth and loss ratios. The report further explores the technological integration of AI, blockchain, and IoT in reshaping the value chain, from risk assessment and pricing to claims settlement and customer engagement.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 920.5 Billion |
| Market Forecast in 2034 | USD 1,854.4 Billion |
| Growth Rate | 8.2% CAGR |
| Number of Pages | 255 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Allianz SE, AXA SA, Zurich Insurance Group, Chubb Limited, American International Group, Inc. (AIG), Berkshire Hathaway Inc., Liberty Mutual Insurance, Travelers Companies, Inc., Tokyo Marine Holdings, Inc., Munich Re Group, Swiss Re, Aviva plc, Aon plc, Marsh & McLennan Companies, Inc., Progressive Corporation, Hartford Financial Services Group, Inc., QBE Insurance Group, Ping An Insurance (Group) Company of China, Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the commercial insurance market reflects the diverse needs of modern businesses, ranging from physical asset protection to intangible risk mitigation. The market is increasingly bifurcated between high-volume, standardized products for small businesses and highly tailored, bespoke solutions for multinational corporations. This analysis delves into the performance and outlook of each segment, highlighting how shifting economic activities are influencing the demand for specific types of coverage. The rise of specialized lines, such as cyber and directors' and officers' liability, demonstrates the market's response to evolving legal and digital threats. Below is a detailed breakdown of the market segments.
- By Type:
- Commercial Property: Protection against damage to physical assets like buildings and equipment.
- Commercial Auto: Coverage for business-owned vehicles and liability arising from their use.
- General Liability: Essential coverage for third-party bodily injury and property damage claims.
- Marine, Aviation & Transport (MAT): Specialized risks associated with global logistics and transportation.
- Workers’ Compensation: Mandatory coverage for employee injuries sustained during employment.
- Professional Liability: Including Errors and Omissions (E&O) and Directors and Officers (D&O) insurance.
- Cyber Insurance: Rapidly growing segment covering data breaches, ransomware, and digital business interruption.
- By Enterprise Size:
- Large Enterprises: Typically require customized, multi-layered programs and captive insurance solutions.
- Small & Medium Enterprises (SMEs): Demand cost-effective, simplified, and bundled insurance packages.
- By Distribution Channel:
- Agents & Brokers: Traditional intermediaries remain vital for complex risk advisory and placements.
- Direct Response: Insurers selling directly to businesses through internal sales teams.
- Online/Digital Platforms: Emerging channel favored by SMEs for quick policy issuance and management.
Regional Highlights
The geographic distribution of the commercial insurance market is influenced by regional economic maturity, regulatory rigor, and the prevalence of natural or systemic risks. North America remains the largest market, largely due to the litigious nature of the US legal system and the sheer volume of commercial assets requiring protection. Europe follows closely, with a strong focus on regulatory compliance and the integration of ESG principles into corporate insurance programs. The Asia-Pacific region is characterized by high growth, driven by rapid urbanization and the expansion of the manufacturing sector. Meanwhile, markets in Latin America and the Middle East are experiencing growth as they modernize their insurance frameworks to attract foreign investment. Each region presents unique challenges and opportunities based on its specific socio-economic landscape.
- North America: The largest market share holder, with a high concentration of global insurers and brokers. The US market is currently experiencing significant rate increases in liability lines due to social inflation.
- Europe: A mature market characterized by stringent Solvency II regulations and a leading role in the global transition toward sustainable underwriting.
- Asia-Pacific: The fastest-growing region, where increasing disposable income and corporate expansion are driving a massive surge in demand for commercial P&C and health coverage.
- Latin America: Showing resilience with growth in countries like Brazil and Mexico, though political and economic volatility remains a concern for capacity providers.
- Middle East & Africa: Significant opportunities exist in infrastructure-led insurance, particularly in the Gulf Cooperation Council (GCC) countries as they diversify their economies.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Commercial Insurance Market.The competitive landscape is dominated by a mix of traditional multi-line global insurers and specialized carriers that focus on niche risks. These organizations are increasingly competing on the basis of technological prowess, capital strength, and the breadth of their global networks. The following companies are identified as the primary influencers in the global commercial insurance market, based on their premium volume, market reach, and innovation in product development.
- Allianz SE
- AXA SA
- Zurich Insurance Group
- Chubb Limited
- American International Group, Inc. (AIG)
- Berkshire Hathaway Inc.
- Liberty Mutual Insurance
- The Travelers Companies, Inc.
- Tokyo Marine Holdings, Inc.
- Munich Re Group
- Swiss Re
- Aviva plc
- Aon plc
- Marsh & McLennan Companies, Inc.
- The Progressive Corporation
- The Hartford Financial Services Group, Inc.
- QBE Insurance Group
- Ping An Insurance (Group) Company of China, Ltd.
- Sompo Holdings, Inc.
- CNA Financial Corporation
Frequently Asked Questions
The following frequently asked questions provide concise insights into the most critical aspects of the commercial insurance market, addressing common concerns regarding market growth, emerging risks, and technological adoption.
What is driving the growth of the global Commercial Insurance market?
Growth is primarily driven by the increasing complexity of corporate risks, including cyber threats and supply chain disruptions, alongside the rapid expansion of the SME sector in emerging economies. Additionally, the integration of AI and big data in underwriting is allowing for more accurate pricing, which attracts more capital and increases market participation.
Which insurance segment is expected to see the fastest growth through 2034?
Cyber insurance is projected to be the fastest-growing segment. As businesses of all sizes digitize their operations, the frequency of cyberattacks has skyrocketed, making cyber coverage an essential component of a modern enterprise risk management strategy.
How is climate change impacting the Commercial Insurance market?
Climate change is causing an increase in the frequency and severity of natural catastrophes, leading to higher claims payouts in the commercial property segment. This has resulted in rising premiums and a shift toward parametric insurance solutions that provide faster payouts for climate-related losses.
What role does digitalization play in the commercial insurance sector?
Digitalization is transforming the entire value chain, from automated underwriting and digital distribution channels to the use of IoT for real-time risk monitoring. It allows insurers to reduce operational costs and provides customers with a more seamless, transparent experience in policy management and claims filing.
Why is North America the largest market for commercial insurance?
North America’s dominance is due to its highly developed economy, a mature legal framework that mandates various forms of commercial liability insurance, and a strong corporate culture of risk mitigation. The presence of the world's largest insurance carriers and brokers further solidifies its market position.
Author
R
Ram Krishnan is a Manger Industry Services Research with 7+ years of experience in the Industry Services Industry. He specializes in industrial services market intelligence, service demand forecasting, competitive benchmarking, outsourcing and managed services analysis, operational performance assessment, market sizing, customer behavior analysis, pricing strategy evaluation, and industry trend forecasting across diverse service sectors. His analytical expertise transforms complex market data into actionable insights, enabling organizations to make strategic business decisions, identify growth opportunities, optimize operations, understand evolving market dynamics, and strengthen their competitive positioning in global industry services markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
