Sludge Management Dewatering Market
Sludge Management Dewatering Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711051 | Published On : October 02, 2026 |
Format : 


 | Author : Jonathan Sikka
Sludge Management Dewatering Market Size
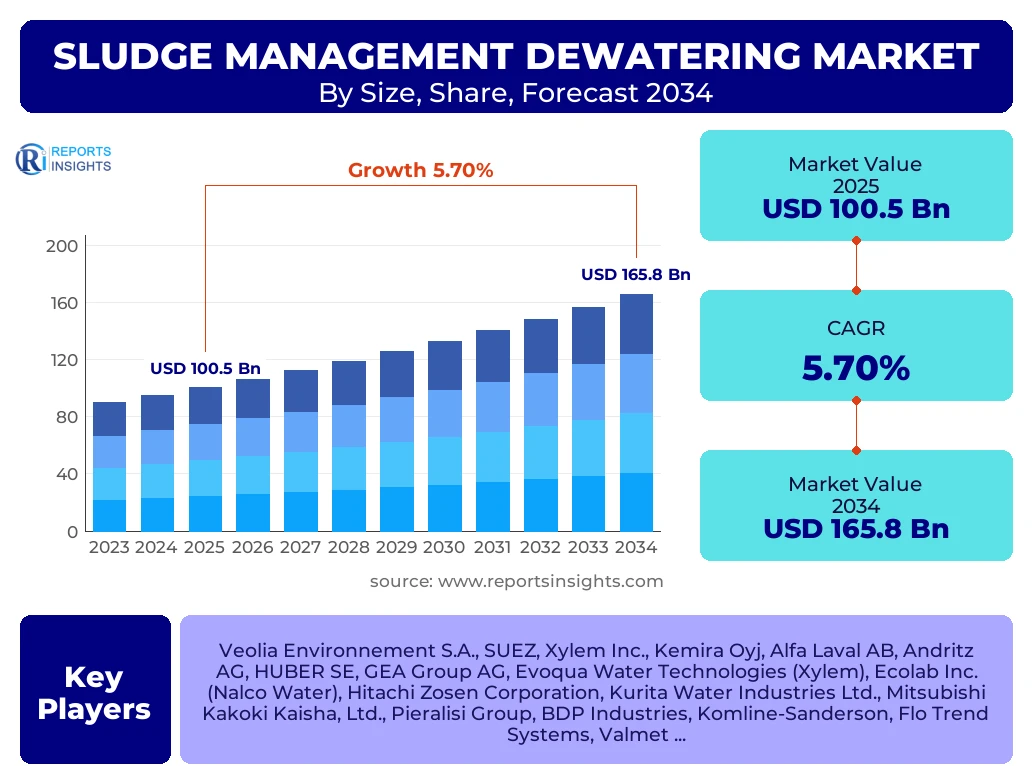
According to Reports Insights Consulting Pvt Ltd, The Sludge Management Dewatering Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.7% between 2026 and 2034. The market is estimated at USD 106.2 Billion in 2026 and is projected to reach USD 165.8 Billion by the end of the forecast period in 2034.
Key Sludge Management Dewatering Market Trends & Insights
The global landscape for sludge management and dewatering is undergoing a profound transformation driven by the transition toward a circular economy and the integration of sophisticated industrial automation. Stakeholders are increasingly focusing on resource recovery, specifically the extraction of energy, phosphorus, and nitrogen from sewage sludge. Competitive benchmarking reveals that leading players are shifting from traditional mechanical dewatering to integrated thermal-mechanical systems that significantly reduce sludge volume while enhancing biogas yield. Regional insights indicate that the Asia-Pacific region is experiencing the highest growth due to rapid urbanization and massive investments in municipal wastewater infrastructure. Furthermore, the market is seeing a surge in demand for mobile dewatering units, which offer flexibility for industrial sites and smaller municipalities. The adoption of AI-driven process control is another pivotal trend, allowing for real-time optimization of polymer dosing and energy consumption, thereby lowering operational expenditures and improving the environmental footprint of wastewater treatment plants.
- The Asia-Pacific region is identified as the fastest-growing market due to aggressive environmental policy implementation in China and India.
- North America remains the largest market by value, supported by advanced technological adoption and stringent EPA regulations.
- The Centrifugation segment holds the largest market share among technologies owing to its high efficiency and continuous operation capabilities.
- Municipal wastewater treatment accounts for the largest application segment, driven by global population growth and urban sanitation mandates.
- Sustainability-focused trends, such as sludge-to-energy conversion, are becoming primary drivers for equipment upgrades in mature markets like Europe.
Key Takeaways Sludge Management Dewatering Market Size & Forecast
The market forecast period 2025-2034 suggests a steady upward trajectory, underpinned by the urgent need to manage increasing volumes of industrial and municipal waste. Regulatory frameworks, such as the EU Urban Wastewater Treatment Directive and the Clean Water Act in the United States, are compelling facilities to adopt more efficient dewatering technologies to minimize disposal costs and landfill usage. The market is also witnessing a consolidation phase where major environmental service providers are acquiring specialized technology firms to offer end-to-end sludge management solutions. Data suggests that the integration of Internet of Things (IoT) sensors in dewatering machinery is becoming a standard requirement for enterprise-level stakeholders seeking to enhance predictive maintenance and operational transparency. High growth is also expected in the industrial sector, particularly within the food and beverage and chemical industries, where sludge byproduct management is critical for compliance and brand reputation.
- China is the leading country in terms of capacity expansion, contributing significantly to the global CAGR through massive state-funded infrastructure projects.
- The United States leads in the adoption of advanced thermal drying and incineration technologies paired with dewatering systems.
- Screw press technology is gaining rapid traction in the small-to-mid-sized plant category due to low energy consumption and minimal maintenance requirements.
- The market is shifting from a disposal-centric model to a resource-recovery model, significantly impacting future investment strategies.
- Escalating costs associated with sludge transportation and landfilling are the primary economic catalysts for high-performance dewatering equipment sales.
Sludge Management Dewatering Market Drivers Analysis
The expansion of the sludge management dewatering market is primarily catalyzed by stringent environmental regulations and the global push for sustainable waste management. As urban populations swell, the volume of wastewater increases proportionally, necessitating advanced systems that can handle higher throughput with greater precision. Additionally, the rising cost of sludge disposal is forcing operators to seek technologies that maximize cake solids concentration, thereby reducing the weight and volume of the waste for transport.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Wastewater Discharge Regulations | +1.8% | European Union, North America | 2025 - 2034 |
| Rapid Urbanization and Infrastructure Development | +1.5% | China, India, Southeast Asia | 2025 - 2030 |
| Focus on Resource Recovery (Sludge-to-Energy) | +1.2% | Global | 2027 - 2034 |
| Escalating Landfill Levies and Transportation Costs | +1.2% | United Kingdom, Germany, Japan | 2025 - 2034 |
Sludge Management Dewatering Market Restraints Analysis
Despite the positive growth outlook, the market faces significant restraints, most notably the high initial capital investment required for state-of-the-art dewatering machinery. Small and medium-sized enterprises (SMEs) and developing municipalities often struggle with the financing of these systems. Furthermore, the operational complexity and the need for skilled labor to manage advanced automated systems can hinder adoption in regions with limited technical expertise.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Capital Expenditure (CAPEX) | -0.8% | Emerging Economies (Africa, SE Asia) | 2025 - 2034 |
| High Energy Consumption of Mechanical Systems | -0.5% | Global | 2025 - 2030 |
| Technical Skill Gap in Specialized Operations | -0.4% | Latin America, MEA | 2025 - 2034 |
Sludge Management Dewatering Market Opportunities Analysis
The integration of digital technologies presents a significant opportunity for market players. AI and machine learning applications for real-time monitoring and predictive maintenance can drastically reduce downtime and chemical usage. Additionally, the growing demand for mobile and containerized dewatering units provides a lucrative niche for servicing remote industrial sites, disaster relief areas, and temporary municipal overloads.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Digitalization and IoT-enabled Dewatering | +1.4% | United States, Germany, South Korea | 2026 - 2034 |
| Emergence of Mobile Dewatering Services | +0.9% | North America, Australia | 2025 - 2032 |
| Phosphorus Recovery Technology Integration | +0.7% | European Union | 2028 - 2034 |
Sludge Management Dewatering Market Challenges Impact Analysis
One of the most pressing challenges is the management of emerging contaminants within sludge, such as PFAS (per- and polyfluoroalkyl substances) and microplastics. These contaminants complicate the disposal and reuse of dewatered sludge, leading to stricter regulatory hurdles. Moreover, the fluctuation in chemical prices, particularly for polymers used in flocculation, adds an element of volatility to the operational costs of dewatering facilities.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Management of PFAS and Toxic Residues | -0.6% | United States, EU member states | 2025 - 2034 |
| Volatility in Polymer and Chemical Pricing | -0.5% | Global | 2025 - 2030 |
| Limited Land Availability for Sludge Application | -0.3% | Japan, Singapore, Western Europe | 2025 - 2034 |
Sludge Management Dewatering Market - Updated Report Scope
This comprehensive market report provides a deep-dive analysis into the global sludge management and dewatering industry, covering technological advancements, regulatory shifts, and competitive dynamics. The scope includes a detailed evaluation of mechanical dewatering equipment, chemical conditioning agents, and auxiliary services across both municipal and industrial sectors. The report utilizes statistics-driven forecasting to provide a clear roadmap for stakeholders over the next decade.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 100.5 Billion |
| Market Forecast in 2034 | USD 165.8 Billion |
| Growth Rate | 5.7% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Veolia Environnement S.A., SUEZ, Xylem Inc., Kemira Oyj, Alfa Laval AB, Andritz AG, HUBER SE, GEA Group AG, Evoqua Water Technologies (Xylem), Ecolab Inc. (Nalco Water), Hitachi Zosen Corporation, Kurita Water Industries Ltd., Mitsubishi Kakoki Kaisha, Ltd., Pieralisi Group, BDP Industries, Komline-Sanderson, Flo Trend Systems, Valmet, Phoenix Process Equipment, Hiller GmbH |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented based on technology, application, component, and disposal method. Each segment is analyzed for its growth potential, market share, and technological evolution. Mechanical dewatering remains the core of the market, with centrifuges and belt presses dominating large-scale municipal operations. However, the industrial sector is increasingly adopting specialized screw presses and plate-and-frame filters for high-solids applications. The service component is also growing as facilities move toward long-term maintenance contracts and "as-a-service" business models to manage sludge processing.
- By Technology: Centrifuges lead in high-capacity municipal plants; Screw presses are growing fastest due to energy efficiency; Belt Filter Presses remain standard for cost-effective operations.
- By Application: Municipal sewage treatment is the largest volume contributor; Food & Beverage is the fastest-growing industrial sub-segment.
- By Disposal Method: Landfilling is declining; Incineration and Agricultural land application are seeing divergent regional trends based on local environmental laws.
- By Component: Equipment (Hardware) constitutes the bulk of market value, but Services (Maintenance and Chemicals) provide recurring revenue streams.
Regional Highlights
- North America: The largest market by revenue, characterized by high adoption of advanced thermal drying technologies and strict EPA compliance for biosolid disposal. The US is the primary driver in this region.
- Europe: A mature market focused on the circular economy. Germany, the UK, and France are leaders in implementing sludge-to-energy projects and phosphorus recovery.
- Asia-Pacific: The fastest-growing region. China's "Water Ten Plan" and India's "Namami Gange" program are fueling massive investments in new sludge treatment facilities.
- Middle East & Africa: Significant growth in the GCC countries due to large-scale desalination and wastewater reuse projects to combat water scarcity.
- Latin America: Brazil and Mexico are modernizing their municipal infrastructure, presenting substantial opportunities for international equipment manufacturers.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Sludge Management Dewatering Market.- Veolia Environnement S.A.
- SUEZ
- Xylem Inc.
- Kemira Oyj
- Alfa Laval AB
- Andritz AG
- HUBER SE
- GEA Group AG
- Evoqua Water Technologies (Xylem)
- Ecolab Inc. (Nalco Water)
- Hitachi Zosen Corporation
- Kurita Water Industries Ltd.
- Mitsubishi Kakoki Kaisha, Ltd.
- Pieralisi Group
- BDP Industries
- Komline-Sanderson
- Flo Trend Systems
- Valmet
- Phoenix Process Equipment
- Hiller GmbH
Frequently Asked Questions
What is the projected market size of the Sludge Management Dewatering market by 2034?
The global market is projected to reach approximately USD 165.8 billion by 2034, growing at a steady CAGR of 5.7% from 2025.
Which technology is currently dominating the sludge dewatering market?
Centrifuge technology currently dominates the market due to its high efficiency, continuous operation, and ability to handle large volumes of sludge in municipal treatment plants.
How is the circular economy impacting sludge management?
The circular economy is shifting the focus from simple sludge disposal to resource recovery, specifically using dewatered sludge for biogas production, energy recovery, and nutrient extraction.
What are the primary drivers for market growth in the Asia-Pacific region?
Growth in APAC is driven by rapid urbanization, government-led environmental cleanup initiatives, and massive investments in new wastewater treatment infrastructure, particularly in China and India.
What are the main challenges facing the sludge management industry today?
Key challenges include the high cost of equipment, the management of emerging contaminants like PFAS, and the increasing stringency of regulations regarding landfilling and agricultural application of biosolids.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted