Breast Reconstruction Market
Breast Reconstruction Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711471 | Published On : November 03, 2026 |
Format : 


 | Author : Jonathan Sikka
Breast Reconstruction Market Size
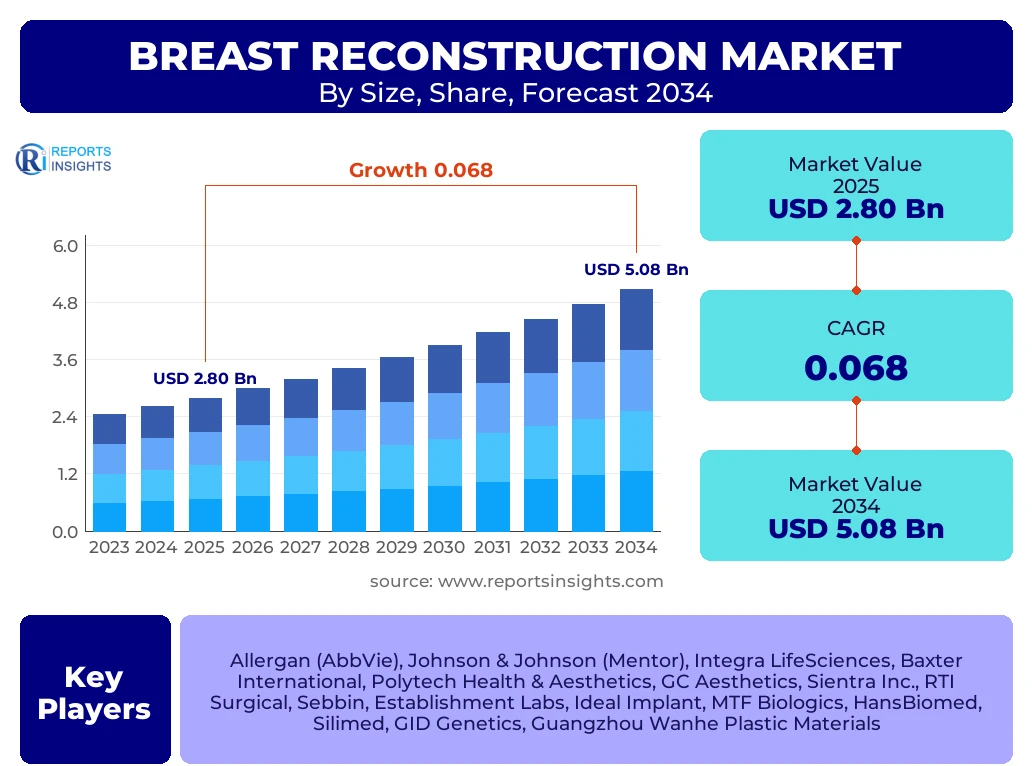
According to Reports Insights Consulting Pvt Ltd, The Breast Reconstruction Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.8% between 2025 and 2034. The market is estimated at USD 2.99 Billion in 2026 and is projected to reach USD 5.08 Billion by the end of the forecast period in 2034.
Key Breast Reconstruction Market Trends & Insights
The global breast reconstruction landscape is undergoing a significant transformation driven by advancements in surgical techniques and a burgeoning emphasis on patient-centric outcomes. Current market intelligence indicates a shift from traditional submuscular placement toward prepectoral reconstruction, which offers reduced post-operative pain and faster recovery times. Furthermore, the integration of 3D printing and digital imaging is revolutionizing preoperative planning, allowing for highly customized aesthetic results that align with individual patient anatomy. Regional analysis reveals that while North America continues to dominate due to favorable reimbursement policies, the Asia-Pacific region is emerging as a high-growth corridor fueled by rising healthcare expenditure and increasing breast cancer awareness initiatives.
- Largest Region: North America remains the primary revenue contributor, holding over 40% of the global market share, supported by advanced healthcare infrastructure and high surgical volume.
- Fastest Growing Region: Asia-Pacific is expected to register the highest CAGR during the forecast period, driven by medical tourism and improving access to oncology care in China and India.
- Largest Segment: Breast implants currently represent the largest product segment, though Acellular Dermal Matrices (ADM) are seeing the most rapid adoption in complex reconstructive procedures.
- Procedural Shift: There is a notable trend toward immediate reconstruction following mastectomy, reducing the psychological burden on patients and optimizing clinical resource utilization.
Key Takeaways Breast Reconstruction Market Size & Forecast
Strategic analysis of the breast reconstruction sector highlights a resilient growth trajectory underpinned by a steady increase in breast cancer survivorship and a diversifying portfolio of prosthetic and biological materials. Stakeholders are increasingly focusing on the synergistic use of implants and fat grafting to achieve superior texture and contour, addressing the growing demand for natural-looking outcomes. The market is also benefiting from a favorable regulatory environment in emerging economies, which is encouraging global manufacturers to expand their localized footprints. As the clinical community shifts toward value-based care, the emphasis is moving beyond simple volume toward long-term patient satisfaction and the reduction of revision surgery rates.
- Market Valuation: The total addressable market is expected to surpass the USD 5 billion mark by 2034, reflecting sustained demand for restorative surgeries.
- Leading Country: The United States leads the global market, accounting for a significant portion of the total value due to high awareness and insurance mandates like the Women’s Health and Cancer Rights Act.
- Technological Influence: The adoption of Acellular Dermal Matrices (ADM) is a critical growth lever, providing structural support and improving the aesthetic quality of implant-based reconstructions.
- Strategic Consolidation: Major players are engaging in aggressive M&A activities to integrate biological materials into their traditional implant portfolios, creating comprehensive surgical solutions.
Breast Reconstruction Market Drivers Analysis
The primary catalyst for market expansion is the rising global incidence of breast cancer, which necessitates post-mastectomy restorative interventions. As screening programs become more sophisticated and accessible, early diagnosis rates are climbing, subsequently increasing the pool of candidates eligible for reconstructive surgery. Furthermore, technological innovations in implant shell design and the development of cohesive silicone gels have significantly enhanced the safety profile of these devices, mitigating patient concerns regarding rupture or leakage. The expansion of medical insurance coverage and specific legislative mandates in several developed nations have also lowered the financial barriers for patients, transforming reconstruction from an elective luxury into a standard component of comprehensive cancer care.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Breast Cancer Prevalence | +2.1% | Global / Europe & North America | 2025 - 2034 |
| Technological Advancement in ADM | +1.5% | United States / Germany | 2025 - 2030 |
| Favorable Reimbursement Policies | +1.2% | United States / Canada / UK | 2026 - 2034 |
| Demand for Minimally Invasive Procedures | +0.9% | Global / APAC | 2027 - 2034 |
Breast Reconstruction Market Restraints Analysis
Despite the positive growth outlook, the market faces constraints primarily rooted in the high cost of advanced reconstructive materials and the associated surgical fees. In many developing regions, the lack of comprehensive insurance coverage for aesthetic restoration remains a significant bottleneck, limiting the procedure to affluent demographic segments. Furthermore, clinical concerns regarding Breast Implant-Associated Anaplastic Large Cell Lymphoma (BIA-ALCL) have led to increased regulatory scrutiny and a shift in patient preference toward autologous (tissue-based) reconstruction, which is more complex and time-consuming. These safety concerns, coupled with the potential for long-term complications such as capsular contracture, necessitate ongoing clinical monitoring and may deter a portion of the patient population.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Surgery and Implants | -1.1% | LATAM / MEA / Emerging APAC | 2025 - 2034 |
| Regulatory Scrutiny and Safety Concerns | -0.8% | Global / EU / USA | 2025 - 2028 |
| Shortage of Skilled Plastic Surgeons | -0.5% | Developing Nations | 2025 - 2034 |
Breast Reconstruction Market Opportunities Analysis
The market presents substantial opportunities in the realm of hybrid reconstruction, which combines autologous fat grafting with traditional implant-based techniques to improve tissue thickness and aesthetic feel. This "best of both worlds" approach is gaining traction among surgeons looking to minimize the visibility of implants while maintaining the structure provided by prosthetics. Additionally, the integration of digital health tools, including AI-driven predictive modeling, offers a significant opportunity for manufacturers to differentiate their products by providing surgeons with precise anatomical mapping. Emerging markets in Latin America and Southeast Asia represent untapped potential, as rising middle-class incomes and investments in specialized oncology centers create new avenues for market entry.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration of AI and 3D Imaging | +1.4% | USA / Japan / South Korea | 2026 - 2034 |
| Expanding Healthcare in Emerging Markets | +1.1% | Brazil / India / China | 2027 - 2034 |
| Development of Bio-compatible Scaffolds | +0.9% | Global / R&D Hubs | 2028 - 2034 |
Breast Reconstruction Market Challenges Impact Analysis
Maintaining long-term clinical safety and ensuring the longevity of reconstructive outcomes remain the foremost challenges for industry participants. The variability in patient anatomy and the physiological response to foreign materials require a diverse range of product specifications, which complicates inventory management and supply chain logistics for manufacturers. Moreover, the rigorous clinical trial requirements for new biomaterials often lead to prolonged time-to-market and high R&D costs. Navigating the diverse regulatory landscapes of international markets, particularly the transition from MDD to MDR in Europe, poses a significant administrative and financial burden on smaller companies, potentially leading to market consolidation.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Regulatory Approval Paths | -0.7% | European Union / China | 2025 - 2027 |
| Risk of Post-operative Complications | -0.6% | Global | 2025 - 2034 |
| Economic Volatility Affecting Elective Care | -0.4% | Global | 2025 - 2026 |
Breast Reconstruction Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the hardware, biologics, and procedural workflows defining the breast reconstruction ecosystem. It provides a granular breakdown of product categories including silicone and saline implants, tissue expanders, and the increasingly vital segment of acellular dermal matrices. The research evaluates the market through the lens of surgical timing—immediate versus delayed reconstruction—and placement techniques, offering stakeholders a clear view of where clinical preferences are shifting. Geographically, the report covers six major regions and over 20 key countries, providing a cross-referenced analysis of regulatory trends, reimbursement landscapes, and competitive dynamics between 2020 and 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 2.80 Billion |
| Market Forecast in 2034 | USD 5.08 Billion |
| Growth Rate | 6.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Allergan (AbbVie), Johnson & Johnson (Mentor), Integra LifeSciences, Baxter International, Polytech Health & Aesthetics, GC Aesthetics, Sientra Inc., RTI Surgical, Sebbin, Establishment Labs, Ideal Implant, MTF Biologics, HansBiomed, Silimed, GID Genetics, Guangzhou Wanhe Plastic Materials |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The breast reconstruction market is segmented into several critical categories that reflect the diversity of patient needs and surgical methodologies. The product segment is primarily dominated by breast implants, which are further categorized by filler material—silicone or saline—with silicone holding the majority share due to its superior aesthetic properties. Tissue expanders represent a vital pre-reconstructive phase, particularly in delayed procedures where skin stretching is required. Acellular Dermal Matrices (ADM) have emerged as a high-value segment, acting as an internal "bra" to support implants and improve the natural appearance of the reconstructed breast. Additionally, the market is segmented by procedure type, where immediate reconstruction (performed at the time of mastectomy) is increasingly preferred over delayed procedures for its psychological benefits and cost-efficiency.
- By Product:
- Breast Implants (Silicone and Saline)
- Tissue Expanders
- Acellular Dermal Matrix (ADM)
- Nipple Reconstruction Products
- By Procedure:
- Immediate Reconstruction
- Delayed Reconstruction
- By Type:
- Implant-based Reconstruction
- Autologous/Tissue-based Reconstruction (FLAP Surgery)
- Hybrid Reconstruction
- By Placement:
- Submuscular Placement
- Prepectoral Placement
- Dual-Plane Placement
- By End-User:
- General Hospitals
- Specialty Oncology Centers
- Ambulatory Surgical Centers (ASCs)
Regional Highlights
North America currently holds the largest market share, a position sustained by the high volume of breast cancer surgeries and a sophisticated insurance landscape that mandates coverage for reconstruction. In the United States, the presence of major industry players and a strong pipeline of innovative products ensure that the region remains at the forefront of the market. Europe follows closely, with countries like Germany, France, and the United Kingdom exhibiting high adoption rates of advanced biologics and ADM. The European market is characterized by stringent quality standards and a strong emphasis on evidence-based surgical outcomes. In contrast, the Asia-Pacific region is the fastest-growing market, driven by rapidly improving healthcare infrastructure in China and India, alongside a growing social acceptance of aesthetic restorative surgeries.
- North America: Largest market valuation with the highest penetration of prepectoral reconstruction techniques.
- Europe: Leading in the adoption of textured and anatomical implants, though shifting toward smoother surfaces following regulatory updates.
- Asia-Pacific: Highest growth rate (CAGR) expected through 2034, fueled by medical tourism in South Korea and Thailand.
- Latin America: Significant growth in Brazil and Mexico, predominantly driven by high demand for combined aesthetic and reconstructive procedures.
- Middle East & Africa: Steady growth observed in the UAE and Saudi Arabia, supported by investments in specialized cancer care centers.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Breast Reconstruction Market.- Allergan (AbbVie Inc.)
- Mentor Worldwide LLC (Johnson & Johnson)
- Integra LifeSciences Corporation
- Baxter International Inc.
- Polytech Health & Aesthetics GmbH
- GC Aesthetics PLC
- Sientra, Inc.
- RTI Surgical
- Laboratoires Arion
- Groupe Sebbin SAS
- Establishment Labs Holdings Inc.
- Ideal Implant Incorporated
- MTF Biologics
- HansBiomed Co., Ltd.
- Silimed Industria de Implantes Ltda.
- GID Genetics
- Guangzhou Wanhe Plastic Materials Co., Ltd.
- PMT Corporation
- Kimal PLC
- AirXpanders, Inc.
Frequently Asked Questions
What is the current market size of the global breast reconstruction industry?
The global breast reconstruction market is estimated to be valued at approximately USD 2.80 billion in 2025 and is projected to grow to over USD 5 billion by 2034, following a CAGR of 6.8%.
What are the primary differences between implant-based and autologous reconstruction?
Implant-based reconstruction uses silicone or saline prosthetics to recreate the breast shape, often requiring less recovery time. Autologous reconstruction uses the patient's own tissue (usually from the abdomen or back), providing a more natural feel and look, though it involves a more complex surgery and longer initial recovery.
How does the use of Acellular Dermal Matrix (ADM) impact surgical outcomes?
ADM acts as a biological scaffold that supports the implant, helps define the breast pocket, and can reduce the incidence of capsular contracture. It is especially useful in prepectoral placement to provide an extra layer of tissue coverage.
Is breast reconstruction typically covered by health insurance?
In many developed nations, including the U.S. (under the Women's Health and Cancer Rights Act), health insurance providers are legally required to cover breast reconstruction surgery following a mastectomy, including procedures on the opposite breast to achieve symmetry.
Which region is expected to show the fastest growth in the next decade?
The Asia-Pacific region is anticipated to be the fastest-growing market due to rising awareness, an increasing number of hospitals specializing in oncology, and a growing middle-class population with access to restorative healthcare.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
