Rubber Tired Gantry (RTG) Crane Market
Rubber Tired Gantry (RTG) Crane Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711340 | Published On : October 28, 2026 |
Format : 


 | Author : Ashraf Shehata
Rubber Tired Gantry (RTG) Crane Market Size
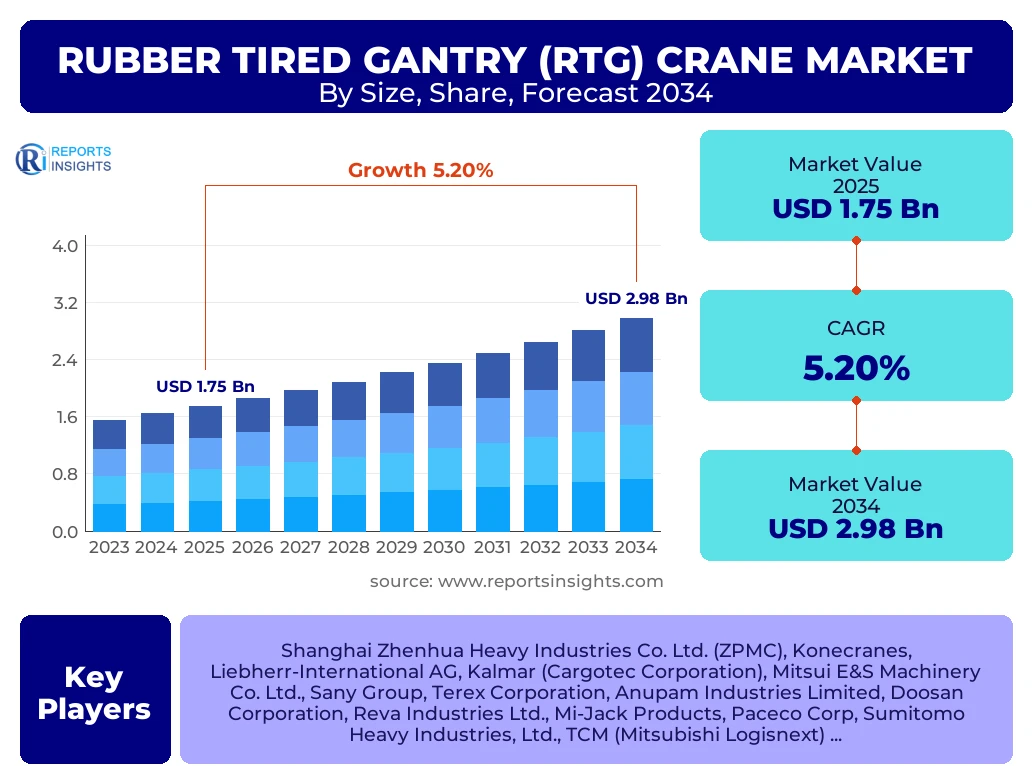
According to Reports Insights Consulting Pvt Ltd, The Rubber Tired Gantry (RTG) Crane Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.2% between 2025 and 2034. The market is estimated at USD 1.84 Billion in 2026 and is projected to reach USD 2.98 Billion by the end of the forecast period in 2034.
Key Rubber Tired Gantry (RTG) Crane Market Trends & Insights
The global Rubber Tired Gantry (RTG) Crane market is undergoing a significant transformation driven by the modernization of port infrastructure and the urgent need for operational efficiency in container terminals. Industry stakeholders are increasingly prioritizing automation and digitalization to mitigate labor costs and enhance safety protocols. A primary trend is the transition from traditional diesel-powered RTGs to fully electric (E-RTG) and hybrid models, which aligns with international maritime decarbonization goals. Furthermore, the integration of Remote Control (RC) and Automated Stacking Crane (ASC) technologies is becoming standard in greenfield port projects and major brownfield upgrades across the globe.
- Largest Region: Asia-Pacific remains the dominant region, accounting for over 45% of the total market share due to its massive port throughput capacities in China, Singapore, and India.
- Fastest Growing Region: The Middle East and Africa (MEA) region is projected to witness the highest CAGR as massive new port developments in Saudi Arabia and the UAE accelerate.
- Largest Segment by Share: 16-Wheel RTG cranes currently hold the largest market share owing to their superior stability and higher lifting capacities required for high-density stacking.
- Leading Power Type: Hybrid and Electric RTGs are seeing the fastest adoption rates as port authorities implement strict emission control regulations.
Key Takeaways Rubber Tired Gantry (RTG) Crane Market Size & Forecast
The global outlook for the Rubber Tired Gantry (RTG) Crane market is robust, characterized by steady capital investment in maritime logistics and intermodal freight transport. The forecast period indicates a shift toward intelligent terminal solutions where RTGs are interconnected via 5G networks for real-time monitoring and predictive maintenance. While the market faces headwinds from high initial capital expenditure, the long-term operational savings and sustainability benefits of advanced RTG systems are compelling port operators to upgrade their aging fleets. China remains the pivotal manufacturing hub and consumer market, dictating much of the global pricing and technological trajectory.
- Global Market Dominance: China is the leading country in both production and consumption of RTG cranes, driven by its Belt and Road Initiative and extensive coastline port network.
- Sustainability Focus: Nearly 60% of new RTG orders in Europe and North America are for electric or zero-emission models.
- Intermodal Growth: The expansion of inland container depots (ICDs) and rail freight corridors is creating a secondary demand stream for smaller, more agile RTG configurations.
- Technological Integration: AI-driven yard management systems are now being bundled with RTG hardware to optimize container shuffling and reduce dwell times.
Rubber Tired Gantry (RTG) Crane Market Drivers Analysis
The primary catalysts for the Rubber Tired Gantry (RTG) Crane market include the escalating volumes of global containerized trade and the subsequent need for high-density terminal storage. As vessel sizes increase, ports must improve their yard productivity to maintain fast turnaround times. Additionally, the global push for Green Ports is driving the replacement of legacy diesel equipment with cleaner alternatives.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Increased Global Container Throughput | +1.5% | Global (High in APAC) | 2025 - 2034 |
| Stringent Maritime Emission Regulations | +1.2% | Europe and North America | 2026 - 2030 |
| Port Automation and Digitalization | +0.9% | Global (High in MEA) | 2025 - 2034 |
| Expansion of Intermodal Rail Networks | +0.6% | North America and India | 2027 - 2034 |
Rubber Tired Gantry (RTG) Crane Market Restraints Analysis
Despite growth, the market faces significant hurdles including the high upfront cost of automated and electric machinery compared to traditional diesel units. Geopolitical tensions and trade protectionism can also disrupt supply chains for critical components like specialized steel and electronic control systems.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Capital Investment (CAPEX) | -0.8% | Global (Emerging Markets) | 2025 - 2034 |
| Complex Maintenance of Automated Systems | -0.4% | Global | 2026 - 2030 |
| Trade Tariffs and Geopolitical Instability | -0.5% | USA-China / EU-Russia | 2025 - 2028 |
Rubber Tired Gantry (RTG) Crane Market Opportunities Analysis
Opportunities abound in the retrofitting of existing diesel RTGs to electric or hybrid versions, allowing port operators to meet environmental targets without full fleet replacement. Furthermore, the development of hydrogen fuel cell-powered RTGs represents a frontier for innovation in zero-emission heavy machinery.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Retrofitting Services for Legacy Fleets | +0.7% | North America and Europe | 2025 - 2032 |
| Hydrogen Fuel Cell Integration | +0.4% | Japan, Korea, and EU | 2028 - 2034 |
| Smart Port Initiatives in Developing Economies | +0.8% | SE Asia and Latin America | 2026 - 2034 |
Rubber Tired Gantry (RTG) Crane Market Challenges Impact Analysis
The main challenges involve the integration of heterogeneous systems where new automated RTGs must work alongside older manual equipment. Additionally, the scarcity of skilled technicians capable of servicing sophisticated electronic and software-driven crane components remains a global bottleneck.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Skilled Labor Shortage for Maintenance | -0.3% | Global | 2025 - 2034 |
| Infrastructure Limitations for Electrification | -0.5% | Africa and Parts of SE Asia | 2025 - 2030 |
| Cybersecurity Risks in Automated Terminals | -0.2% | Developed Markets | 2026 - 2034 |
Rubber Tired Gantry (RTG) Crane Market - Updated Report Scope
This report provides a comprehensive analysis of the global RTG crane landscape, covering technical specifications, power sources, and geographical penetration. It evaluates the impact of macro-economic factors and micro-technical advancements on the market valuation through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.75 Billion |
| Market Forecast in 2034 | USD 2.98 Billion |
| Growth Rate | 5.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Shanghai Zhenhua Heavy Industries Co. Ltd. (ZPMC), Konecranes, Liebherr-International AG, Kalmar (Cargotec Corporation), Mitsui E&S Machinery Co. Ltd., Sany Group, Terex Corporation, Anupam Industries Limited, Doosan Corporation, Reva Industries Ltd., Mi-Jack Products, Paceco Corp, Sumitomo Heavy Industries, Ltd., TCM (Mitsubishi Logisnext), Henan Weihua Heavy Machinery Co., Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented based on physical configuration, power delivery systems, and level of operational autonomy. The 16-wheel RTG segment dominates the market due to the industry shift toward larger container stacks and the need for lower ground pressure. Electrification is the fastest-growing power segment as ports migrate away from diesel to reduce carbon footprints and energy costs.
- By Type:
- 8-Wheel RTG Cranes
- 16-Wheel RTG Cranes
- By Power Source:
- Diesel-Powered
- Electric (E-RTG)
- Hybrid
- Hydrogen Fuel Cell (Emerging)
- By Operation:
- Manual (Operator in Cabin)
- Remote Controlled
- Fully Automated
- By Lifting Capacity:
- Below 40 Tons
- 40 to 50 Tons
- Above 50 Tons
Regional Highlights
- Asia-Pacific: The largest market globally, led by China, South Korea, and Singapore. The region benefits from massive manufacturing output and significant government investment in port infrastructure. China alone accounts for a substantial portion of global RTG production and domestic demand.
- Europe: A pioneer in E-RTG adoption. Major ports like Rotterdam, Hamburg, and Antwerp are leading the way in automation and decarbonization, making Europe a high-value market for advanced technological integrations.
- North America: Focused on modernizing aging West Coast and East Coast ports to improve supply chain resilience. There is a strong trend toward hybrid systems to balance operational flexibility with environmental mandates.
- Middle East & Africa: The fastest-growing region due to ambitious economic diversification plans (e.g., Saudi Vision 2030) that involve building world-class transshipment hubs.
- Latin America: Steady growth driven by port privatizations and the expansion of the Panama Canal, which necessitates larger and more efficient yard equipment in surrounding regional ports.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Rubber Tired Gantry (RTG) Crane Market.- Shanghai Zhenhua Heavy Industries Co. Ltd. (ZPMC)
- Konecranes
- Liebherr-International AG
- Kalmar (Cargotec Corporation)
- Mitsui E&S Machinery Co. Ltd.
- Sany Group
- Terex Corporation
- Anupam Industries Limited
- Doosan Corporation
- Reva Industries Ltd.
- Mi-Jack Products
- Paceco Corp
- Sumitomo Heavy Industries, Ltd.
- TCM (Mitsubishi Logisnext)
- Henan Weihua Heavy Machinery Co., Ltd.
Frequently Asked Questions
What is the current market size of the Rubber Tired Gantry (RTG) Crane industry?
As of 2025, the market is valued at approximately USD 1.75 Billion and is expected to grow steadily at a CAGR of 5.2% over the next decade.
Which power source is becoming the most popular in RTG cranes?
Electric (E-RTG) and Hybrid models are becoming the industry standard due to their ability to significantly reduce CO2 emissions and lower long-term fuel costs compared to traditional diesel units.
Which region holds the largest share of the RTG crane market?
The Asia-Pacific region holds the largest market share, driven by the presence of the worlds busiest container ports and major manufacturers like ZPMC.
What are the main benefits of 16-wheel RTG cranes over 8-wheel versions?
16-wheel RTG cranes offer better stability, higher lifting capacities, and exert lower pressure on the terminal pavement, making them ideal for high-density stacking operations.
How is automation impacting the RTG crane market?
Automation is driving the adoption of remote-controlled and fully automated cranes, which improve safety, provide better operational consistency, and allow for 24/7 port operations with reduced labor dependency.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
