Retail Electricity Market
Retail Electricity Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711612 | Published On : November 08, 2026 |
Format : 


 | Author : Seema Bhateja
Retail Electricity Market Size
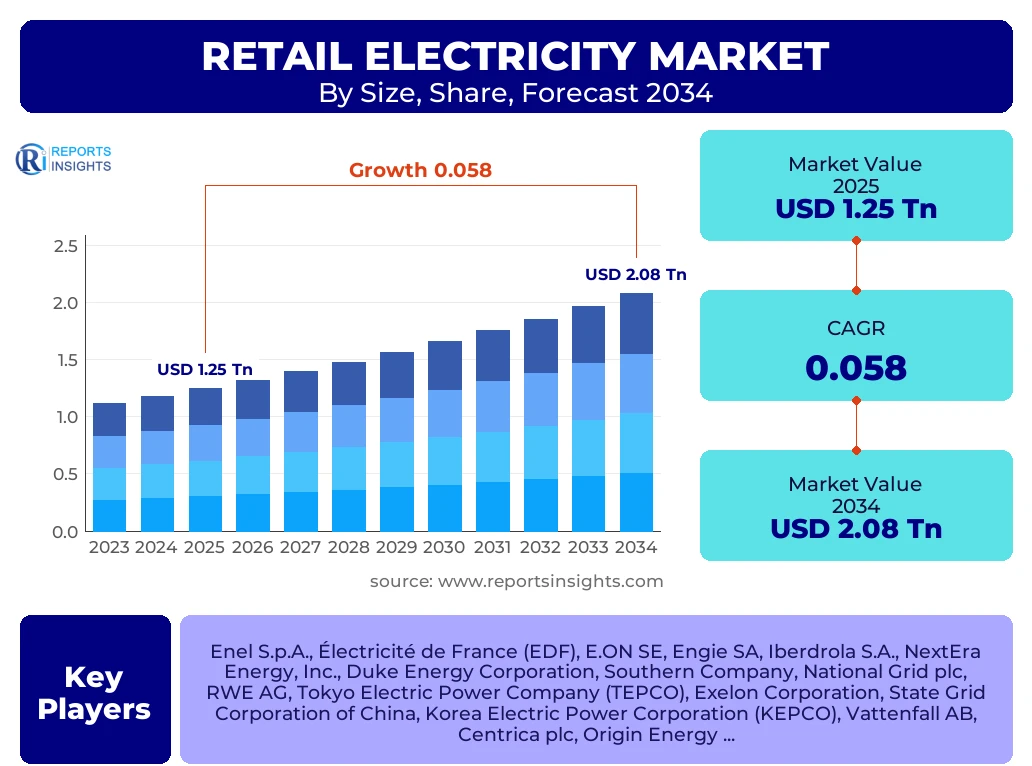
According to Reports Insights Consulting Pvt Ltd, The Retail Electricity Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.8% between 2025 and 2034. The market is estimated at USD 1.32 Trillion in 2026 and is projected to reach USD 2.08 Trillion by the end of the forecast period in 2034.
Key Retail Electricity Market Trends & Insights
The global retail electricity sector is undergoing a profound structural transformation characterized by the "Three Ds": Decarbonization, Decentralization, and Digitalization. As national governments commit to net-zero targets, the retail landscape is shifting from a centralized, commodity-based model to a service-oriented ecosystem. Consumers are no longer passive recipients of energy; they are increasingly becoming "prosumers" who generate, store, and sell electricity back to the grid. This transition is heavily supported by the deployment of Advanced Metering Infrastructure (AMI) and Artificial Intelligence (AI) platforms that optimize load forecasting and demand-side management. Furthermore, the convergence of the transportation and power sectors—driven by the rapid adoption of electric vehicles (EVs)—is creating new revenue streams for retailers through smart charging solutions and vehicle-to-grid (V2G) services.
Market dynamics are also influenced by the increasing liberalization of energy markets across Asia and parts of North America, where competition is driving innovation in pricing structures and customer engagement. The rise of Virtual Power Plants (VPPs) represents a significant trend where retailers aggregate distributed energy resources to provide grid services, effectively balancing the intermittent nature of renewable energy sources. This evolution is compelling legacy utilities to rethink their business models, moving toward subscription-based "Energy-as-a-Service" (EaaS) frameworks that prioritize efficiency and sustainability over volumetric sales.
- Largest Region: Asia Pacific (APAC) currently holds the largest market share, accounting for over 40% of global demand, driven by massive urbanization in China and India.
- Fastest Growing Region: Southeast Asia and parts of Africa are expected to exhibit the highest CAGR due to rapid industrialization and expanding grid access.
- Largest Segment by Share: The Industrial sector remains the largest consumer by volume, though the Residential segment is the fastest evolving in terms of service innovation.
- Technology Trend: AI-driven predictive analytics for energy consumption optimization is becoming a standard offering among top-tier retail providers.
- Sustainability Focus: Green tariffs and 100% renewable energy contracts are witnessing a 25% year-on-year increase in adoption among corporate and industrial (C&I) clients.
Key Takeaways Retail Electricity Market Size & Forecast
The forecast period from 2025 to 2034 suggests a period of robust investment in grid modernization and digital retail interfaces. Analysts observe that the market is entering a phase of high consolidation in mature markets like Europe, while emerging economies are seeing a surge in new market entrants and independent power producers. The integration of the Internet of Things (IoT) into household appliances is enabling more sophisticated demand-response programs, which are essential for managing the peak loads associated with renewable energy volatility. Revenue growth will likely be decoupled from total volume consumption as energy efficiency measures gain traction, forcing retailers to monetize data and provide value-added services such as home energy audits and HVAC optimization.
- Dominant Country: China continues to lead in total investment and capacity expansion, particularly in the integration of high-voltage direct current (HVDC) lines for long-distance retail distribution.
- Growth Catalyst: The implementation of the Inflation Reduction Act (IRA) in the United States is a primary driver for renewable retail investment in North America.
- Consumer Shift: There is a marked shift toward fixed-price renewable contracts as consumers seek protection against the price volatility of fossil fuels.
- Regulatory Impact: The EU Green Deal and "Fit for 55" package are mandating stricter decarbonization targets for retailers across the European continent.
- Market Stability: Long-term Power Purchase Agreements (PPAs) are becoming the preferred instrument for stabilizing retail price forecasts for large-scale industrial users.
Retail Electricity Market Drivers Analysis
The primary driver for the retail electricity market is the global shift toward electrification in sectors that were previously reliant on fossil fuels. This includes the electrification of space heating through heat pumps and the aggressive rollout of EV charging infrastructure. Additionally, the liberalization of energy markets in developing nations allows for competitive retail pricing, which attracts private investment and improves operational efficiency. The demand for reliable, 24/7 power in data centers, particularly those supporting AI and cloud computing, is also providing a significant tailwind for the high-reliability retail segment.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Electrification of Transportation (EVs) | +1.8% | Global (Strongest in Europe/China) | 2025 - 2034 |
| Grid Digitalization & Smart Meters | +1.2% | North America & APAC | 2025 - 2030 |
| Corporate Sustainability Mandates | +0.9% | Western Europe & USA | 2025 - 2034 |
| Urbanization in Emerging Markets | +1.5% | India, Brazil, Indonesia | 2026 - 2034 |
Retail Electricity Market Restraints Analysis
The market faces significant hurdles, primarily concerning aging grid infrastructure that cannot always handle the bidirectional flow of energy from distributed resources. High capital expenditure requirements for upgrading transmission and distribution networks often lead to increased retail costs, which can dampen consumer demand or lead to regulatory pushback. Furthermore, geopolitical tensions affecting natural gas supplies and critical mineral chains for battery storage continue to introduce price volatility into the retail market, making long-term forecasting difficult for providers and end-users alike.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Aging Transmission Infrastructure | -0.7% | United States & UK | 2025 - 2034 |
| Regulatory Price Caps | -0.5% | European Union | 2025 - 2028 |
| Supply Chain Volatility | -0.4% | Global | 2025 - 2030 |
Retail Electricity Market Opportunities Analysis
Opportunities abound in the integration of storage solutions with retail offerings. As battery costs continue to decline, retail providers can offer "behind-the-meter" storage services that allow consumers to arbitrage energy prices. Additionally, the development of Peer-to-Peer (P2P) energy trading platforms using blockchain technology offers a lucrative opportunity for innovative retailers to act as platform facilitators rather than just commodity sellers. The expansion of microgrids in remote areas and industrial parks also presents a high-margin niche for specialized retail providers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Virtual Power Plant (VPP) Integration | +1.4% | Germany, Australia, Japan | 2026 - 2034 |
| Energy-as-a-Service (EaaS) Models | +1.1% | North America (C&I Segment) | 2025 - 2034 |
| Green Hydrogen Electrolysis Demand | +0.6% | Middle East & Australia | 2028 - 2034 |
Retail Electricity Market Challenges Impact Analysis
Cybersecurity is the most pressing challenge for the digitalized retail market. As smart meters and IoT devices proliferate, the surface area for cyberattacks on the grid increases, potentially leading to widespread outages or data breaches. Additionally, the intermittency of renewable energy sources poses a challenge for retailers in maintaining grid stability without relying on expensive peaking plants. Retaining customer loyalty in a hyper-competitive, liberalized market where "churn" rates are high also remains a significant operational challenge for retail marketing teams.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Cybersecurity Vulnerabilities | -0.6% | Global (High in Digitalized Markets) | 2025 - 2034 |
| Grid Balancing Costs | -0.8% | High Renewable Penetration Zones | 2025 - 2034 |
| Customer Retention/Churn | -0.3% | Liberalized Markets (UK, Texas) | 2025 - 2034 |
Retail Electricity Market - Updated Report Scope
This report provides a granular analysis of the global retail electricity landscape, covering the entire value chain from generation procurement to end-user delivery. It examines the impact of regulatory shifts, technological advancements in smart grids, and the evolving consumer preference for sustainable energy. The scope includes a detailed breakdown of residential, commercial, and industrial segments across major geographic regions, providing stakeholders with actionable insights for strategic planning and investment. The report further evaluates the competitive positioning of the top 20 global players, focusing on their digital transformation strategies and renewable energy portfolios.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.25 Trillion |
| Market Forecast in 2034 | USD 2.08 Trillion |
| Growth Rate | 5.8% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Enel S.p.A., Électricité de France (EDF), E.ON SE, Engie SA, Iberdrola S.A., NextEra Energy, Inc., Duke Energy Corporation, Southern Company, National Grid plc, RWE AG, Tokyo Electric Power Company (TEPCO), Exelon Corporation, State Grid Corporation of China, Korea Electric Power Corporation (KEPCO), Vattenfall AB, Centrica plc, Origin Energy, NRG Energy, Inc., American Electric Power (AEP), Kansai Electric Power. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the retail electricity market reflects the diversity of consumption patterns and the varied requirements of different economic sectors. The industrial segment remains the primary driver of volume, requiring high-voltage, high-reliability supply often secured through complex, multi-year contracts. Conversely, the residential segment is where the most significant innovation is occurring, particularly in the realm of smart home integration and personalized energy management apps. The commercial segment is increasingly focusing on corporate power purchase agreements (CPPAs) to meet Environmental, Social, and Governance (ESG) targets, while the newly emerging transportation segment is poised for exponential growth as public and private EV fleets expand globally.
- By User Type:
- Residential: Focus on smart meters, home automation, and solar rooftop integration.
- Commercial: Offices, retail malls, and hospitals focusing on efficiency and ESG reporting.
- Industrial: High-volume manufacturing, chemical plants, and data centers requiring stable load profiles.
- Transportation: Public transit electrification and private EV charging networks.
- By Power Source:
- Renewables: Solar, Wind, and Hydro are seeing the fastest growth in the retail mix.
- Conventional: Natural gas and coal, still dominant in many regions but facing phase-out pressure.
- Nuclear: Providing a stable, carbon-free baseline for retail portfolios in specific regions like France and the US.
- By Service Model:
- Fixed-rate: Preferred by risk-averse residential and small business customers.
- Variable/Dynamic: Gaining traction among tech-savvy users with smart home devices.
- Prepaid: Crucial for market expansion in emerging economies in Africa and Southeast Asia.
Regional Highlights
- Asia Pacific: The largest market globally, led by China's massive grid investments and India's rapid industrial expansion. China alone accounts for a significant portion of global renewable retail capacity.
- North America: A mature market characterized by high levels of digitalization. The U.S. market is highly fragmented with significant variation in deregulation across states, with Texas and the Northeast being primary hubs for retail competition.
- Europe: The global leader in energy transition policy. Countries like Germany and the UK are pioneers in integrating high percentages of intermittent renewables into the retail mix and implementing sophisticated carbon pricing.
- Latin America: Brazil and Chile are emerging as key markets for renewable energy retail, driven by favorable solar and wind conditions and recent regulatory reforms aimed at attracting private capital.
- Middle East and Africa: The Middle East is pivoting toward solar integration to preserve oil for export, while Africa represents a massive opportunity for off-grid retail solutions and microgrid technologies.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Retail Electricity Market.- Enel S.p.A.
- Électricité de France (EDF)
- E.ON SE
- Engie SA
- Iberdrola S.A.
- NextEra Energy, Inc.
- Duke Energy Corporation
- Southern Company
- National Grid plc
- RWE AG
- Tokyo Electric Power Company (TEPCO)
- Exelon Corporation
- State Grid Corporation of China
- Korea Electric Power Corporation (KEPCO)
- Vattenfall AB
- Centrica plc
- Origin Energy
- NRG Energy, Inc.
- American Electric Power (AEP)
- Kansai Electric Power
Frequently Asked Questions
What is the current size of the global Retail Electricity market?
The global retail electricity market is estimated at approximately USD 1.25 Trillion in 2025 and is projected to surpass USD 2.08 Trillion by 2034, growing at a CAGR of 5.8% during the forecast period.
Which region is expected to grow the fastest in the Retail Electricity sector?
While Asia Pacific remains the largest market, Southeast Asian countries and parts of the Middle East are expected to show the fastest growth rates due to rapid urbanization and large-scale industrialization projects.
How is the rise of Electric Vehicles (EVs) affecting the retail electricity market?
EVs are a major growth driver, significantly increasing total residential and commercial electricity demand. They also enable new services like smart charging and vehicle-to-grid (V2G) solutions, allowing retailers to manage grid loads more effectively.
What are the main challenges facing retail electricity providers today?
The primary challenges include aging grid infrastructure, the high cost of integrating intermittent renewable energy, increasing cybersecurity threats to digitalized billing and metering systems, and high customer churn in liberalized markets.
What role does Artificial Intelligence play in the Retail Electricity market?
AI is used for predictive load forecasting, optimizing demand-response programs, personalized customer engagement, and identifying infrastructure failures before they occur, thereby improving both operational efficiency and customer satisfaction.
Author
S
Seema Bhateja is a Manger Energy and Power Research Industry with 7+ years of experience in the Energy and Power Industry. She specializes in energy market intelligence, power generation analysis, renewable energy assessment, demand forecasting, competitive benchmarking, grid infrastructure evaluation, regulatory landscape analysis, market sizing, and investment trend analysis across conventional and clean energy sectors. Her research integrates industry expertise with data-driven methodologies to help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, anticipate evolving market trends, and strengthen their competitive positioning in the global energy and power market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
