Motive Lead Acid Battery Market
Motive Lead Acid Battery Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711502 | Published On : November 04, 2026 |
Format : 


 | Author : Seema Bhateja
Motive Lead Acid Battery Market Size
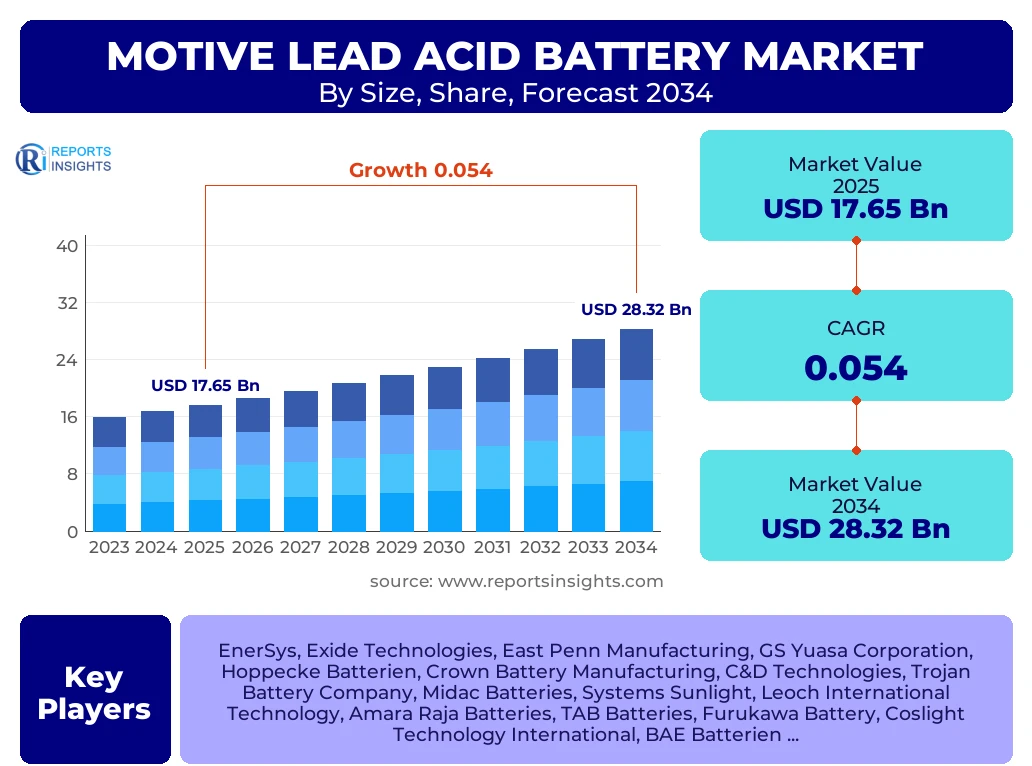
According to Reports Insights Consulting Pvt Ltd, The Motive Lead Acid Battery Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.4% between 2025 and 2034. The market is estimated at USD 18.57 Billion in 2026 and is projected to reach USD 28.32 Billion by the end of the forecast period in 2034.
The global motive lead acid battery market is undergoing a significant transformation as industrial and commercial sectors seek reliable, cost-effective energy storage solutions for material handling and transportation. Motive power batteries, specifically designed to provide deep discharge cycles over long durations, remain the backbone of the global logistics and warehousing industry. Despite the rising competition from lithium-ion alternatives, lead acid technology maintains a dominant position due to its high recyclability, established infrastructure, and superior safety profile in heavy-duty applications. The increasing demand for electric forklifts, automated guided vehicles (AGVs), and ground support equipment is driving the sustained expansion of this market across both developed and emerging economies.
The market valuation reflects a steady progression supported by the rapid expansion of e-commerce and the subsequent need for sophisticated warehousing solutions. In recent years, technical advancements in lead-carbon and thin plate pure lead (TPPL) technologies have enhanced the performance characteristics of these batteries, narrowing the gap with newer chemistries in terms of charging efficiency and cycle life. This technological resilience ensures that motive lead acid batteries remain a preferred choice for cost-conscious operators who require high-torque performance and robust reliability in demanding industrial environments. Furthermore, the global shift toward electrification in closed-campus environments, such as airports and manufacturing hubs, provides a consistent tailwind for long-term market growth.
Key Motive Lead Acid Battery Market Trends & Insights
The Motive Lead Acid Battery market is characterized by a strategic shift toward high-performance variants like VRLA and TPPL to meet the rigorous demands of 24/7 logistics operations. Users are increasingly inquiring about the total cost of ownership (TCO) comparisons between lead acid and lithium-ion, leading manufacturers to focus on maintenance-free designs and rapid-charging capabilities. The market is also seeing a surge in "Battery-as-a-Service" (BaaS) models, where industrial fleets lease power rather than purchasing hardware, optimizing capital expenditure. Competitive benchmarking reveals that regional leaders are investing heavily in circular economy initiatives, emphasizing 99% recyclability as a primary sustainability advantage over competing battery chemistries.
- Largest Region: Asia Pacific remains the dominant market shareholder due to the massive manufacturing base in China and India and the rapid expansion of logistics networks.
- Fastest Growing Region: Southeast Asia is projected to witness the highest growth rate, fueled by industrialization and the entry of global e-commerce giants.
- Largest Segment by Type: VRLA (Valve Regulated Lead Acid) batteries hold the largest share due to their maintenance-free nature and suitability for sensitive environments.
- Largest Segment by Application: Forklifts and material handling equipment represent the primary revenue generator for the motive power sector.
Key Takeaways Motive Lead Acid Battery Market Size & Forecast
The market trajectory for motive lead acid batteries is defined by a balance of traditional reliability and modern efficiency upgrades. Stakeholders are focusing on regional supply chain resilience and the integration of smart monitoring systems to track battery health in real-time. Forecasts indicate that while the market faces pressure from alternative technologies, the established recycling ecosystem for lead ensures it remains a central component of global green energy strategies. The transition from internal combustion engine (ICE) forklifts to electric versions in emerging markets provides a massive untapped reservoir for market expansion throughout the forecast period.
- Leading Country: China continues to lead in both production and consumption, supported by extensive government subsidies for industrial electrification.
- Material Innovation: The adoption of Lead-Carbon technology is extending battery life by 30%, making it highly competitive for heavy-duty motive cycles.
- Recycling Leadership: With a recovery rate exceeding 98%, lead acid batteries are the most successfully recycled consumer product globally, aiding ESG compliance.
- Warehouse Automation: The rise of AGVs and AMRs in smart factories is creating new specifications for high-density motive power units.
- Economic Resilience: The low initial purchase price of lead acid remains the decisive factor for SMEs in the logistics sector.
Motive Lead Acid Battery Market Drivers Analysis
The primary drivers of the motive lead acid battery market include the exponential growth of global e-commerce, which mandates a higher volume of material handling equipment, and the cost-efficiency of lead-based systems compared to newer energy storage technologies. Additionally, stringent environmental regulations in indoor facilities are forcing a shift from diesel-powered machinery to electric alternatives, where lead acid remains the most accessible entry point.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| E-commerce & Logistics Expansion | +1.8% | Global (North America & APAC) | 2025-2034 |
| Shift to Electric Material Handling | +1.5% | Europe & China | 2025-2030 |
| Technological Advancements (TPPL) | +1.1% | United States & Germany | 2026-2034 |
| Cost Advantage Over Li-ion | +1.0% | Latin America & India | 2025-2034 |
Motive Lead Acid Battery Market Restraints Analysis
Despite its dominance, the market faces significant headwinds from the decreasing cost of lithium-ion batteries and their superior energy density. Furthermore, the environmental concerns associated with lead mining and the intensive maintenance required for traditional flooded lead-acid batteries act as barriers to adoption in high-tech industrial settings.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Competition from Lithium-ion Batteries | -1.4% | Developed Economies | 2025-2034 |
| Environmental & Health Regulations | -0.8% | European Union | 2025-2028 |
| Maintenance Intensity | -0.5% | Global | 2025-2034 |
Motive Lead Acid Battery Market Opportunities Analysis
Significant opportunities lie in the modernization of existing industrial fleets in developing nations and the integration of IoT-enabled battery management systems. The development of advanced lead-carbon batteries for opportunity charging also presents a lucrative pathway for capturing market share in fast-paced warehouse environments.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adoption of Lead-Carbon Technology | +1.2% | Japan & South Korea | 2026-2034 |
| Expansion of Cold Chain Logistics | +0.9% | Global | 2025-2032 |
| Market Entry in SE Asia | +1.1% | Vietnam, Indonesia | 2027-2034 |
Motive Lead Acid Battery Market Challenges Impact Analysis
The industry must navigate challenges such as the volatility of raw lead prices and the logistical complexities of handling hazardous materials. Ensuring a sustainable supply chain while meeting the increased power requirements of modern high-speed automated systems remains a critical hurdle for traditional manufacturers.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Raw Material Price Volatility | -0.6% | Global | Ongoing |
| Disposal & Recycling Compliance | -0.4% | Emerging Markets | 2025-2030 |
| Slow Charging Speeds vs Lithium | -0.7% | Heavy Industry | 2025-2034 |
Motive Lead Acid Battery Market - Updated Report Scope
This report provides a granular analysis of the global motive lead acid battery landscape, covering technological segments, diverse industrial applications, and geographical performance. It includes a comprehensive assessment of the competitive environment, regulatory frameworks, and the impact of the global energy transition on traditional lead-based storage solutions.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 17.65 Billion |
| Market Forecast in 2034 | USD 28.32 Billion |
| Growth Rate | 5.4% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | EnerSys, Exide Technologies, East Penn Manufacturing, GS Yuasa Corporation, Hoppecke Batterien, Crown Battery Manufacturing, C&D Technologies, Trojan Battery Company, Midac Batteries, Systems Sunlight, Leoch International Technology, Amara Raja Batteries, TAB Batteries, Furukawa Battery, Coslight Technology International, BAE Batterien, Saft (TotalEnergies), Rolls Battery Engineering, Eternity Technologies, Narada Power |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The motive lead acid battery market is segmented primarily by product technology and end-use applications, reflecting the diverse needs of the industrial sector. VRLA batteries are gaining momentum due to their low maintenance requirements and safety features in food and pharmaceutical warehouses. Meanwhile, traditional flooded batteries remain the cost-efficient choice for heavy-duty construction and mining operations where ventilation is less of a concern. The emergence of lead-carbon batteries represents a specialized segment targeting higher cycle life and faster charging times, specifically for high-throughput logistics hubs.
- Product Type:
- VRLA (Valve Regulated Lead Acid): Dominant segment for indoor warehousing due to spill-proof design and maintenance-free operation.
- Flooded Lead Acid: Preferred for cost-sensitive applications and extreme heavy-duty industrial tasks.
- Lead-Carbon: High-growth segment offering improved resistance to partial state-of-charge (PSoC) operation.
- Application:
- Forklifts & Material Handling: The largest application area, driven by global supply chain modernization.
- Automated Guided Vehicles (AGVs): Rapidly expanding segment due to the rise of Industry 4.0 and smart factories.
- Golf Carts & Personal Transport: Significant steady demand in the hospitality and residential community sectors.
- Ground Support Equipment (GSE): Electrification of airport tugs and tractors.
- Sales Channel:
- OEM (Original Equipment Manufacturer): Direct integration into new machinery.
- Aftermarket: Large replacement market due to the finite lifespan of lead acid batteries in high-use cycles.
Regional Highlights
- Asia Pacific: Holds over 40% of the market share, driven by China's manufacturing dominance and India's burgeoning logistics sector. The region is both the largest producer and consumer of motive batteries.
- North America: A mature market focused on high-efficiency VRLA and TPPL technologies. The growth is heavily tied to the expansion of e-commerce giants like Amazon and Walmart.
- Europe: Characterized by stringent environmental standards, favoring high-quality, maintenance-free batteries and robust recycling networks. Germany and the UK lead in warehouse automation adoption.
- Latin America: Expected to show steady growth as manufacturing hubs in Mexico and Brazil modernize their material handling fleets.
- Middle East & Africa: Growth is concentrated in the logistics hubs of the UAE and Saudi Arabia, alongside mining activities in South Africa.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Motive Lead Acid Battery Market.- EnerSys
- Exide Technologies
- East Penn Manufacturing
- GS Yuasa Corporation
- Hoppecke Batterien
- Crown Battery Manufacturing
- C&D Technologies
- Trojan Battery Company
- Midac Batteries
- Systems Sunlight
- Leoch International Technology
- Amara Raja Batteries
- TAB Batteries
- Furukawa Battery
- Coslight Technology International
- BAE Batterien
- Saft (TotalEnergies)
- Rolls Battery Engineering
- Eternity Technologies
- Narada Power
Frequently Asked Questions
What is the expected growth of the Motive Lead Acid Battery market?
The global market is projected to grow at a CAGR of 5.4% from 2025 to 2034, reaching a valuation of USD 28.32 Billion by 2034, driven by the logistics and warehouse automation sector.
Why is lead acid still preferred over lithium-ion in motive power?
Lead acid remains preferred due to its lower initial cost (CAPEX), established 99% recycling rate, and safety in heavy-duty applications where weight is often needed as a counterweight for forklifts.
Which region is the fastest-growing in this market?
Southeast Asia is currently the fastest-growing region, fueled by rapid industrialization, infrastructure development, and the expansion of the regional e-commerce logistics network.
What are the main types of motive lead acid batteries?
The primary types include Flooded Lead Acid (traditional), VRLA (Valve Regulated - AGM or Gel), and the newer Lead-Carbon batteries designed for high-cycle industrial use.
How does warehouse automation affect the battery market?
Automation increases the demand for AGVs and AMRs, which require reliable motive power. This shift is driving innovation in "opportunity charging" and maintenance-free battery technologies.
Author
S
Seema Bhateja is a Manger Energy and Power Research Industry with 7+ years of experience in the Energy and Power Industry. She specializes in energy market intelligence, power generation analysis, renewable energy assessment, demand forecasting, competitive benchmarking, grid infrastructure evaluation, regulatory landscape analysis, market sizing, and investment trend analysis across conventional and clean energy sectors. Her research integrates industry expertise with data-driven methodologies to help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, anticipate evolving market trends, and strengthen their competitive positioning in the global energy and power market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
