Diesel Generator Market
Diesel Generator Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711339 | Published On : October 28, 2026 |
Format : 


 | Author : Seema Bhateja
Diesel Generator Market Size
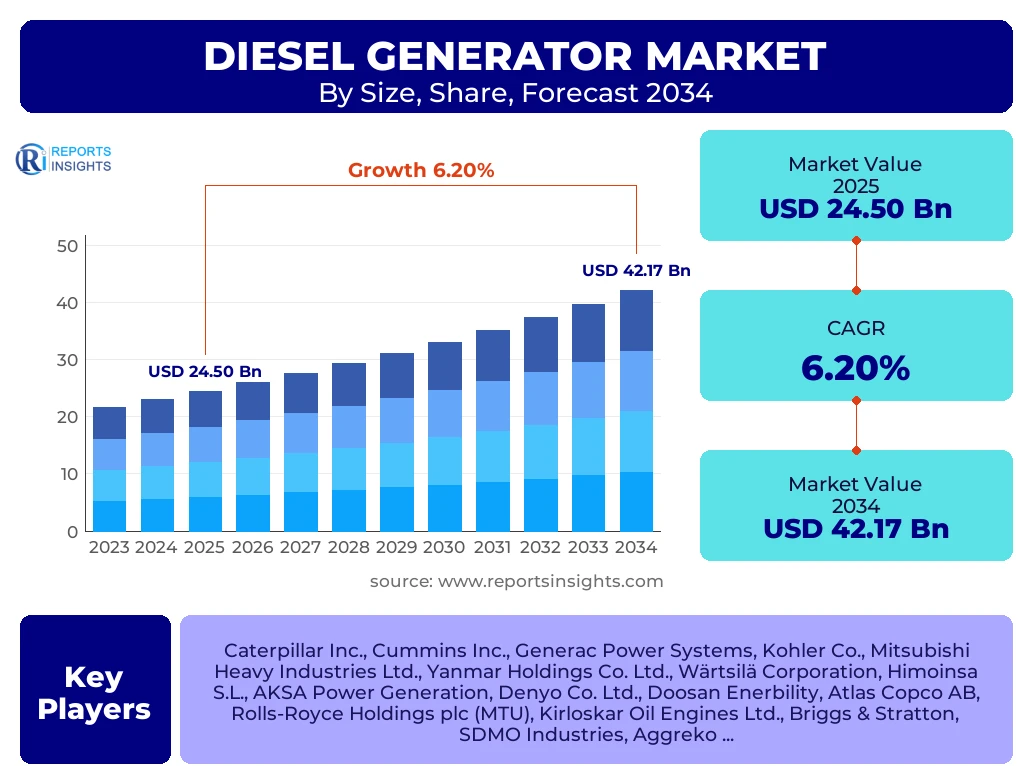
According to Reports Insights Consulting Pvt Ltd, The Diesel Generator Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2025 and 2034. The market is estimated at USD 26.02 Billion in 2026 and is projected to reach USD 42.17 Billion by the end of the forecast period in 2034.
The global energy landscape is currently navigating a complex transition where traditional power reliability remains a cornerstone for industrial and commercial operations. Diesel generators continue to serve as the primary solution for emergency standby power, peak shaving, and continuous power in remote locations. The market expansion is fundamentally underpinned by the rapid proliferation of data centers, the revitalization of global manufacturing hubs, and the critical need for resilient power infrastructure in the face of increasing grid instability and extreme weather events. While the global shift toward decarbonization presents long-term competition from battery storage and hydrogen fuel cells, the immediate technical superiority of diesel in terms of power density, response time, and existing infrastructure ensures its continued dominance in the backup power sector.
The statistical trajectory of the market reflects a robust recovery post-pandemic, followed by a sustained growth phase driven by emerging economies. In regions like Asia-Pacific and Africa, large-scale urbanization and industrialization projects are outpacing the development of centralized utility grids, making diesel generators an essential component for economic continuity. Conversely, in mature markets like North America and Europe, the growth is heavily concentrated in the high-power rating segments, specifically catering to the hyperscale data center industry and healthcare facilities where zero-latency power transition is a non-negotiable requirement. This dichotomy creates a diverse market environment where technological innovation in emission reduction and fuel efficiency serves as a primary differentiator for global manufacturers.
Key Diesel Generator Market Trends & Insights
The diesel generator market is witnessing a profound shift toward digitalization and environmental compliance. Modern units are no longer isolated mechanical assets; they are becoming integrated components of the Internet of Things (IoT) ecosystem. Predictive maintenance, enabled by real-time sensor data and cloud analytics, is significantly reducing downtime and operational costs for enterprise-level users. Furthermore, there is a visible trend toward hybrid power systems, where diesel generators are coupled with renewable energy sources and battery storage to optimize fuel consumption and reduce carbon footprints without compromising reliability. Competitive benchmarking reveals that the leading players are aggressively investing in "Tier 4 Final" and "Stage V" compliant engines to navigate the stringent environmental regulations in Western jurisdictions while maintaining performance metrics.
- Largest Region: Asia-Pacific remains the largest regional market, driven by massive infrastructure spending in China, India, and Southeast Asia.
- Fastest Growing Region: Africa and parts of the Middle East are projected to exhibit the highest CAGR due to rapid industrialization and significant gaps in grid reliability.
- Largest Segment by Share: The Industrial and Data Center segments currently hold the largest market share, particularly for high-power rating generators exceeding 750 kVA.
- Technological Shift: Increasing adoption of bi-fuel and tri-fuel systems that allow generators to operate on a mix of diesel and natural gas to lower emissions.
- Digital Integration: Rise of "Power as a Service" (PaaS) models and remote monitoring systems as key value-added services.
Key Takeaways Diesel Generator Market Size & Forecast
The forecast period from 2025 to 2034 indicates a market that is maturing in terms of technology but expanding in terms of application depth. The critical takeaway for stakeholders is the sustained demand within the mission-critical infrastructure sector. As global digitalization accelerates, the demand for high-capacity diesel generators (above 1000 kVA) is expected to grow disproportionately compared to residential segments. The market is also seeing a consolidation of supply chains as manufacturers seek to mitigate geopolitical risks and localize production in high-growth regions. Strategically, the focus is shifting from simple hardware sales to comprehensive lifecycle management and emission-compliant power solutions that align with corporate ESG (Environmental, Social, and Governance) targets.
- China and India dominance: These two nations will account for nearly 35 percent of the total global volume by 2034 due to manufacturing incentives and urban expansion.
- Data Center Surge: The exponential growth of AI and cloud computing is the single largest driver for the standby power segment in developed economies.
- Regulatory Pressure: Emission standards are forcing a transition toward cleaner diesel technologies and sophisticated exhaust after-treatment systems.
- Grid Modernization Gaps: Slow utility grid upgrades in North America and Europe are inadvertently supporting the demand for onsite diesel backup systems.
- Energy Security: Increasing geopolitical tensions and energy supply volatility are prompting industries to invest in diesel-based self-generation for energy independence.
Diesel Generator Market Drivers Analysis
The primary catalysts for the diesel generator market include the rising frequency of power outages and the critical reliance on continuous electricity for modern digital infrastructure. As utility grids age in developed nations and struggle to keep pace with demand in developing ones, the diesel generator remains the gold standard for immediate, high-torque power response. Additionally, the industrial sector's expansion into remote areas for mining and oil exploration necessitates decentralized power solutions where diesel remains the most viable and transportable fuel source.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Data Center Capacity Expansion | +2.4% | Global (USA, Ireland, Singapore) | 2025 - 2034 |
| Infrastructure & Urbanization | +1.8% | Asia-Pacific (India, Vietnam) | 2025 - 2030 |
| Industrial Automation & Manufacturing | +1.1% | Germany, China, Mexico | 2026 - 2034 |
| Aging Grid Infrastructure | +0.9% | North America | 2025 - 2034 |
Diesel Generator Market Restraints Analysis
The market faces significant headwinds from increasingly stringent environmental regulations and the global push for carbon neutrality. Governments are implementing carbon taxes and stricter emission limits that increase the total cost of ownership for diesel assets. Furthermore, the rapid advancement and falling costs of Battery Energy Storage Systems (BESS) are beginning to challenge diesel's dominance in short-duration backup applications, particularly in the residential and small commercial sectors.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Emission Standards (EPA/Stage V) | -1.5% | European Union, North America | 2025 - 2034 |
| Rise of Battery Energy Storage (BESS) | -1.2% | Global | 2027 - 2034 |
| Fuel Price Volatility | -0.7% | Global | Ongoing |
Diesel Generator Market Opportunities Analysis
Opportunities are emerging in the integration of diesel generators with renewable microgrids. By acting as the "firming" power source for solar or wind installations, diesel generators can facilitate the transition to green energy while ensuring 100 percent uptime. Additionally, the development of HVO (Hydrotreated Vegetable Oil) compatible engines provides a pathway for users to reduce their net carbon emissions by up to 90 percent without replacing their existing generator infrastructure, presenting a massive retrofit and new-sale opportunity.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| HVO & Biofuel Compatibility | +1.6% | Europe, Nordic Countries | 2025 - 2034 |
| Hybrid Microgrid Integration | +1.3% | Australia, Africa, Remote Mining | 2026 - 2034 |
| Digital Twin & AI Monitoring | +0.8% | Global (Enterprise Users) | 2025 - 2030 |
Diesel Generator Market Challenges Impact Analysis
The primary challenge lies in the public perception of diesel as a "dirty" fuel, which is driving some corporate clients to explore less reliable but more sustainable alternatives. Maintaining supply chain resilience for specialized components, such as semiconductors for engine control units (ECUs) and high-grade steel for enclosures, remains a persistent operational hurdle. Furthermore, the transition to natural gas generators in regions with established gas infrastructure poses a direct competitive threat to traditional diesel sales.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Public Perception & ESG Mandates | -1.1% | Global Corporate Sector | 2025 - 2034 |
| Natural Gas Generator Competition | -0.9% | USA, Russia, Middle East | 2025 - 2034 |
| Supply Chain Constraints | -0.5% | Global Manufacturers | Short to Medium Term |
Diesel Generator Market - Updated Report Scope
This report provides a granular analysis of the global diesel generator market, encompassing power ratings from small portable units to multi-megawatt industrial power plants. The scope includes a detailed evaluation of technology types, including standby, prime, and continuous power applications, across residential, commercial, and industrial end-users. The analysis covers the transition from mechanical to electronic governors and the integration of advanced exhaust filtration systems. Geographically, the report offers insights into 25+ key national markets, highlighting regulatory shifts and infrastructure development projects that dictate demand patterns.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 24.50 Billion |
| Market Forecast in 2034 | USD 42.17 Billion |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 265 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Caterpillar Inc., Cummins Inc., Generac Power Systems, Kohler Co., Mitsubishi Heavy Industries Ltd., Yanmar Holdings Co. Ltd., Wärtsilä Corporation, Himoinsa S.L., AKSA Power Generation, Denyo Co. Ltd., Doosan Enerbility, Atlas Copco AB, Rolls-Royce Holdings plc (MTU), Kirloskar Oil Engines Ltd., Briggs & Stratton, SDMO Industries, Aggreko, Weichai Power Co. Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The diesel generator market is characterized by diverse requirements ranging from residential backup to heavy-duty industrial baseload power. Segmenting by power rating reveals that the Very High (>750 kVA) segment is witnessing the most aggressive growth, primarily fueled by the mission-critical needs of hyperscale data centers and large-scale manufacturing plants. Application-wise, Standby Power continues to dominate the market share as businesses prioritize business continuity. Meanwhile, the Prime/Continuous Power segment is seeing steady demand in emerging economies where the utility grid is either absent or chronically unreliable. The industrial end-user segment remains the largest by revenue, but the commercial segment, particularly healthcare and telecommunications, is rapidly gaining ground due to digital transformation initiatives.
- By Power Rating:
- Low Power (<75 kVA): Primarily for residential and small retail use.
- Medium Power (75-375 kVA): Used in small to medium enterprises (SMEs) and construction sites.
- High Power (375-750 kVA): Ideal for medium industrial facilities and large commercial buildings.
- Very High Power (>750 kVA): Critical for data centers, mining operations, and utility-scale peak shaving.
- By Application:
- Standby Power: The largest segment, used during utility outages.
- Prime/Continuous Power: Used as the primary source of power in remote or off-grid locations.
- Peak Shaving: Used by industrial consumers to reduce utility costs during peak demand periods.
- By End-User:
- Industrial: Covers manufacturing, oil and gas, mining, and chemical processing.
- Commercial: Includes data centers, hospitals, hotels, shopping malls, and telecommunications towers.
- Residential: Standby backup for homes and residential complexes.
Regional Highlights
- North America: The market is characterized by high demand for EPA-compliant, Tier 4 Final generators. The primary growth engine is the expansion of the data center corridor in Northern Virginia and the increasing vulnerability of the aging US power grid to storms and wildfires.
- Europe: Regulatory focus on Stage V emissions and the transition to renewable energy are the key drivers. The region is a leader in adopting HVO-compatible generators and hybrid systems to meet stringent ESG targets.
- Asia-Pacific: This is both the largest and one of the fastest-growing regions. China and India are the focal points, with massive investments in manufacturing, smart cities, and infrastructure. The presence of numerous domestic manufacturers also makes it a highly competitive price-sensitive market.
- Middle East & Africa: In the Middle East, the focus is on infrastructure diversification (e.g., Saudi Vision 2030), while in Africa, the lack of reliable grid electricity makes diesel generators a vital necessity for both commercial and residential sectors.
- Latin America: Growth is concentrated in the mining sectors of Chile and Peru, along with the growing industrial base in Brazil and Mexico.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Diesel Generator Market.- Caterpillar Inc.
- Cummins Inc.
- Generac Power Systems
- Kohler Co.
- Mitsubishi Heavy Industries Ltd.
- Yanmar Holdings Co. Ltd.
- Wärtsilä Corporation
- Himoinsa S.L.
- AKSA Power Generation
- Denyo Co. Ltd.
- Doosan Enerbility
- Atlas Copco AB
- Rolls-Royce Holdings plc (MTU)
- Kirloskar Oil Engines Ltd.
- Briggs & Stratton
- SDMO Industries
- Aggreko
- Weichai Power Co. Ltd.
- Pramac
- FG Wilson
Frequently Asked Questions
What is the projected growth rate of the diesel generator market through 2034?
The diesel generator market is expected to grow at a CAGR of 6.2% from 2025 to 2034, reaching a valuation of approximately USD 42.17 Billion by the end of the period, driven by data center demand and industrialization.
How are environmental regulations affecting the diesel generator market?
Regulations such as EPA Tier 4 Final in the US and Stage V in Europe are forcing manufacturers to innovate with advanced after-treatment systems and biofuels, increasing initial costs but improving the long-term sustainability and compliance of diesel assets.
Which industry segment is the largest consumer of diesel generators?
The Industrial segment, including manufacturing and mining, remains the largest consumer. however, the Commercial segment, specifically Data Centers, is the fastest-growing end-user due to the global surge in digital infrastructure.
Can diesel generators be integrated with renewable energy sources?
Yes, there is a growing trend toward hybrid microgrids where diesel generators act as a reliable backup or "firming" source for intermittent renewable energy like solar and wind, ensuring continuous power supply in off-grid or weak-grid areas.
What is HVO, and why is it important for this market?
HVO (Hydrotreated Vegetable Oil) is a renewable paraffinic diesel fuel. Its importance lies in its ability to be used as a drop-in replacement for traditional diesel, allowing users to reduce CO2 emissions by up to 90% without significant hardware modifications.
Author
S
Seema Bhateja is a Manger Energy and Power Research Industry with 7+ years of experience in the Energy and Power Industry. She specializes in energy market intelligence, power generation analysis, renewable energy assessment, demand forecasting, competitive benchmarking, grid infrastructure evaluation, regulatory landscape analysis, market sizing, and investment trend analysis across conventional and clean energy sectors. Her research integrates industry expertise with data-driven methodologies to help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, anticipate evolving market trends, and strengthen their competitive positioning in the global energy and power market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
