Railway Wiring Harness Market
Railway Wiring Harness Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711544 | Published On : November 05, 2026 |
Format : 


 | Author : Ashraf Shehata
Railway Wiring Harness Market Size
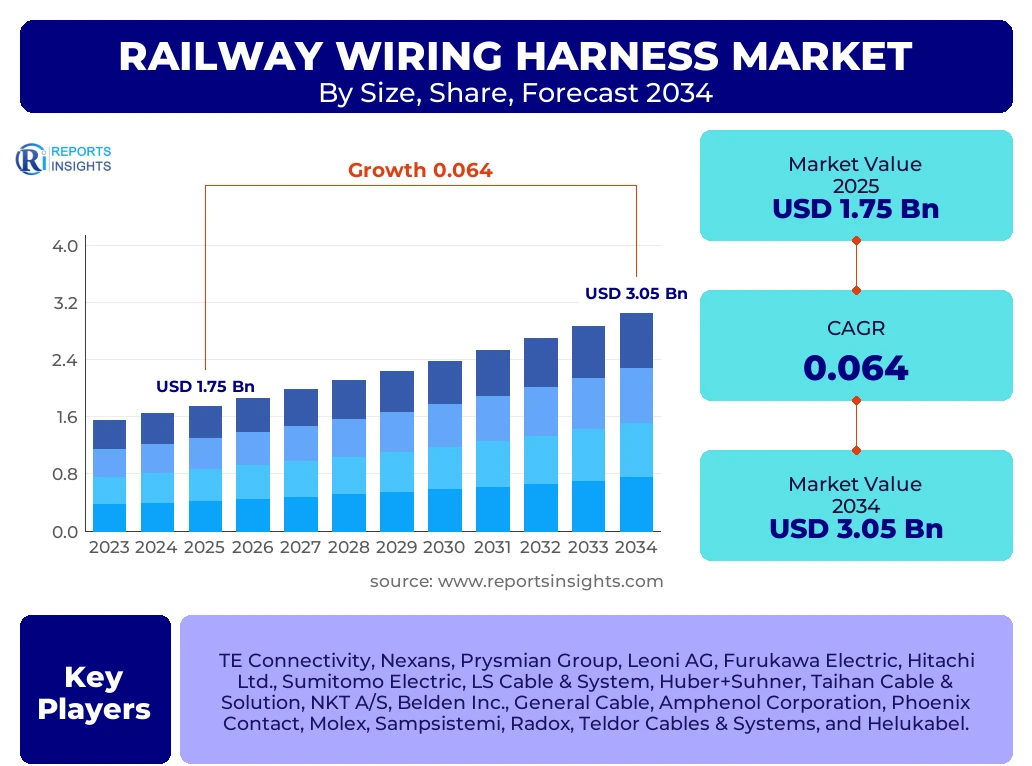
According to Reports Insights Consulting Pvt Ltd, The Railway Wiring Harness Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.4% between 2025 and 2034. The market is estimated at USD 1.86 Billion in 2026 and is projected to reach USD 3.05 Billion by the end of the forecast period in 2034.
Key Railway Wiring Harness Market Trends & Insights
The Railway Wiring Harness Market is undergoing a significant transformation driven by the global transition toward sustainable mobility and the integration of advanced digital technologies within rail infrastructure. Stakeholders are increasingly focusing on regional insights, particularly the aggressive expansion of high-speed rail networks in the Asia-Pacific region and the rigorous refurbishment of aging rolling stock in Europe. Technical benchmarking reveals a shift from traditional heavy-gauge copper wiring to lightweight, high-performance alloys and fiber-optic integration to accommodate the data-intensive requirements of modern signaling and passenger infotainment systems. Competitive benchmarking highlights that leading manufacturers are prioritizing modular harness designs to reduce installation time and enhance maintenance efficiency. Furthermore, the adoption of silicon-free and halogen-free materials is becoming a standard to comply with stringent fire, smoke, and toxicity (FST) regulations globally.
- Asia-Pacific is the largest and fastest-growing region, driven by massive infrastructure investments in China and India.
- The High-Speed Rail segment is the fastest-growing train type category due to cross-border connectivity projects.
- The Propulsion System application holds the largest market share owing to the complexity and volume of wiring required for power transmission.
- Copper remains the largest material segment, though Aluminum is gaining traction for weight-reduction initiatives.
Key Takeaways Railway Wiring Harness Market Size & Forecast
The global market for railway wiring harnesses is characterized by steady long-term growth, supported by governmental mandates for rail electrification and the decarbonization of the transport sector. Market participants are centering their strategies on the development of ruggedized solutions capable of withstanding extreme vibrations, temperature fluctuations, and electromagnetic interference (EMI). Data forecasts indicate a surge in demand for low-voltage wiring harnesses as trains become increasingly autonomous and software-defined. Strategic partnerships between rolling stock manufacturers and specialized harness providers are becoming the norm to streamline supply chains and ensure adherence to regional safety certifications.
- China and India represent the primary engines of volume growth, accounting for over 35% of the projected market expansion.
- The Metro and Monorail segment is witnessing high demand due to rapid urbanization in emerging economies.
- Lightweighting is a critical technological pivot, with manufacturers investing in specialized insulation materials to reduce the overall weight of the rolling stock.
- Aftermarket and maintenance services are emerging as significant revenue streams as older fleets undergo comprehensive electrical overhauls.
Railway Wiring Harness Market Drivers Analysis
The primary catalysts for the Railway Wiring Harness market involve the global push for rail electrification and the rapid modernization of signaling systems. As nations strive to meet net-zero carbon targets, the replacement of diesel locomotives with electric and hydrogen-powered units necessitates extensive and complex wiring architectures. Additionally, the implementation of the European Rail Traffic Management System (ERTMS) and Communications-Based Train Control (CBTC) requires sophisticated harness systems to ensure seamless data transmission and operational safety.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Global Shift Toward Rail Electrification | +2.1% | Global (Strongest in Europe and India) | 2025 - 2034 |
| Expansion of High-Speed Rail Networks | +1.8% | China, Japan, and Southeast Asia | 2026 - 2032 |
| Digitalization of Signaling and Control | +1.5% | North America and Europe | 2025 - 2030 |
Railway Wiring Harness Market Restraints Analysis
Despite robust growth prospects, the market faces significant headwinds from the high initial capital expenditure required for rail infrastructure projects. The long gestation periods of railway contracts can lead to inventory holding costs and financial strain for small-scale harness manufacturers. Furthermore, fluctuations in raw material prices, particularly copper and high-grade polymers, create volatility in profit margins, forcing companies to adopt complex hedging strategies.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Capital Intensity of Rail Projects | -1.2% | Latin America and Africa | 2025 - 2034 |
| Raw Material Price Volatility (Copper) | -0.8% | Global | Short to Medium Term |
Railway Wiring Harness Market Opportunities Analysis
The integration of the Internet of Things (IoT) and Big Data in rail operations presents a significant opportunity for the wiring harness sector. Smart harnesses equipped with sensors can monitor their own health, enabling predictive maintenance and reducing downtime. Additionally, the emergence of hydrogen-powered trains and the potential for Maglev technology offer untapped markets for specialized, high-performance wiring solutions tailored to unique thermal and electrical requirements.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Predictive Maintenance and IoT Integration | +1.4% | Germany, USA, and South Korea | 2027 - 2034 |
| Hydrogen and Alternative Fuel Trains | +1.1% | European Union | 2028 - 2034 |
Railway Wiring Harness Market Challenges Impact Analysis
Navigating the complex landscape of regional safety certifications and environmental regulations remains a primary challenge for global manufacturers. Each jurisdiction often has unique requirements for fire resistance, smoke density, and toxicity, necessitating localized product development. Moreover, the shortage of skilled labor proficient in high-precision electrical assembly for rail applications could impede production capacities in certain regions.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Complex Regulatory and Safety Standards | -0.9% | European Union and North America | Ongoing |
| Skilled Labor Shortages in Assembly | -0.5% | United Kingdom and USA | 2025 - 2030 |
Railway Wiring Harness Market - Updated Report Scope
This comprehensive market analysis encompasses the entire value chain of the Railway Wiring Harness industry, from raw material suppliers to original equipment manufacturers (OEMs) and aftermarket service providers. The scope includes a detailed evaluation of various harness components across multiple train types, ranging from high-speed locomotives to urban light rail systems. The report provides granular data on material preferences, application-specific requirements, and regional adoption rates, ensuring a holistic view of the market's trajectory over the next decade.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.75 Billion |
| Market Forecast in 2034 | USD 3.05 Billion |
| Growth Rate | 6.4% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | TE Connectivity, Nexans, Prysmian Group, Leoni AG, Furukawa Electric, Hitachi Ltd., Sumitomo Electric, LS Cable & System, Huber+Suhner, Taihan Cable & Solution, NKT A/S, Belden Inc., General Cable, Amphenol Corporation, Phoenix Contact, Molex, Sampsistemi, Radox, Teldor Cables & Systems, and Helukabel. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Railway Wiring Harness market is segmented based on component, material, train type, and application to provide a clear understanding of the various factors influencing demand. Each segment is analyzed for its historical performance, current market standing, and future growth potential. The shift toward electrification is significantly impacting the Traction and Propulsion segments, while the trend of smart rail is boosting the Signaling and Infotainment categories.
- By Component:
- Wire: The largest component segment due to the extensive length required in each car.
- Connectors: Critical for modularity and ease of maintenance.
- Terminals: Ensuring secure electrical contacts in high-vibration environments.
- Sheaths/Conduits: Vital for environmental protection and mechanical durability.
- By Material:
- Copper: The industry standard for conductivity and reliability.
- Aluminum: Gaining share in high-speed rail to reduce overall weight.
- By Train Type:
- High-Speed Rail: Leading segment in terms of value due to technical complexity.
- Metro and Monorail: Driven by urban infrastructure expansion in Asia and Latin America.
- Freight Trains: Steady demand focused on ruggedization and long-distance durability.
- By Application:
- Propulsion System: Demands high-voltage harnesses with superior thermal resistance.
- Signaling and Control: Growing demand for high-integrity, data-capable wiring.
- HVAC and Lighting: Standard applications with a focus on energy efficiency.
Regional Highlights
The regional analysis provides a comprehensive overview of the market dynamics across different geographies, identifying key growth drivers and market leaders. Regional differences in infrastructure development, regulatory frameworks, and technological adoption play a crucial role in shaping the market landscape.
- Asia-Pacific: The dominant region globally, Asia-Pacific accounts for the largest market share. This is fueled by China’s unprecedented expansion of its high-speed rail network and India’s modernization programs under the National Rail Plan. The presence of major rolling stock manufacturers like CRRC further strengthens the ecosystem.
- Europe: Europe is a leader in technological innovation and regulatory standards. The region is characterized by a strong focus on high-speed rail and the decarbonization of its existing networks. Countries like Germany, France, and the UK are investing heavily in hydrogen-powered trains and digital signaling, driving demand for advanced wiring solutions.
- North America: The market in North America is driven primarily by the refurbishment of aging urban rail systems and the expansion of freight rail networks. Recent legislative support for infrastructure development in the United States is expected to catalyze growth in the passenger rail segment.
- Middle East and Africa: Growth in this region is centered around ambitious cross-border rail projects in the GCC countries. Urban rail projects in cities like Riyadh and Dubai provide significant opportunities for specialized harness providers.
- Latin America: Market expansion is led by urban transit developments in Brazil, Chile, and Mexico, aimed at reducing metropolitan traffic congestion and improving public transport efficiency.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Railway Wiring Harness Market. These organizations are at the forefront of innovation, often engaging in strategic mergers, acquisitions, and technological collaborations to maintain their market dominance.
- TE Connectivity
- Nexans
- Prysmian Group
- Leoni AG
- Furukawa Electric
- Hitachi Ltd.
- Sumitomo Electric
- LS Cable & System
- Huber+Suhner
- Taihan Cable & Solution
- NKT A/S
- Belden Inc.
- General Cable
- Amphenol Corporation
- Phoenix Contact
- Molex
- Sampsistemi
- Radox
- Teldor Cables & Systems
- Helukabel
Frequently Asked Questions
What is the projected growth rate of the Railway Wiring Harness Market?
The Railway Wiring Harness Market is expected to grow at a CAGR of 6.4% from 2026 to 2034, driven by rail electrification and digital modernization.
Which region currently leads the global market share?
The Asia-Pacific region currently holds the largest share of the market, primarily due to massive investments in rail infrastructure in China and India.
What are the primary materials used in railway wiring harnesses?
Copper remains the most common material due to its conductivity, but there is an increasing shift toward Aluminum for its lightweight properties in high-speed rail applications.
What is driving the demand for modular wiring harness designs?
Modular designs allow for faster installation, easier maintenance, and the ability to upgrade specific train systems without replacing the entire wiring architecture.
How are safety regulations impacting the choice of wiring materials?
Strict fire, smoke, and toxicity (FST) regulations are mandating the use of halogen-free and flame-retardant materials to ensure passenger safety in enclosed environments.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
