Pipe Fabrication Market
Pipe Fabrication Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711533 | Published On : November 05, 2026 |
Format : 


 | Author : Jonathan Sikka
Pipe Fabrication Market Size
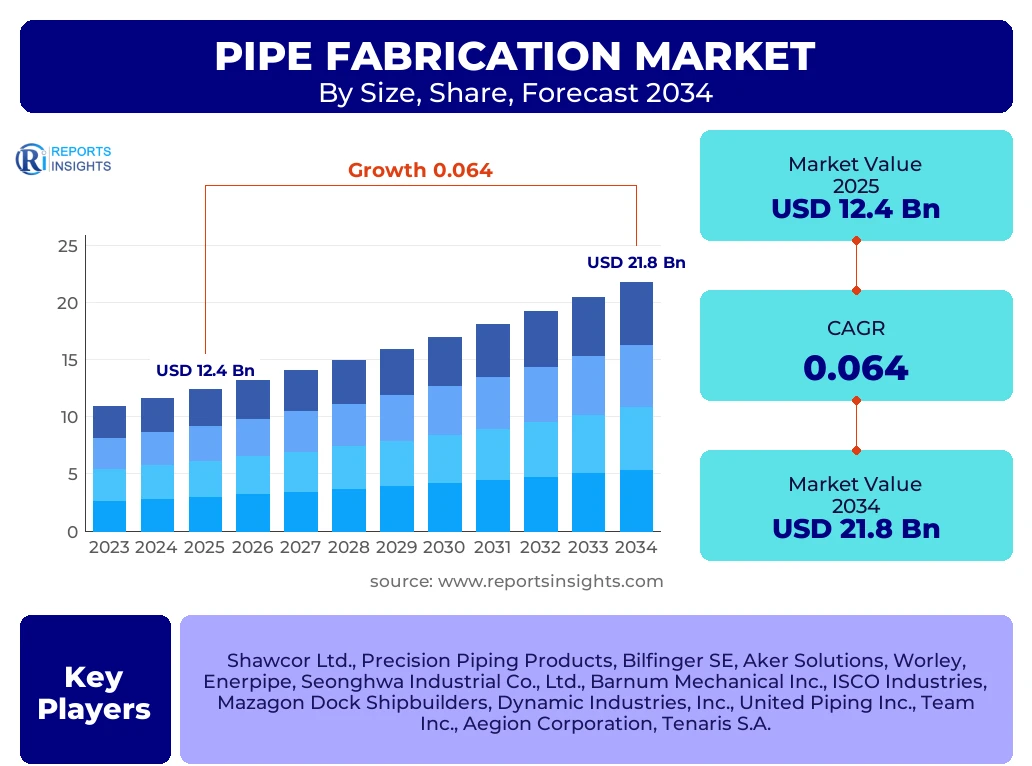
According to Reports Insights Consulting Pvt Ltd, The Pipe Fabrication Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.4% between 2025 and 2034. The market is estimated at USD 13.2 Billion in 2026 and is projected to reach USD 21.8 Billion by the end of the forecast period in 2034.
Key Pipe Fabrication Market Trends & Insights
The global pipe fabrication landscape is undergoing a fundamental transformation driven by the integration of Industry 4.0 technologies and the increasing demand for high-precision modular construction. Recent market analysis suggests that industrial operators are shifting away from on-site fabrication toward shop-controlled environments to ensure better quality control and adherence to strict safety standards. Regional insights indicate that the Asia-Pacific region remains the primary engine of growth, supported by massive infrastructure investments in energy and water treatment. Furthermore, the adoption of robotic welding and automated pipe spool fabrication is significantly reducing lead times and improving weld consistency. Competitive benchmarking shows that leading firms are increasingly investing in 3D laser scanning and Building Information Modeling (BIM) to facilitate seamless integration of fabricated components into complex industrial architectures.
- Largest Region: Asia-Pacific, holding a market share of over 38% due to rapid industrialization in China, India, and Southeast Asia.
- Fastest Growing Region: Middle East and Africa (MEA), driven by extensive downstream oil and gas projects and hydrogen infrastructure development.
- Leading Material Segment: Metallic pipes, specifically stainless steel and carbon steel, continue to dominate due to their high pressure and temperature resistance.
- Dominant Service Segment: Welding and Assembly services represent the largest revenue share, accounting for nearly 45% of total fabrication costs.
- Emerging Trend: Growth in "Smart Piping" systems equipped with embedded sensors for real-time monitoring of fluid dynamics and structural integrity.
Key Takeaways Pipe Fabrication Market Size & Forecast
Analysis of market trajectory and stakeholder inquiries reveals a high concentration of growth within the energy, petrochemical, and pharmaceutical sectors. Stakeholders are increasingly concerned with the sustainability of fabrication processes, leading to a rise in the use of recyclable materials and energy-efficient welding techniques. The forecast period highlights a significant shift toward specialized fabrication for the renewable energy sector, particularly in the construction of offshore wind farm substructures and hydrogen transport networks. Market stability is largely influenced by raw material price volatility, yet the increasing complexity of industrial projects ensures a steady demand for high-end, customized fabrication services that exceed standard off-the-shelf solutions.
- Strategic Lead: China is the single largest country market, supported by its vast manufacturing base and domestic energy demand.
- Sectoral Shift: The pharmaceutical and biotechnology sectors are emerging as high-growth end-users, requiring high-purity fabrication and electropolishing services.
- Standardization Influence: Adherence to ASME (American Society of Mechanical Engineers) and ISO standards remains the primary differentiator for market entry in developed economies.
- Cost Dynamics: Labor costs in Western nations are driving the adoption of high-level automation, whereas emerging economies rely on a blend of skilled labor and semi-automated systems.
- Supply Chain Resilience: Nearshoring of fabrication facilities to North America and Europe is increasing as companies seek to mitigate geopolitical risks associated with long-distance logistics.
Pipe Fabrication Market Drivers Analysis
The expansion of the pipe fabrication market is primarily fueled by the global transition toward cleaner energy and the modernization of aging municipal infrastructure. As nations strive to meet net-zero targets, the demand for sophisticated piping systems to transport natural gas and hydrogen has surged. Additionally, the rapid urbanization in emerging economies necessitates extensive water distribution and wastewater treatment facilities, both of which are intensive users of fabricated piping solutions. The integration of advanced metallurgy and corrosion-resistant alloys further drives market value by offering longer-lasting solutions for harsh industrial environments.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Global Energy Transition & Hydrogen Infrastructure | +1.8% | European Union, Germany, Japan | 2025-2034 |
| Urbanization & Water Management Projects | +1.5% | India, Brazil, Southeast Asia | 2025-2030 |
| Advancements in Automated Welding Robotics | +1.2% | United States, South Korea | 2026-2034 |
| Refinery Expansion & Petrochemical Demand | +0.9% | Saudi Arabia, UAE, China | 2025-2029 |
Pipe Fabrication Market Restraints Analysis
Despite robust demand, the market faces significant headwinds from the volatility of raw material prices, particularly steel and specialized alloys. Global trade tensions and fluctuating energy costs directly impact the overhead of fabrication shops. Furthermore, a persistent shortage of certified welders and specialized technical labor in developed markets poses a challenge to scaling operations and maintaining high production volumes. Regulatory pressures regarding carbon emissions from heavy industrial fabrication also necessitate costly transitions to greener manufacturing methods.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Volatility in Raw Material Pricing (Steel/Alloys) | -1.1% | Global | Ongoing |
| Acute Shortage of Certified Skilled Labor | -0.8% | North America, Western Europe | 2025-2034 |
| Stringent Environmental & Emission Regulations | -0.5% | European Union, California (US) | 2027-2034 |
Pipe Fabrication Market Opportunities Analysis
The rise of modular construction presents a significant opportunity for pipe fabricators to move up the value chain by providing pre-assembled pipe racks and skid-mounted systems. These solutions reduce on-site labor requirements and project timelines, making them highly attractive to EPC (Engineering, Procurement, and Construction) firms. Additionally, the development of specialized piping for Carbon Capture and Storage (CCS) facilities offers a niche but rapidly expanding market segment as industrial emitters seek to comply with environmental mandates.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into Modular & Skid-Mounted Units | +2.1% | North America, Middle East | 2026-2034 |
| Carbon Capture & Storage (CCS) Infrastructure | +1.4% | Norway, UK, United States | 2028-2034 |
| High-Purity Piping for Semiconductor Fabs | +0.7% | Taiwan, Arizona (US), Germany | 2025-2030 |
Pipe Fabrication Market Challenges Impact Analysis
Technical challenges in pipe fabrication include the increasing demand for exotic materials that require specialized welding procedures and post-weld heat treatments. Maintaining dimensional accuracy in complex, large-scale spools remains a logistical challenge, especially when transporting components to remote project sites. Geopolitical instability and the disruption of critical shipping lanes also pose significant risks to the timely delivery of fabricated units, potentially leading to project delays and cost overruns.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Logistical Constraints for Large-Scale Spools | -0.6% | Australia, Northern Canada | 2025-2034 |
| Complexity in Welding Exotic Metal Alloys | -0.4% | Global (High-Tech Sectors) | Ongoing |
| Disruption of Global Supply Chains | -0.9% | Global | 2025-2027 |
Pipe Fabrication Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the pipe fabrication lifecycle, including material procurement, cutting, bending, welding, and non-destructive testing (NDT). It covers various pipe materials ranging from standard carbon steel to high-nickel alloys and thermoplastic composites. The analysis provides deep insights into end-user verticals such as oil and gas, power generation, chemical processing, and municipal infrastructure. This report serves as a strategic guide for stakeholders to understand regional demand shifts, technological disruptions, and the competitive landscape through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 12.4 Billion |
| Market Forecast in 2034 | USD 21.8 Billion |
| Growth Rate | 6.4% CAGR |
| Number of Pages | 265 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Shawcor Ltd., Precision Piping Products, Bilfinger SE, Aker Solutions, Worley, Enerpipe, Seonghwa Industrial Co., Ltd., Barnum Mechanical Inc., ISCO Industries, Mazagon Dock Shipbuilders, Dynamic Industries, Inc., United Piping Inc., Team Inc., Aegion Corporation, Tenaris S.A. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The pipe fabrication market is segmented primarily by material type and service offering, with metallic pipes retaining the majority of the market share due to their structural integrity in high-pressure applications. The shift toward stainless steel is particularly notable in the pharmaceutical and food sectors, where hygiene and corrosion resistance are paramount. Service-wise, welding remains the most critical and cost-intensive component of fabrication, with increasing investments being made in high-efficiency TIG and MIG welding technologies. End-user analysis reveals that the energy sector (oil, gas, and power) accounts for nearly half of the total market demand, though the growth rates in water treatment and semiconductor manufacturing are outpacing traditional heavy industries.
- By Material:
- Carbon Steel (Largest Volume)
- Stainless Steel (High Corrosion Resistance)
- Alloy Steel (High Pressure/Temperature)
- Non-Ferrous Metals (Aluminum/Copper)
- Plastic and Composites (Rising in Water/Chemical)
- By Service:
- Welding (Core Revenue Driver)
- Cutting and Beveling (Precision Focus)
- Bending (Induction & Cold Bending)
- Surface Treatment and Coating (Galvanizing/Epoxy)
- Testing and Inspection (NDT/Hydro-testing)
- By End-User Industry:
- Oil and Gas (Upstream, Midstream, Downstream)
- Power Generation (Nuclear, Thermal, Renewables)
- Chemical and Petrochemical
- Water and Wastewater Treatment
- Food and Beverage / Pharmaceutical
- Semiconductor and Electronics
Regional Highlights
- Asia-Pacific: The largest market globally, APAC is fueled by massive infrastructure projects in China and India. China alone accounts for a significant portion of global steel pipe consumption and fabrication output.
- North America: A mature market focused on the replacement of aging infrastructure and the expansion of the shale gas industry. High adoption of advanced fabrication technologies like BIM and robotics.
- Europe: Leading the transition toward green hydrogen piping and sustainable fabrication practices. Germany and Norway are key hubs for specialized offshore and subsea fabrication.
- Middle East: The fastest-growing region, with heavy investment in downstream petrochemical complexes and the diversification of energy portfolios including solar-thermal piping systems.
- Latin America: Growth is centered in Brazil and Guyana, primarily driven by offshore oil and gas exploration and municipal water infrastructure development.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Pipe Fabrication Market.- Shawcor Ltd.
- Bilfinger SE
- Aker Solutions
- Worley
- Precision Piping Products
- Seonghwa Industrial Co., Ltd.
- ISCO Industries
- Enerpipe
- Barnum Mechanical Inc.
- United Piping Inc.
- Team Inc.
- Aegion Corporation
- Tenaris S.A.
- Dynamic Industries, Inc.
- Mazagon Dock Shipbuilders
- Wachs Services
- Piping Enterprise Company
- Cimtas Pipe
- Fabricom (ENGIE)
- McDermott International
Frequently Asked Questions
What is the current market size of the global Pipe Fabrication Market?
The global Pipe Fabrication Market is estimated to be valued at approximately USD 12.4 Billion in 2025 and is projected to grow to USD 21.8 Billion by 2034, following a CAGR of 6.4%.
Which industry is the largest consumer of pipe fabrication services?
The Oil and Gas industry remains the largest consumer, encompassing upstream extraction, midstream transport, and downstream refining, followed closely by the power generation and chemical processing sectors.
How is automation impacting the pipe fabrication industry?
Automation, particularly robotic welding and CNC pipe cutting, is significantly increasing production speed, reducing human error, and helping shops overcome the global shortage of skilled manual welders.
What are the key materials used in industrial pipe fabrication?
Carbon steel is the most widely used due to its cost-effectiveness, while stainless steel and various alloys (like Inconel or Duplex) are used for high-corrosion or extreme temperature environments.
Which region offers the most significant growth opportunities for fabricators?
The Asia-Pacific region offers the highest volume growth, while the Middle East is the fastest-growing due to massive new industrial projects and the emerging hydrogen economy.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
