Ophthalmic Device Market
Ophthalmic Device Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_705955 | Published On : October 04, 2026 |
Format : 


 | Author : Erika Grotto
Ophthalmic Device Market Size
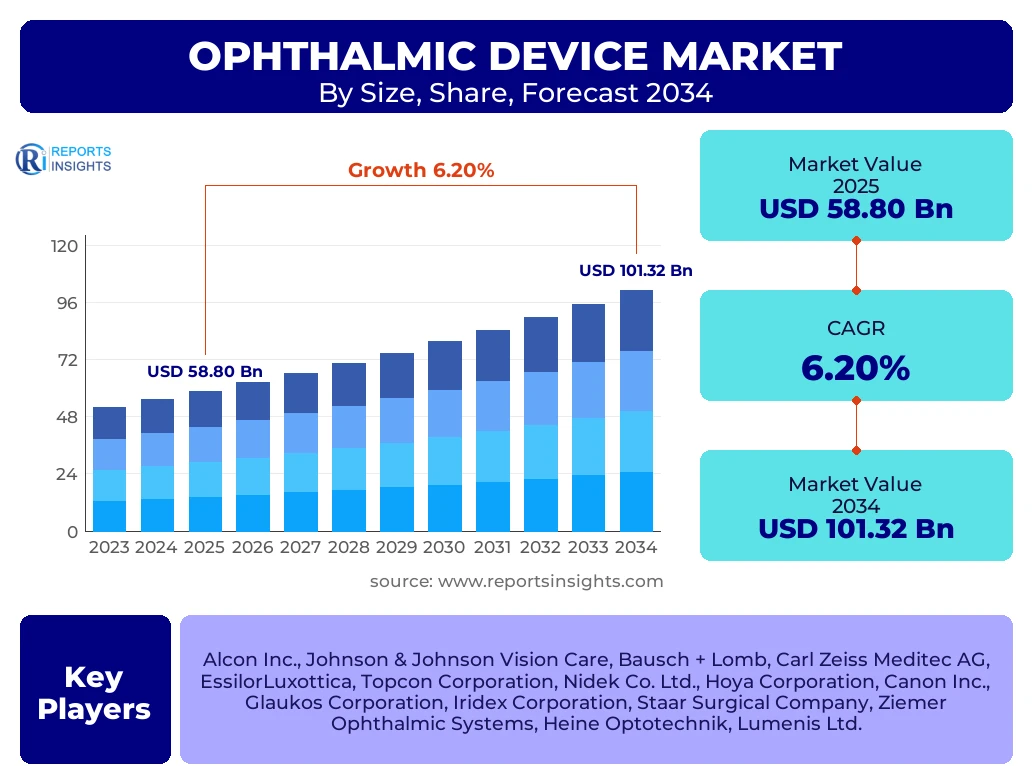
According to Reports Insights Consulting Pvt Ltd, The Ophthalmic Device Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2025 and 2034. The market is estimated at USD 62.45 Billion in 2026 and is projected to reach USD 101.32 Billion by the end of the forecast period in 2034.
Key Ophthalmic Device Market Trends & Insights
The global Ophthalmic Device market is undergoing a significant transformation driven by the convergence of digital health technologies and the escalating global burden of ocular diseases. As the world population ages, the prevalence of age-related macular degeneration (AMD), cataracts, and glaucoma is rising sharply, necessitating more precise diagnostic tools and advanced surgical interventions. Furthermore, the modern lifestyle, characterized by increased screen time, has led to a surge in refractive errors and dry eye syndrome among younger demographics, expanding the target patient base beyond traditional geriatric care. Investors and stakeholders are closely monitoring the integration of artificial intelligence (AI) and machine learning in diagnostic imaging, which is enhancing early detection and personalized treatment planning.
Competitive benchmarking reveals a shift toward minimally invasive surgical techniques and the miniaturization of therapeutic devices. Companies are increasingly focusing on the development of smart contact lenses and digital health platforms that allow for remote monitoring of intraocular pressure, bridging the gap between clinical visits and continuous patient care. Additionally, the shift from hospital-based surgeries to ambulatory surgical centers (ASCs) is reshaping the procurement landscape, with a growing demand for portable and cost-effective diagnostic equipment. This trend is particularly evident in emerging economies where healthcare infrastructure is expanding rapidly to meet the needs of an underserved middle class with rising disposable income.
- Largest Region: North America remains the largest regional market, accounting for a significant share of global revenue due to its advanced healthcare infrastructure and high adoption of premium technology.
- Fastest Growing Region: Asia-Pacific is projected to be the fastest-growing region, fueled by rising healthcare expenditure in China and India and a vast patient pool with unmet medical needs.
- Largest Segment by Share: The vision care segment, comprising spectacles and contact lenses, currently holds the largest market share owing to the high prevalence of myopia and hyperopia globally.
- Technological Convergence: The integration of optical coherence tomography (OCT) with AI-driven analytics is becoming a standard in clinical practice for high-precision retinal imaging.
- Market Expansion: Increased awareness programs and government initiatives for the prevention of avoidable blindness are significantly boosting the demand for diagnostic screening devices.
Key Takeaways Ophthalmic Device Market Size & Forecast
The market trajectory for Ophthalmic Device is heavily influenced by the dual factors of demographic shifts and technological disruption. The forecast period 2025–2034 is expected to witness a steady transition from traditional diagnostic methods to high-definition, non-invasive imaging. As healthcare systems globally prioritize value-based care, device manufacturers are being pressured to demonstrate clinical efficacy alongside cost-efficiency. The vision care segment continues to act as a stable foundation for the market, while the surgical and diagnostic segments provide the highest growth potential through innovation in femtosecond lasers, premium intraocular lenses (IOLs), and robotic-assisted surgical platforms.
- Leading Country: The United States leads the market in terms of value, driven by a high volume of ophthalmic surgeries and favorable reimbursement policies for advanced IOLs.
- High-Growth Segment: The surgical devices segment, specifically Minimally Invasive Glaucoma Surgery (MIGS) devices, is expected to see rapid adoption.
- Patient Demographics: The "Silver Economy" is a primary driver, as the population aged 65 and over is most susceptible to chronic ocular conditions requiring long-term management.
- Innovation Focus: R&D investments are increasingly directed toward biocompatible materials and drug-eluting contact lenses to improve patient compliance and outcomes.
- Strategic Consolidation: Large-scale mergers and acquisitions among top-tier players are consolidating market share and expanding product portfolios across both surgical and vision care domains.
Ophthalmic Device Market Drivers Analysis
The primary catalysts for market growth include the rising prevalence of chronic eye disorders and the continuous evolution of ophthalmic surgical technology. As diagnostic accuracy improves, more patients are being funneled into surgical pipelines, particularly for cataract and vitreoretinal procedures. Moreover, the increasing public-private partnerships focused on vision screening in schools and workplaces are broadening the reach of primary eye care services.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Prevalence of Geriatric Eye Diseases | +2.1% | Global (High in Europe & Japan) | 2025 - 2034 |
| Technological Advancements in AI-Diagnostics | +1.8% | North America & APAC | 2026 - 2034 |
| Expansion of Ambulatory Surgical Centers (ASCs) | +1.2% | United States & Germany | 2025 - 2030 |
| Increasing Incidence of Myopia in Youth | +1.1% | Asia-Pacific (China/South Korea) | 2025 - 2034 |
Ophthalmic Device Market Restraints Analysis
Despite robust growth, the market faces significant hurdles such as the high cost of sophisticated ophthalmic equipment and a critical shortage of skilled ophthalmologists in developing regions. Furthermore, the lengthy and stringent regulatory approval processes for new surgical devices can delay product launches and increase the overall cost of innovation, limiting the entry of smaller startups into the high-end surgical market.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Advanced Ophthalmic Systems | -0.9% | Latin America & Africa | 2025 - 2034 |
| Stringent Regulatory & Compliance Standards | -0.7% | European Union (MDR Impact) | 2025 - 2028 |
| Limited Reimbursement for New Technologies | -0.5% | Developing Nations | 2026 - 2032 |
Ophthalmic Device Market Opportunities Analysis
The emergence of tele-ophthalmology and the development of cost-effective, handheld diagnostic devices offer immense opportunities for market expansion in rural and underserved areas. Additionally, the move toward personalized ophthalmology, including customized IOLs and gene therapy delivery devices, is opening new revenue streams for manufacturers who can integrate biotechnology with medical device engineering.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adoption of Tele-Ophthalmology Platforms | +1.5% | Global (Focus on Rural Areas) | 2025 - 2034 |
| Growth of Smart Contact Lenses & Wearables | +1.3% | North America & Japan | 2027 - 2034 |
| Emerging Markets Infrastructure Development | +1.4% | India, Brazil, Southeast Asia | 2026 - 2034 |
Ophthalmic Device Market Challenges Impact Analysis
Maintaining data security in connected Ophthalmic Device and managing the supply chain for specialized components remain critical challenges. As devices become more integrated with hospital networks, the risk of cybersecurity breaches increases. Additionally, the environmental impact of disposable surgical instruments is leading to a push for sustainable manufacturing practices, which may require significant operational adjustments.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Cybersecurity Risks in Connected Devices | -0.4% | Developed Markets | 2025 - 2034 |
| Shortage of Skilled Ophthalmic Technicians | -0.6% | Global | 2025 - 2030 |
| Sustainability & Waste Management Regulations | -0.3% | Europe & North America | 2026 - 2034 |
Ophthalmic Device Market - Updated Report Scope
This comprehensive report provides a deep-dive analysis of the global Ophthalmic Device industry, covering the entire ecosystem from vision care products to advanced surgical robotics and diagnostic imaging systems. The scope includes a detailed evaluation of historical trends, current market dynamics, and future projections based on rigorous statistical modeling. The report emphasizes the role of technological disruption, regulatory shifts, and changing patient demographics in shaping the competitive landscape over the next decade. Stakeholders can utilize this data for strategic planning, investment analysis, and identifying high-growth opportunities within specific product categories and geographic regions.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 58.80 Billion |
| Market Forecast in 2034 | USD 101.32 Billion |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Alcon Inc., Johnson & Johnson Vision Care, Bausch + Lomb, Carl Zeiss Meditec AG, EssilorLuxottica, Topcon Corporation, Nidek Co. Ltd., Hoya Corporation, Canon Inc., Glaukos Corporation, Iridex Corporation, Staar Surgical Company, Ziemer Ophthalmic Systems, Heine Optotechnik, Lumenis Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Ophthalmic Device market is multi-faceted, with segmentation based on product functionality, clinical application, and end-user environment. Vision care remains the dominant segment by volume, driven by the mass-market demand for corrective eyewear and the growing popularity of daily disposable contact lenses. However, the diagnostic and surgical segments are witnessing higher value growth due to the introduction of high-margin technologies such as femtosecond lasers and optical coherence tomography (OCT) systems that offer superior resolution for retinal mapping. Understanding these segments is crucial for manufacturers to align their R&D efforts with specific clinical needs and procurement patterns in different healthcare settings.
- Vision Care Segment: Includes contact lenses (spherical, toric, multifocal) and spectacle lenses, which are experiencing steady growth due to rising myopia rates and fashion-driven eyewear trends.
- Surgical Devices Segment: Encompasses intraocular lenses (IOLs), phacoemulsification systems, and refractive lasers. The shift toward premium IOLs (trifocal and EDOF) is a significant value driver here.
- Diagnostic & Monitoring Devices: Covers high-tech imaging tools like fundus cameras, OCT systems, and tonometers, where AI integration is drastically reducing diagnosis time.
- End-User Analysis: While hospitals remain major purchasers, there is a distinct trend toward decentralized care, with ophthalmic clinics and specialized eye centers becoming primary hubs for routine procedures and diagnostics.
Regional Highlights
- North America: The largest market share holder, characterized by a sophisticated reimbursement landscape and early adoption of robotic ophthalmic surgery. The United States is the primary contributor, supported by high R&D spending.
- Europe: A mature market with a strong emphasis on regulatory compliance and public healthcare funding. Germany, France, and the UK are leaders in cataract and glaucoma device consumption.
- Asia-Pacific: The fastest-growing region, driven by the massive population bases in China and India. Rapidly improving healthcare infrastructure and a rising prevalence of diabetic retinopathy are creating significant demand.
- Latin America: Showing moderate growth as Brazil and Mexico modernize their healthcare facilities, though market expansion is occasionally tempered by economic volatility.
- Middle East & Africa: A developing market with localized pockets of high demand, particularly in the GCC countries, focusing on establishing specialized eye care hospitals.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Ophthalmic Device Market.- Alcon Inc.
- Johnson & Johnson Vision Care, Inc.
- Bausch + Lomb (Bausch Health Companies Inc.)
- Carl Zeiss Meditec AG
- EssilorLuxottica SA
- Topcon Corporation
- Nidek Co., Ltd.
- Hoya Corporation
- Canon Inc.
- Glaukos Corporation
- Iridex Corporation
- Staar Surgical Company
- Ziemer Ophthalmic Systems AG
- Heine Optotechnik GmbH & Co. KG
- Lumenis Ltd.
- Second Sight Medical Products, Inc.
- Quantel Medical (Lumibird Group)
- Oculus Optikgeräte GmbH
- Ellex Medical Lasers Limited
Frequently Asked Questions
What is the current market size of the global Ophthalmic Device industry?
The global Ophthalmic Device market is estimated to be valued at USD 58.80 Billion in 2025 and is expected to reach approximately USD 101.32 Billion by 2034, growing at a CAGR of 6.2%.
Which segment is expected to witness the highest growth rate?
The surgical devices segment, particularly Minimally Invasive Glaucoma Surgery (MIGS) and premium Intraocular Lenses (IOLs), is expected to witness the highest value growth due to technological innovations and an aging patient demographic.
How is Artificial Intelligence impacting the Ophthalmic Device market?
AI is significantly enhancing the diagnostic segment by providing automated screening for conditions like diabetic retinopathy and glaucoma, allowing for faster, more accurate detection and reducing the workload on clinicians.
Which region holds the largest share of the Ophthalmic Device market?
North America currently holds the largest market share, driven by advanced healthcare systems, high per capita healthcare spending, and the rapid adoption of new ophthalmic technologies.
What are the primary challenges facing manufacturers in this market?
Key challenges include stringent regulatory requirements (such as the EU MDR), high costs associated with specialized equipment R&D, and a shortage of trained ophthalmic specialists in emerging economies.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
