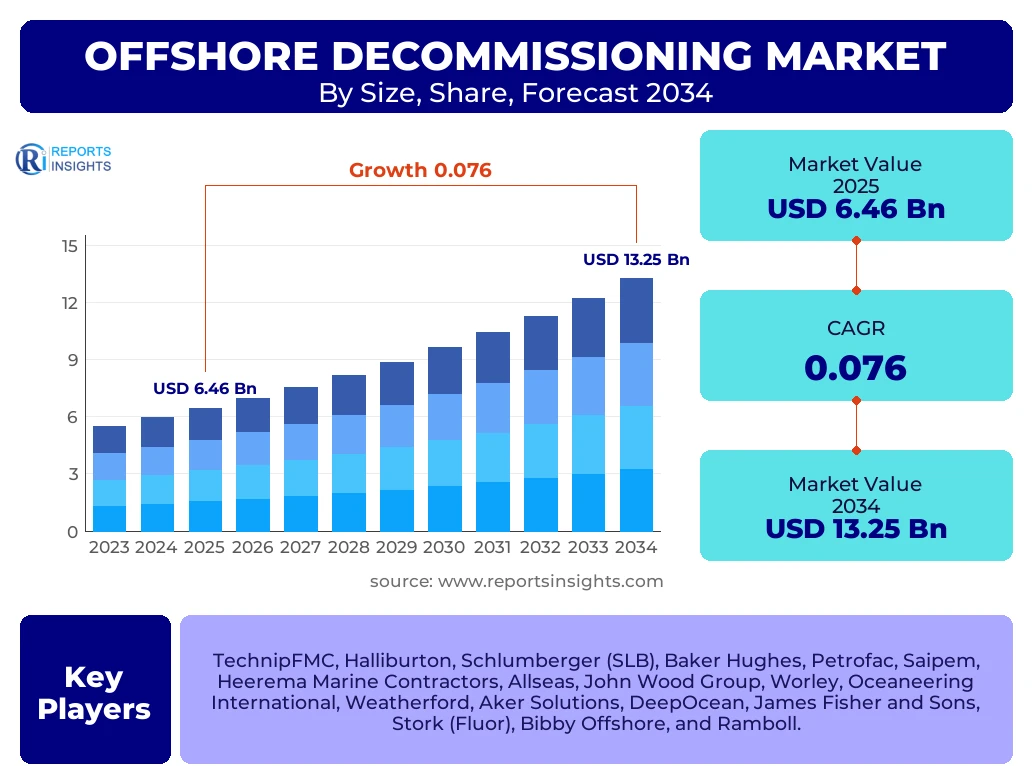
Offshore Decommissioning Market
Offshore Decommissioning Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711616 | Published On : November 08, 2026 |
Format : 


 | Author : Seema Bhateja
Offshore Decommissioning Market Size
According to Reports Insights Consulting Pvt Ltd, The Offshore Decommissioning Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.6% between 2025 and 2034. The market is estimated at USD 6.95 Billion in 2026 and is projected to reach USD 13.25 Billion by the end of the forecast period in 2034.
Key Offshore Decommissioning Market Trends & Insights
The offshore decommissioning landscape is currently navigating a pivotal transition characterized by the convergence of stringent environmental regulations and the natural lifecycle maturation of major oil and gas basins. Stakeholders are increasingly prioritizing cost-efficient abandonment strategies as profit margins in mature fields diminish. A notable trend is the shift toward Integrated Project Management (IPM) models, where operators outsource the entire decommissioning scope to specialized service providers to mitigate risks and streamline logistics. Furthermore, the adoption of advanced robotics and remotely operated vehicles (ROVs) is revolutionizing the subsea cutting and removal process, significantly enhancing safety protocols and reducing the carbon footprint of the decommissioning vessels themselves.
- Largest Region: Europe remains the dominant market, driven primarily by extensive activities in the North Sea UK and Norwegian sectors where aging infrastructure has reached the end of its design life.
- Fastest Growing Region: Asia Pacific is anticipated to exhibit the highest growth rate, fueled by emerging regulatory frameworks in countries like Malaysia, Indonesia, and Australia, coupled with a massive backlog of idle platforms.
- Largest Segment: Well Plugging and Abandonment (P&A) accounts for the largest market share, often representing 45 percent to 55 percent of total decommissioning expenditures due to the technical complexity and duration of downhole operations.
- Technological Shift: There is a rising trend in the "Rigs-to-Reefs" program in the Gulf of Mexico, where retired jackets are repurposed as artificial reefs to support marine biodiversity, providing a cost-effective and environmentally beneficial alternative to full onshore disposal.
Key Takeaways Offshore Decommissioning Market Size & Forecast
The global outlook for offshore decommissioning is robust, with an estimated 2,500 to 3,000 structures expected to be decommissioned over the next decade. The market forecast is heavily influenced by oil price volatility; while lower prices accelerate the cessation of production (CoP), they also constrain the capital expenditure available for immediate decommissioning activities. Conversely, stable pricing allows operators to fulfill their regulatory obligations with greater financial predictability. The industry is seeing a move toward "campaigning," where multiple platforms in proximity are decommissioned in a single continuous operation to achieve economies of scale and reduce mobilization costs for heavy-lift vessels.
- Leading Country: The United Kingdom leads in total expenditure, with the North Sea being a primary global hub for decommissioning innovation and specialized vessel deployment.
- Strategic Mandates: Regulatory bodies like OSPAR in the Northeast Atlantic are tightening rules on "leave in place" exceptions, forcing a higher volume of full removals.
- Energy Transition Synergy: Decommissioning is increasingly linked to the energy transition, as some offshore assets are being evaluated for repurposing for Carbon Capture and Storage (CCS) or as foundations for offshore wind substations.
- Cost Reduction Targets: Industry initiatives aim to reduce decommissioning costs by 35 percent through standardization and improved supply chain collaboration.
Offshore Decommissioning Market Drivers Analysis
The primary driver for the offshore decommissioning market is the aging of global offshore infrastructure, much of which was installed during the production booms of the 1970s and 1980s. As these assets reach their economic limit and mechanical integrity declines, the legal obligation to remove them becomes a non-negotiable liability for operators. Furthermore, the global push for environmental sustainability is forcing a more transparent and systematic approach to asset retirement, ensuring that marine ecosystems are protected from potential leaks or structural collapses from abandoned wells and platforms.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Environmental Regulations (OSPAR/BSEE) | +2.1% | Europe & North America | 2025 - 2034 |
| Aging Infrastructure in Mature Basins | +1.8% | Global | 2025 - 2030 |
| Advancements in Heavy-Lift Vessel Technology | +1.2% | Global | 2027 - 2034 |
| Economic Cessation of Production (CoP) | +1.5% | Asia Pacific & MEA | 2025 - 2034 |
Offshore Decommissioning Market Restraints Analysis
Despite the high volume of potential projects, the market faces significant restraints, primarily the high capital intensity and the lack of direct return on investment for operators. Decommissioning is essentially a "cost center," and in periods of financial uncertainty, companies often defer these activities through life-extension projects. Additionally, the technical challenges of removing structures from deepwater environments or HPHT (High Pressure High Temperature) wells present significant risks that can lead to cost overruns and project delays.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Operational Costs and Financial Liability | -1.4% | Global | 2025 - 2034 |
| Complex Subsea Technical Challenges | -0.9% | Deepwater regions (GoM, Brazil) | 2026 - 2034 |
| Regulatory Delays and Bureaucratic Hurdles | -0.7% | Asia Pacific & Latin America | 2025 - 2030 |
Offshore Decommissioning Market Opportunities Analysis
The decommissioning sector offers substantial opportunities for innovation, particularly in the circular economy where steel and components from removed platforms can be recycled or repurposed. There is also a growing market for specialized insurance and financial products designed to manage decommissioning liabilities. Furthermore, as the industry moves toward deeper waters, there is a burgeoning demand for deepwater P&A technologies and specialized subsea tooling that can operate in extreme environments.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Asset Repurposing for CCS and Hydrogen | +1.3% | Europe (North Sea) | 2028 - 2034 |
| Growth in Deepwater Abandonment Services | +1.6% | Brazil & Gulf of Mexico | 2027 - 2034 |
| Digital Twin Integration for Decommissioning Planning | +0.8% | Global | 2025 - 2034 |
Offshore Decommissioning Market Challenges Impact Analysis
One of the most pressing challenges is the shortage of specialized skills and the availability of heavy-lift assets. As the global energy sector simultaneously builds out offshore wind capacity, there is intense competition for the same heavy-lift vessels and technical personnel required for decommissioning. Managing the hazardous waste, including Naturally Occurring Radioactive Material (NORM) and mercury, also poses significant logistical and safety challenges during the onshore disposal phase.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Vessel Availability and Competition with Wind Sector | -1.1% | Europe & North America | 2025 - 2034 |
| Hazardous Waste Management (NORM/Mercury) | -0.6% | Global | 2025 - 2034 |
| Geopolitical Instability Affecting Supply Chains | -0.5% | Middle East & Russia | 2025 - 2028 |
Offshore Decommissioning Market - Updated Report Scope
This comprehensive market report provides an in-depth analysis of the global offshore decommissioning sector, covering various service types, structure types, and depths. It examines the regulatory landscape, technological advancements, and the competitive dynamics among top-tier oilfield service companies and engineering firms. The report highlights the transition from traditional abandonment methods to innovative, data-driven strategies that optimize costs and ensure environmental compliance across all major oil and gas provinces.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 6.46 Billion |
| Market Forecast in 2034 | USD 13.25 Billion |
| Growth Rate | 7.6% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | TechnipFMC, Halliburton, Schlumberger (SLB), Baker Hughes, Petrofac, Saipem, Heerema Marine Contractors, Allseas, John Wood Group, Worley, Oceaneering International, Weatherford, Aker Solutions, DeepOcean, James Fisher and Sons, Stork (Fluor), Bibby Offshore, and Ramboll. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The offshore decommissioning market is segmented primarily by service type, which dictates the majority of the project logistics and cost structure. Well Plugging and Abandonment (P&A) is the most critical segment, involving the permanent sealing of the reservoir and the removal of the wellhead. This process is highly regulated and requires specialized drilling rigs or vessel-based intervention units. The Platform Removal segment follows, which involves the dismantling of topsides and the removal of the jacket structures, often necessitating heavy-lift vessels with lifting capacities exceeding 10,000 tons. Subsea infrastructure decommissioning is also a significant segment, focusing on the retrieval of pipelines, cables, and manifolds that must be cleared to ensure safe navigation and environmental restoration.
- Well Plugging & Abandonment (P&A): Dominates the market due to the high volume of wells requiring permanent isolation to prevent hydrocarbon leaks.
- Platform Removal: Includes both topside dismantling and the complex task of removing steel or concrete jackets from the seabed.
- Shallow Water Decommissioning: Currently the largest volume of activity, particularly in mature regions like the Gulf of Mexico and the southern North Sea.
- Deepwater Decommissioning: A high-growth segment involving specialized subsea robotics and advanced engineering for FPSO and TLP removals.
- Site Clearance: Ensuring the seabed is returned to its pre-drilling state, requiring sophisticated sonar and debris recovery equipment.
Regional Highlights
The regional dynamics of the offshore decommissioning market are heavily influenced by the age of the oil basins and the maturity of local environmental laws. Europe, specifically the UK and Norway, represents the most advanced market with established regulatory bodies and a clear pipeline of projects. In North America, the Gulf of Mexico remains a highly active region with thousands of structures in shallow water that have exceeded their 25-year lifespan. Asia Pacific is emerging as a critical growth engine, with countries like Thailand and Malaysia implementing new decommissioning guidelines to manage their aging assets. Latin America, led by Brazil, is preparing for a massive wave of FPSO decommissioning as their early pre-salt and post-salt fields enter the late-life stage.
- Europe: The largest market globally; the UK Continental Shelf (UKCS) is the primary driver of decommissioning spend.
- North America: Focused on high-volume, standardized shallow-water removals and an increasing focus on deepwater P&A in the Gulf of Mexico.
- Asia Pacific: The fastest-growing region; high potential in the Gulf of Thailand and the Malay Basin.
- Middle East: Increasing activity in the Persian Gulf as older jack-up platforms and infrastructure require replacement or removal.
- Latin America: High-value projects emerging in Brazil involving the decommissioning of complex floating production systems.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Offshore Decommissioning Market.- TechnipFMC
- Halliburton
- Schlumberger (SLB)
- Baker Hughes
- Petrofac
- Saipem
- Heerema Marine Contractors
- Allseas
- John Wood Group
- Worley
- Oceaneering International
- Weatherford
- Aker Solutions
- DeepOcean
- James Fisher and Sons
- Stork (Fluor)
- Bibby Offshore
- Ramboll
Frequently Asked Questions
What is the most expensive part of offshore decommissioning?
Well Plugging and Abandonment (P&A) is consistently the most expensive component of the decommissioning process. It can account for over 50% of total project costs due to the need for specialized drilling rigs, the duration of downhole work, and the complexities of ensuring a permanent, leak-proof seal in varying geological conditions.
Why is the Europe region leading the offshore decommissioning market?
Europe leads due to the maturity of the North Sea oil and gas fields, which were developed extensively in the 1970s. Additionally, strict environmental standards set by the OSPAR Commission mandate the near-total removal of offshore structures, creating a large and consistent volume of decommissioning projects compared to other regions.
What are the environmental benefits of the "Rigs-to-Reefs" program?
The program involves leaving part of the jacket structure on the seabed to act as an artificial reef. This supports marine biodiversity by providing a habitat for coral, fish, and other marine life. It also reduces the carbon emissions associated with transporting massive structures to shore for dismantling and recycling.
How does oil price volatility impact the decommissioning market?
Low oil prices often lead to the early Cessation of Production (CoP) as fields become uneconomical, increasing the immediate demand for decommissioning. However, it also reduces the cash flow available for operators to fund these projects. High oil prices may delay decommissioning as operators invest in life-extension technologies to continue production.
What role does technology play in reducing decommissioning costs?
Technology plays a vital role through advancements like single-lift vessel technology, which removes an entire topside in one go, saving weeks of offshore labor. Other technologies include abrasive water-jet cutting, autonomous underwater vehicles (AUVs) for site surveys, and AI-driven planning tools that optimize vessel logistics and scheduling.
Author
S
Seema Bhateja is a Manger Energy and Power Research Industry with 7+ years of experience in the Energy and Power Industry. She specializes in energy market intelligence, power generation analysis, renewable energy assessment, demand forecasting, competitive benchmarking, grid infrastructure evaluation, regulatory landscape analysis, market sizing, and investment trend analysis across conventional and clean energy sectors. Her research integrates industry expertise with data-driven methodologies to help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, anticipate evolving market trends, and strengthen their competitive positioning in the global energy and power market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
