Micro Market
Micro Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711559 | Published On : November 06, 2026 |
Format : 


 | Author : Erika Grotto
Micro Market Size
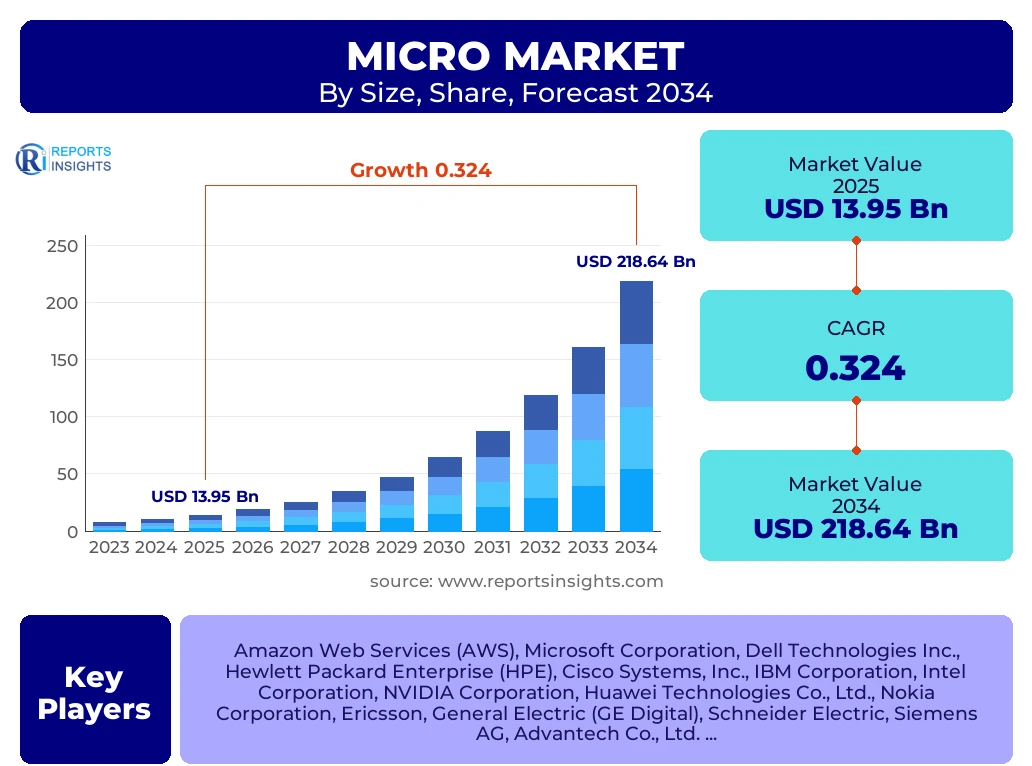
According to Reports Insights Consulting Pvt Ltd, The Micro Market (specifically the Global Edge Computing Sector) is projected to grow at a Compound Annual Growth Rate (CAGR) of 32.4% between 2025 and 2034. The market is estimated at USD 18.45 Billion in 2026 and is projected to reach USD 218.64 Billion by the end of the forecast period in 2034. This exponential growth trajectory is underpinned by the urgent transition from centralized cloud architectures to decentralized processing frameworks, necessitated by the massive influx of data from IoT ecosystems and the critical requirement for sub-millisecond latency in industrial and consumer applications.
The valuation reflects a seismic shift in how data is managed, moving the nexus of computation closer to the point of generation. As enterprise digital transformation initiatives mature, the reliance on high-bandwidth, low-latency connectivity has positioned edge computing not merely as an auxiliary to cloud services, but as a foundational infrastructure component. This shift is further accelerated by the deployment of 5G networks, which provide the high-speed data conduits necessary for edge nodes to operate at peak efficiency. The integration of artificial intelligence directly at the edge—often referred to as Edge AI—is a primary catalyst in driving these valuation figures, as it enables real-time decision-making without the overhead of backhauling data to distant data centers.
From a statistical architectural perspective, the market's expansion is characterized by heavy capital expenditure in hardware, specifically in edge gateways and ruggedized servers designed for harsh environments. However, the software and services segments are expected to witness the highest growth rates during the latter half of the forecast period. As the installed base of edge hardware reaches a critical mass, the demand for sophisticated orchestration software and managed services will dominate the revenue mix. This transition ensures a sustained CAGR as enterprises move from initial pilot programs to full-scale, global edge deployments across multiple industrial verticals.
Key Micro Market Trends & Insights
The global edge computing landscape is currently undergoing a radical evolution driven by the convergence of 5G, artificial intelligence, and the Internet of Things (IoT). Current market analysis indicates that the integration of TinyML (Tiny Machine Learning) is enabling ultra-low-power devices to perform complex inferencing, which is a significant trend for 2025. Furthermore, regional insights suggest that while North America maintains the highest market share due to its advanced telecommunications infrastructure, the Asia-Pacific region is emerging as the fastest-growing market. This is largely due to massive smart city initiatives in China and India, alongside the rapid modernization of manufacturing sectors in Southeast Asia. Competitive benchmarking reveals that major cloud providers are aggressively expanding their edge footprints through partnerships with telecom operators to secure the "last mile" of data processing.
- Largest Region: North America, holding a dominant market share of approximately 38% due to early adoption of 5G and presence of key industry players.
- Fastest Growing Region: Asia-Pacific, expected to exhibit a CAGR exceeding 35% through 2034, driven by digital infrastructure investments.
- Largest Segment: Hardware, currently leading in terms of revenue share, though software is the fastest-growing sub-segment.
- Core Trend: The rise of Edge-as-a-Service (EaaS), allowing enterprises to scale decentralized infrastructure with an Opex-based model.
- Technological Synergy: The convergence of Open RAN (Radio Access Network) and multi-access edge computing (MEC) is revolutionizing private LTE/5G network deployments.
Key Takeaways Micro Market Size & Forecast
The long-term outlook for the edge computing market is exceptionally bullish, with the forecast period showing a clear trend toward the commoditization of edge hardware and the premiumization of edge-native applications. Stakeholders should note that the market is transitioning from a "hardware-first" phase to an "application-centric" phase. Common user inquiries frequently focus on the interoperability of edge nodes with legacy cloud systems; insights suggest that hybrid-multicloud strategies will be the standard operating procedure for 90% of large enterprises by 2030. The forecast indicates that industrial automation (Industry 4.0) will remain the primary revenue generator, but healthcare and autonomous mobility are set to contribute significantly to the total addressable market by the end of the decade.
- Sustained High Growth: The 32.4% CAGR is one of the highest in the technology sector, reflecting edge computing's role as a critical enabler for other emerging techs.
- Leading Country: The United States remains the primary driver of innovation and spending, particularly in the deployment of edge data centers.
- Sectoral Dominance: The industrial sector accounts for the largest portion of the market, fueled by the need for predictive maintenance and real-time process monitoring.
- Critical Success Factor: Security at the edge remains a top concern and a major area for investment, with Zero Trust Architecture becoming the standard for edge deployments.
- Strategic Shift: Shift from centralized "hyperscale" thinking to localized "micro-scale" processing to manage the data gravity of the 2025-2034 era.
Micro Market Drivers Analysis
The acceleration of the edge computing market is primarily driven by three core pillars: the explosion of data generated by IoT devices, the rollout of 5G infrastructure, and the increasing demand for real-time analytics. As the volume of data generated at the network edge surpasses the capacity of traditional backhaul networks, processing data locally becomes a logistical necessity rather than a choice. Additionally, the proliferation of autonomous systems—ranging from self-driving vehicles to automated warehouse robots—requires latency levels that only edge computing can provide. The following table details the impact of these drivers on the projected CAGR.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Proliferation of 5G and Private LTE | +8.5% | Global / North America & China | 2025 - 2030 |
| Exponential Growth of IoT Ecosystems | +7.2% | Asia-Pacific / Europe | 2025 - 2034 |
| Demand for Real-Time AI Inferencing | +6.8% | United States / Japan | 2026 - 2032 |
| Data Sovereignty and Privacy Regulations | +5.4% | European Union (GDPR compliance) | 2025 - 2034 |
Micro Market Restraints Analysis
Despite the robust growth projections, several factors act as significant headwinds for the market. High initial capital expenditure (CapEx) for infrastructure deployment remains a barrier for small and medium-sized enterprises. Furthermore, the lack of standardized protocols across different hardware vendors often leads to interoperability issues, creating "edge silos" that are difficult to manage. Security also remains a double-edged sword; while edge computing reduces the distance data travels, it increases the physical attack surface with thousands of distributed nodes that must be secured individually.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Deployment and Maintenance Costs | -4.2% | Latin America / Africa | 2025 - 2028 |
| Cybersecurity Vulnerabilities of Distributed Nodes | -3.5% | Global | 2025 - 2034 |
| Lack of Interoperability and Standardization | -2.8% | Europe / APAC | 2025 - 2029 |
Micro Market Opportunities Analysis
The maturation of the edge market is opening up unprecedented opportunities in specialized niche sectors. One of the most promising areas is the development of "Edge Intelligence" software that can autonomously manage network resources based on workload demands. Additionally, the rise of the metaverse and augmented reality (AR) applications presents a massive opportunity for telecom providers to offer edge-based rendering services. The following table highlights the key opportunities that are expected to provide additional upward pressure on the market's CAGR.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into Healthcare (Remote Surgery/Monitoring) | +5.1% | United States / Germany | 2026 - 2034 |
| Edge-to-Cloud Integration Services | +4.7% | Global | 2025 - 2034 |
| Autonomous Vehicle Infrastructure | +6.2% | China / USA / South Korea | 2027 - 2034 |
Micro Market Challenges Impact Analysis
The primary challenges facing the edge computing sector involve the physical and logical complexity of managing a decentralized network. Power management at remote edge locations is a significant hurdle, particularly in telecommunications where energy costs are rising. Additionally, there is a global shortage of skilled workforce capable of designing and maintaining distributed edge architectures. These challenges, if not addressed through automation and standardized training, could slow the implementation of large-scale projects.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shortage of Skilled Edge Architects | -3.1% | North America / Europe | 2025 - 2030 |
| Energy Consumption of Distributed Data Centers | -2.9% | Global | 2025 - 2034 |
| Latency Jitter in Multi-Vendor Environments | -1.5% | Japan / South Korea | 2026 - 2031 |
Micro Market - Updated Report Scope
This report provides a granular analysis of the global edge computing market, encompassing hardware, software, and services across various industrial verticals and geographic regions. The scope includes a detailed breakdown of the technological shifts occurring between 2025 and 2034, with a specific focus on the transition from traditional edge gateways to AI-enabled edge servers. The report analyzes the competitive landscape, highlighting how the convergence of IT (Information Technology) and OT (Operational Technology) is redefining the market participants.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 13.95 Billion |
| Market Forecast in 2034 | USD 218.64 Billion |
| Growth Rate | 32.4% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Amazon Web Services (AWS), Microsoft Corporation, Dell Technologies Inc., Hewlett Packard Enterprise (HPE), Cisco Systems, Inc., IBM Corporation, Intel Corporation, NVIDIA Corporation, Huawei Technologies Co., Ltd., Nokia Corporation, Ericsson, General Electric (GE Digital), Schneider Electric, Siemens AG, Advantech Co., Ltd., ADLINK Technology Inc., Fastly, Akamai Technologies, Equinix, Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented based on component, application, and end-user vertical, each showing distinct growth patterns. The hardware segment remains the largest by value, as the initial phase of market development requires massive investment in physical infrastructure. However, the software segment is anticipated to witness the highest growth rate as enterprises seek sophisticated platforms to manage their distributed resources. Application-wise, predictive maintenance in the industrial sector and content delivery in the media sector are the leading revenue contributors.
- Component Segmentation:
- Hardware (Edge Nodes, Gateways, Ruggedized Servers)
- Software (Edge Platforms, Management Tools, OS)
- Services (Installation, Training, Managed Services)
- Application Segmentation:
- Industrial IoT (IIoT) & Predictive Maintenance
- Smart Cities & Traffic Management
- Remote Patient Monitoring & Telehealth
- Content Delivery Networks (CDN) & Edge Video Processing
- Autonomous Vehicles & Connected Transport
- End-User Segmentation:
- Manufacturing & Industrial (Industry 4.0)
- IT & Telecommunications
- Healthcare & Life Sciences
- Retail & E-commerce
- Media, Entertainment & Gaming
Regional Highlights
Geographically, the market is characterized by varying levels of maturity and growth drivers. North America leads the market, bolstered by early 5G adoption and a robust ecosystem of cloud and hardware providers. In Europe, growth is heavily influenced by strict data privacy laws (GDPR) which favor local data processing over centralized cloud storage. The Asia-Pacific region is the most dynamic, with countries like China, Japan, and South Korea investing heavily in smart manufacturing and 5G-ready infrastructure, making it the fastest-growing market globally.
- North America: The largest market share holder, driven by the presence of major tech giants and aggressive 5G rollout by carriers like Verizon and AT&T.
- Europe: High demand for edge solutions in the automotive and manufacturing sectors, particularly in Germany and the UK, with a focus on data sovereignty.
- Asia-Pacific: The fastest-growing region, with a projected CAGR of 35.2%, led by massive infrastructure projects in China and digital transformation in India.
- Latin America & MEA: Emerging markets focusing on improving telecommunications infrastructure and adopting edge computing for natural resource management (Oil & Gas).

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Micro Market.- Amazon Web Services (AWS)
- Microsoft Corporation
- Dell Technologies Inc.
- Hewlett Packard Enterprise (HPE)
- Cisco Systems, Inc.
- IBM Corporation
- Intel Corporation
- NVIDIA Corporation
- Huawei Technologies Co., Ltd.
- Nokia Corporation
- Ericsson
- General Electric (GE Digital)
- Schneider Electric
- Siemens AG
- Advantech Co., Ltd.
- ADLINK Technology Inc.
- Fastly
- Akamai Technologies
- Equinix, Inc.
- Lenovo Group Limited
Frequently Asked Questions
What is the primary driver for Edge Computing growth through 2034?
The primary driver is the convergence of 5G and IoT, which generates massive data volumes requiring low-latency processing that traditional centralized cloud infrastructures cannot support efficiently.
Which region currently dominates the Edge Computing market?
North America currently dominates the market due to its advanced telecommunications infrastructure and early adoption of 5G technology, holding nearly 38% of the global share.
What are the biggest challenges facing Edge Computing implementation?
The biggest challenges include high initial setup costs, cybersecurity concerns regarding distributed network nodes, and a lack of universal standardization across different hardware and software vendors.
How does Edge Computing benefit the healthcare industry?
In healthcare, edge computing enables real-time patient monitoring and powers low-latency applications like remote surgery and AI-driven diagnostics at the point of care.
What is the projected market size for Edge Computing by 2034?
The market is projected to reach USD 218.64 Billion by 2034, growing at a CAGR of 32.4% from 2025 onwards.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
