Medical Tubing Market
Medical Tubing Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711161 | Published On : October 13, 2026 |
Format : 


 | Author : Erika Grotto
Medical Tubing Market Size
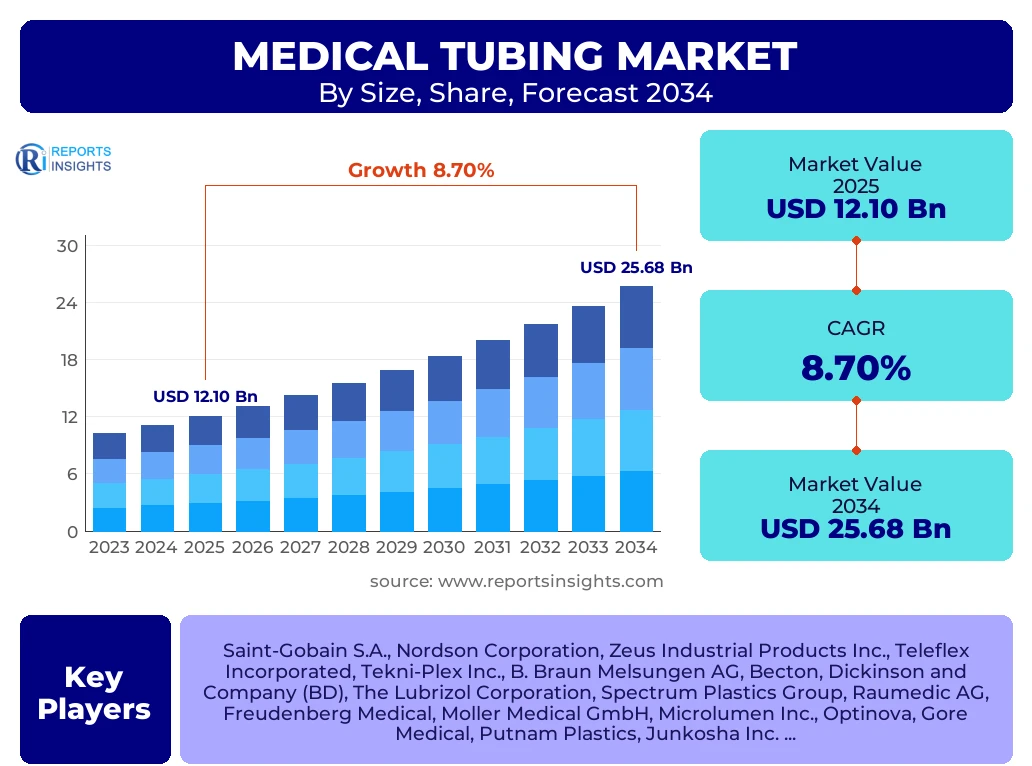
According to Reports Insights Consulting Pvt Ltd, The Medical Tubing Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.7% between 2025 and 2034. The market is estimated at USD 13.15 Billion in 2026 and is projected to reach USD 25.68 Billion by the end of the forecast period in 2034.
Key Medical Tubing Market Trends & Insights
The global medical tubing industry is undergoing a significant transformation driven by the rapid evolution of minimally invasive surgical procedures and the escalating demand for home-based healthcare solutions. As healthcare providers seek to reduce hospital stay durations and improve patient outcomes, the requirement for high-precision, small-diameter tubing for catheters and endoscopic tools has surged. Technological advancements in extrusion processes, such as multi-lumen and co-extrusion techniques, are enabling the production of tubing with complex geometries and integrated functionalities. Furthermore, the shift toward value-based care is pushing manufacturers to adopt cost-effective yet high-performance materials that comply with increasingly stringent global regulatory standards, such as the European Union Medical Device Regulation (EU MDR).
Another prominent trend is the integration of smart technologies within medical tubing systems. Engineers are developing tubing that incorporates sensors for real-time monitoring of fluid flow, temperature, and pressure, which is particularly critical in intensive care units and advanced drug delivery systems. The market is also seeing a move away from traditional phthalate-plasticized PVC toward safer alternatives like Thermoplastic Elastomers (TPE) and specialized Silicones, driven by environmental concerns and patient safety protocols. Competitive benchmarking reveals that leading players are focusing on vertical integration and localized manufacturing to mitigate supply chain risks and cater to the specific needs of emerging markets in the Asia-Pacific region.
- Largest Region: North America remains the dominant market owing to its sophisticated healthcare infrastructure and high healthcare expenditure.
- Fastest Growing Region: Asia-Pacific is expected to witness the highest CAGR due to increasing medical tourism and expanding healthcare access in China and India.
- Largest Material Segment: Polyvinyl Chloride (PVC) continues to hold the largest market share due to its versatility, cost-effectiveness, and established safety profile.
- Leading Application: Bulk Disposable Tubing represents the largest application segment, supported by the high volume of routine medical procedures globally.
- Emerging Material Trend: High-performance fluoropolymers and bio-based elastomers are gaining traction for specialty surgical applications.
Key Takeaways Medical Tubing Market Size & Forecast
The Medical Tubing market is characterized by a steady growth trajectory, underpinned by the structural demographic shift toward an aging global population. This demographic trend directly correlates with a higher prevalence of chronic diseases such as cardiovascular disorders, diabetes, and respiratory ailments, all of which necessitate the use of various medical tubing products for diagnosis and treatment. Market analysis indicates that while high-volume commodity tubing remains the backbone of the industry, value-added specialty tubing is where the highest profit margins reside. Stakeholders are increasingly investing in Research and Development to create antimicrobial and thromboresistant coatings that reduce hospital-acquired infections (HAIs), a key priority for healthcare administrators worldwide.
- Market Valuation: The industry is set to nearly double in size over the next decade, reaching a valuation of over USD 25 billion by 2034.
- Regulatory Influence: Stringent FDA and EU MDR certifications act as a high barrier to entry, favoring established players with robust quality management systems.
- Material Transition: There is a marked transition from traditional materials to advanced Thermoplastic Polyurethanes (TPU) and Fluoropolymers for high-strength, low-friction applications.
- Manufacturing Innovation: Micro-extrusion technology is becoming a critical capability for producing components for the next generation of robotic surgical systems.
- Sustainability Focus: Leading manufacturers are adopting circular economy principles, focusing on recyclable materials and reducing waste in the extrusion process.
Medical Tubing Market Drivers Analysis
The primary driver for the medical tubing market is the increasing global prevalence of chronic conditions requiring long-term management. As the incidence of kidney failure, cardiovascular disease, and chronic obstructive pulmonary disease (COPD) rises, the demand for dialysis tubing, catheters, and oxygen delivery systems scales proportionally. Additionally, the rapid expansion of the geriatric population worldwide significantly boosts the consumption of medical disposables. Technological innovation in the field of interventional cardiology and neurology also plays a crucial role, as these procedures rely heavily on specialized, high-performance micro-tubing to navigate complex vascular pathways.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rise in Minimally Invasive Surgeries (MIS) | +3.2% | Global (Strongest in US & Germany) | 2025 - 2034 |
| Aging Global Population & Chronic Diseases | +2.5% | Japan, Europe, North America | 2025 - 2034 |
| Expansion of Home Healthcare Services | +1.8% | United Kingdom, Canada, USA | 2026 - 2032 |
| Advancements in Micro-Extrusion Technology | +1.2% | Germany, Switzerland, Japan | 2027 - 2034 |
Medical Tubing Market Restraints Analysis
Despite the positive growth outlook, the market faces significant restraints, primarily stemming from the volatile costs of medical-grade raw materials. High-performance polymers such as PEEK and Fluoropolymers are subject to supply chain fluctuations, which can impact the profit margins of tubing manufacturers. Furthermore, the rigorous and lengthy approval processes required by regulatory bodies like the FDA and EMA can delay the introduction of innovative products. The environmental concerns regarding the disposal of single-use medical plastics also present a long-term challenge, as healthcare systems come under pressure to reduce their carbon footprint and plastic waste.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Regulatory Compliance Standards | -1.5% | European Union, United States | 2025 - 2034 |
| Fluctuating Raw Material Prices | -0.8% | Global | 2025 - 2029 |
| Environmental Concerns & Plastic Waste Policies | -0.6% | Western Europe, California (USA) | 2028 - 2034 |
Medical Tubing Market Opportunities Analysis
Significant opportunities lie in the development of antimicrobial and bioactive tubing surfaces. With the rising cost of treating hospital-acquired infections, hospitals are willing to pay a premium for tubing that actively inhibits bacterial growth. Moreover, the emerging markets in Southeast Asia and Latin America represent a massive untapped potential as these regions invest heavily in upgrading their clinical infrastructure. The integration of 3D printing and additive manufacturing in the production of customized medical tubing for patient-specific applications also offers a high-growth avenue for specialized manufacturers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Bio-compatible & Bio-resorbable Tubing | +2.4% | USA, Germany, South Korea | 2026 - 2034 |
| Expansion into Emerging Markets (BRIC) | +2.1% | China, India, Brazil | 2025 - 2034 |
| Smart Tubing with Integrated Sensors | +1.5% | Israel, USA, Japan | 2027 - 2034 |
Medical Tubing Market Challenges Impact Analysis
The primary challenge for market participants is maintaining a balance between high precision and mass-scale production efficiency. As the demand for micro-tubing increases, the technical difficulty of maintaining tight tolerances in high-speed extrusion lines intensifies. Additionally, the entry of low-cost manufacturers from developing regions creates intense pricing pressure in the commodity tubing segment, forcing established Western players to differentiate through complex engineering and superior material science. Navigating the complex intellectual property landscape also poses a challenge for firms developing proprietary multi-layer tubing structures.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Intense Pricing Pressure in Commodity Segments | -1.2% | Global | 2025 - 2034 |
| Technical Complexity in Micro-Tubing Production | -0.9% | Advanced Manufacturing Hubs | 2025 - 2030 |
| Disruptions in Global Logistics & Supply Chains | -0.7% | Global | 2025 - 2027 |
Medical Tubing Market - Updated Report Scope
This report provides a comprehensive analysis of the global medical tubing market, covering material types, applications, and structural designs. It includes a detailed assessment of the competitive landscape, regulatory environment, and technological advancements that are shaping the future of the industry. The scope encompasses all major geographic regions and provides granular insights into the market dynamics of key countries, ensuring a robust strategic framework for stakeholders and investors.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 12.10 Billion |
| Market Forecast in 2034 | USD 25.68 Billion |
| Growth Rate | 8.7% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Saint-Gobain S.A., Nordson Corporation, Zeus Industrial Products Inc., Teleflex Incorporated, Tekni-Plex Inc., B. Braun Melsungen AG, Becton, Dickinson and Company (BD), The Lubrizol Corporation, Spectrum Plastics Group, Raumedic AG, Freudenberg Medical, Moller Medical GmbH, Microlumen Inc., Optinova, Gore Medical, Putnam Plastics, Junkosha Inc., Trelleborg AB, Merit Medical Systems, MicroLumen. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The medical tubing market is segmented based on material, structure, and application to provide a clear view of the diverse needs of the healthcare sector. Material choice is the most critical factor, as it determines biocompatibility, flexibility, and resistance to chemicals or heat. Structure segmentation reflects the increasing complexity of medical devices, while application categories highlight the volume and value drivers across different clinical settings.
- By Material:
- Polyvinyl Chloride (PVC): Dominant due to cost and versatility.
- Polyolefins (Polyethylene, Polypropylene): Used for low-density and chemical resistance.
- Thermoplastic Elastomers (TPE) & TPU: Gaining share as high-performance PVC alternatives.
- Silicones: Preferred for high-temperature and long-term implantable applications.
- Fluoropolymers (PTFE, FEP): Essential for low-friction catheter liners.
- By Structure:
- Single-Lumen: Standard tubing for simple fluid transfer.
- Multi-Lumen: Complex tubing for multi-functional catheters.
- Co-Extruded: Combining different materials for specific inner/outer properties.
- Braided/Reinforced: High-pressure and kink-resistant applications.
- By Application:
- Bulk Disposable Tubing: High volume usage in IV sets and drainage.
- Catheters & Cannulas: High value, precision-engineered segments.
- Drug Delivery: Specialized tubing for insulin pumps and oncology treatments.
- Dialysis & Filtration: Highly regulated tubing for blood processing.
Regional Highlights
- North America: The largest market share holder, driven by the presence of major medical device OEMs and an advanced regulatory framework. The US is the primary contributor, focusing on high-end specialty tubing for cardiovascular and neurological surgeries.
- Europe: The second-largest market, characterized by strict quality standards under the EU MDR. Germany, France, and the UK are leaders in medical tubing innovation, particularly in silicone and fluoropolymer applications.
- Asia-Pacific: The fastest-growing region, with China and India leading the surge. The growth is fueled by massive investments in healthcare infrastructure, a rising middle class, and the presence of low-cost manufacturing hubs transitioning toward high-quality standards.
- Latin America: Showing steady growth in Brazil and Mexico, primarily in the bulk disposable and dialysis tubing segments as medical access expands.
- Middle East & Africa: A developing market with increasing demand for basic medical supplies and a growing focus on building domestic medical device assembly capabilities.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Medical Tubing Market.- Saint-Gobain S.A.
- Nordson Corporation
- Zeus Industrial Products Inc.
- Teleflex Incorporated
- Tekni-Plex Inc.
- B. Braun Melsungen AG
- Becton, Dickinson and Company (BD)
- The Lubrizol Corporation
- Spectrum Plastics Group
- Raumedic AG
- Freudenberg Medical
- Moller Medical GmbH
- Microlumen Inc.
- Optinova
- W. L. Gore & Associates
- Putnam Plastics
- Junkosha Inc.
- Trelleborg AB
- Merit Medical Systems
- Vention Medical
Frequently Asked Questions
What is the projected growth rate of the Medical Tubing Market?
The Medical Tubing Market is expected to grow at a Compound Annual Growth Rate (CAGR) of 8.7% from 2025 to 2034, reaching a valuation of USD 25.68 Billion.
Which material is most commonly used in medical tubing?
Polyvinyl Chloride (PVC) remains the most widely used material due to its low cost, flexibility, and ease of sterilization, though TPE and Silicones are gaining ground in specialty applications.
What are the primary drivers for the Medical Tubing Market?
Key drivers include the rise in minimally invasive surgeries, an aging global population with chronic diseases, and the expansion of home-based healthcare and diagnostic services.
Which region is the fastest-growing in the medical tubing industry?
The Asia-Pacific (APAC) region is the fastest-growing market, driven by increased healthcare spending, infrastructure development, and growing medical tourism in countries like China and India.
How is technology impacting the medical tubing manufacturing process?
Advancements such as micro-extrusion, multi-lumen design, and the integration of smart sensors are allowing for more complex, functional, and miniaturized tubing suitable for advanced surgical robotics.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
