Ophthalmic Clinical Trials Market
Ophthalmic Clinical Trials Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711119 | Published On : October 09, 2026 |
Format : 


 | Author : Erika Grotto
Ophthalmic Clinical Trials Market Size
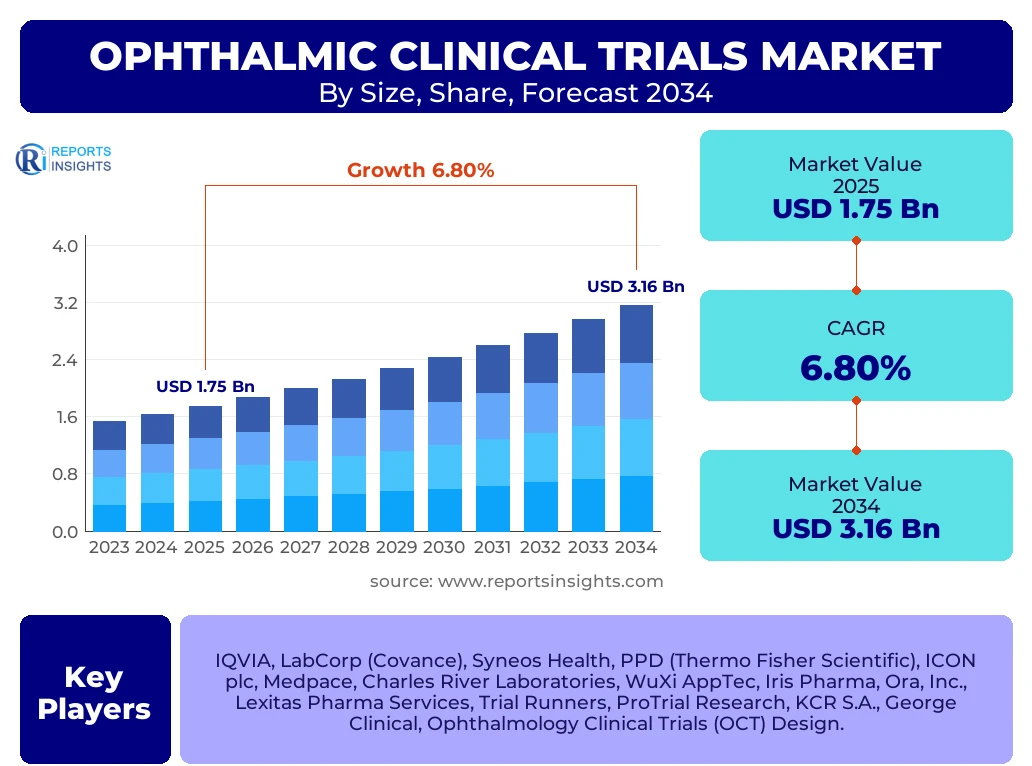
According to Reports Insights Consulting Pvt Ltd, The Ophthalmic Clinical Trials Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.8% between 2025 and 2034. The market is estimated at USD 1.87 Billion in 2026 and is projected to reach USD 3.16 Billion by the end of the forecast period in 2034.
Key Ophthalmic Clinical Trials Market Trends & Insights
The Ophthalmic Clinical Trials market is undergoing a significant transformation driven by the integration of digital health technologies and a shift toward precision medicine. Stakeholders are increasingly focusing on the development of gene therapies and advanced biologics to treat previously untreatable retinal conditions. The adoption of decentralized clinical trial (DCT) models is also gaining momentum, allowing for better patient recruitment and retention by reducing the burden of frequent site visits. Furthermore, artificial intelligence (AI) is being leveraged to enhance image analysis in ocular diagnostics, providing more accurate endpoints for clinical studies. The market is also seeing a surge in trials for Dry Eye Disease (DED) and Age-related Macular Degeneration (AMD), reflecting the growing unmet needs of an aging global population.
- Largest Region: North America remains the dominant market due to its robust pharmaceutical infrastructure, high R&D investment, and favorable regulatory environment.
- Fastest Growing Region: Asia-Pacific is expected to witness the highest CAGR, fueled by expanding healthcare access, a large patient pool, and lower operational costs for clinical research.
- Largest Segment by Phase: Phase III trials account for the largest market share in terms of value, owing to the high costs associated with large-scale patient enrollment and long-term monitoring.
- Leading Indication: Retinal disorders, including AMD and diabetic retinopathy, represent the largest segment by indication, driven by the high prevalence of these conditions globally.
- Technological Trend: The use of virtual reality (VR) and remote monitoring tools is becoming a standard in assessing visual function and patient-reported outcomes.
Key Takeaways Ophthalmic Clinical Trials Market Size & Forecast
The Ophthalmic Clinical Trials market is poised for steady growth as pharmaceutical and biotechnology companies increase their investment in vision-saving therapies. The forecast period (2025–2034) will likely see a transition from traditional small-molecule drugs to complex biological and gene-based interventions. Regulatory bodies like the FDA and EMA are providing clearer pathways for innovative ophthalmic treatments, which is encouraging more startups to enter the space. The market's expansion is further supported by the rising prevalence of diabetes-related eye complications and the global "myopia epidemic" among younger populations, necessitating extensive clinical validation for new corrective treatments.
- Market Growth Driver: The increasing incidence of vision loss and blindness worldwide is the primary catalyst for clinical research funding.
- Leading Country: The United States leads in total clinical trial volume, hosting a significant portion of the global Phase I and Phase II ophthalmic studies.
- Strategic Shift: There is a notable move toward "Real-World Evidence" (RWE) to supplement clinical trial data, particularly for post-market surveillance (Phase IV).
- Emerging Opportunity: Gene therapy for inherited retinal diseases (IRDs) is creating a high-value niche within the clinical trial ecosystem.
- Cost Management: Contract Research Organizations (CROs) are becoming indispensable partners for ophthalmic sponsors to navigate complex regulatory hurdles and optimize site selection.
Ophthalmic Clinical Trials Market Drivers Analysis
The primary driver for the ophthalmic clinical trials market is the dramatic rise in the geriatric population, which is more susceptible to age-related eye conditions such as cataracts, glaucoma, and macular degeneration. Additionally, the rapid advancement in biotechnology has enabled the development of targeted therapies that require rigorous clinical testing. The increasing prevalence of lifestyle-induced conditions like diabetic retinopathy and chronic dry eye syndrome is also pushing manufacturers to accelerate their clinical pipelines to capture market share in these growing therapeutic categories.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Prevalence of Retinal Diseases | +2.1% | Global (High in North America) | 2025 - 2034 |
| Advancements in Gene and Cell Therapy | +1.5% | United States, Europe | 2026 - 2030 |
| Expansion of Healthcare Infrastructure in APAC | +1.2% | China, India, SE Asia | 2027 - 2034 |
| Adoption of AI and Big Data in Diagnostics | +0.8% | Global | 2025 - 2029 |
Ophthalmic Clinical Trials Market Restraints Analysis
Despite the positive growth outlook, the market faces significant restraints, most notably the high cost associated with conducting ophthalmic trials. The specialized nature of ocular assessments requires expensive imaging equipment and highly trained clinical staff, which can strain the budgets of smaller biotech firms. Furthermore, stringent regulatory requirements and the complexity of achieving statistically significant endpoints in chronic eye conditions often lead to longer trial durations and higher failure rates during Phase II and Phase III development.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Operational Costs of Ocular Trials | -1.1% | North America, Europe | 2025 - 2034 |
| Stringent Regulatory Approval Pathways | -0.9% | United States (FDA), EU (EMA) | 2025 - 2030 |
| Difficulties in Patient Recruitment | -0.7% | Global | 2025 - 2034 |
Ophthalmic Clinical Trials Market Opportunities Analysis
The shift toward personalized medicine and the development of orphan drugs for rare genetic eye disorders present substantial opportunities for growth. As our understanding of the human genome improves, tailored treatments that address the underlying genetic causes of blindness are becoming feasible. Additionally, the integration of tele-ophthalmology and home-based monitoring devices offers a way to modernize clinical trials, reaching a broader demographic and improving the quality of longitudinal data collected from trial participants.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Personalized Medicine & Pharmacogenomics | +1.4% | Europe, Japan, USA | 2028 - 2034 |
| Development of Sustained-Release Drug Delivery | +1.1% | Global | 2026 - 2032 |
| Growth in Rare Eye Disease Research | +0.9% | North America, UK | 2025 - 2034 |
Ophthalmic Clinical Trials Market Challenges Impact Analysis
One of the most pressing challenges in the ophthalmic clinical trials sector is the inherent difficulty of measuring subjective outcomes like visual acuity and quality of life, which can vary significantly between patients. Moreover, the competitive landscape for patient enrollment is intense, particularly for common conditions like AMD, where multiple trials are often vying for the same small pool of eligible participants. Ensuring global standardization of diagnostic procedures across multi-center trials also remains a technical hurdle for many CROs.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Variability in Patient-Reported Outcomes | -0.6% | Global | 2025 - 2034 |
| Site Saturation and Competition for Patients | -0.5% | United States, Western Europe | 2025 - 2028 |
| Data Security in Digital/Remote Trials | -0.3% | Global | 2026 - 2034 |
Ophthalmic Clinical Trials Market - Updated Report Scope
This report provides a comprehensive analysis of the global ophthalmic clinical trials market, covering all major trial phases, service types, and therapeutic indications. The scope includes an in-depth evaluation of the competitive landscape, regulatory frameworks, and the impact of emerging technologies like AI and blockchain on trial transparency and efficiency. It offers strategic insights for pharmaceutical companies, medical device manufacturers, and contract research organizations (CROs) looking to navigate the evolving ocular research environment between 2025 and 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.75 Billion |
| Market Forecast in 2034 | USD 3.16 Billion |
| Growth Rate | 6.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | IQVIA, LabCorp (Covance), Syneos Health, PPD (Thermo Fisher Scientific), ICON plc, Medpace, Charles River Laboratories, WuXi AppTec, Iris Pharma, Ora, Inc., Lexitas Pharma Services, Trial Runners, ProTrial Research, KCR S.A., George Clinical, Ophthalmology Clinical Trials (OCT) Design. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The ophthalmic clinical trials market is segmented based on phase, service type, indication, and end-user. Phase III trials currently dominate the market value due to the extensive resources required for late-stage clinical validation. In terms of service type, clinical trial management services hold the largest share as sponsors increasingly outsource end-to-end logistics to specialized CROs. Indication-wise, retinal disorders remain the most researched area, though dry eye disease is seeing a rapid influx of new clinical candidates. The end-user segment is led by pharmaceutical companies, followed by medical device firms focusing on innovative surgical lasers and diagnostic equipment.
- By Phase:
- Phase I (Safety and Dosage)
- Phase II (Efficacy and Side Effects)
- Phase III (Large-scale Comparative Efficacy)
- Phase IV (Post-marketing Surveillance)
- By Service Type:
- Clinical Trial Management Services
- Regulatory and Consulting Services
- Clinical Data Management and Biostatistics
- Medical Writing and Pharmacovigilance
- Site Selection and Management
- By Indication:
- Retinal Disorders (AMD, Diabetic Macular Edema)
- Glaucoma and Ocular Hypertension
- Dry Eye Disease (DED)
- Cataract and Refractive Surgery
- Uveitis and Rare Inflammatory Diseases
- Inherited Retinal Diseases (Gene Therapy)
- By End-User:
- Pharmaceutical and Biotechnology Companies
- Medical Device Manufacturers
- Academic and Government Research Institutes
Regional Highlights
- North America: The largest market globally, characterized by a high density of innovative biotech firms and a favorable regulatory environment via the FDA. The U.S. remains the primary hub for early-phase gene therapy trials.
- Europe: A significant market with a strong emphasis on academic research and stringent safety standards. The EU5 countries (Germany, UK, France, Italy, Spain) are key locations for multi-center Phase III trials.
- Asia-Pacific: The fastest-growing region, driven by countries like China and India, which offer massive patient populations and lower operational costs for late-stage trials. Government initiatives to improve healthcare infrastructure are also boosting clinical research activity.
- Latin America: Emerging as a cost-effective destination for clinical trials, particularly in Brazil and Mexico, where patient recruitment rates are relatively high for chronic conditions.
- Middle East and Africa: Growing interest in clinical research to address local prevalence of conditions like diabetic retinopathy and trachoma, with significant investment coming from the UAE and Saudi Arabia.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Ophthalmic Clinical Trials Market.- IQVIA
- LabCorp (Covance)
- Syneos Health
- PPD (Thermo Fisher Scientific)
- ICON plc
- Medpace
- Charles River Laboratories
- WuXi AppTec
- Iris Pharma
- Ora, Inc.
- Lexitas Pharma Services
- Trial Runners
- ProTrial Research
- KCR S.A.
- George Clinical
- Ophthalmology Clinical Trials (OCT) Design
- Eurofins Scientific
- SGS SA
- Clinipace
Frequently Asked Questions
What is the current market size of the Ophthalmic Clinical Trials market?
As of 2025, the market is valued at approximately USD 1.75 Billion. It is expected to grow steadily at a CAGR of 6.8%, reaching USD 3.16 Billion by 2034.
Which phase of clinical trials holds the largest market share?
Phase III trials hold the largest market share because they involve the highest number of patients, require multi-center global coordination, and involve the most extensive data collection and analysis before regulatory submission.
Why is Asia-Pacific the fastest-growing region for these trials?
The Asia-Pacific region offers a combination of large, treatment-naive patient pools, lower costs for trial execution compared to the West, and rapidly improving regulatory frameworks in countries like China and South Korea.
What are the major challenges in recruiting patients for eye trials?
Challenges include strict inclusion/exclusion criteria, patient fear of invasive ocular procedures, the need for frequent follow-up visits, and competition between multiple trials focusing on the same indications like AMD.
How is AI impacting the Ophthalmic Clinical Trials market?
AI is being used to automate the grading of retinal images, identify early-stage disease markers, and improve the speed and accuracy of diagnostic endpoints, which ultimately shortens trial timelines and reduces human error.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
