Mea Specialty Chemicals Market
Mea Specialty Chemicals Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711143 | Published On : October 12, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Mea Specialty Chemicals Market Size
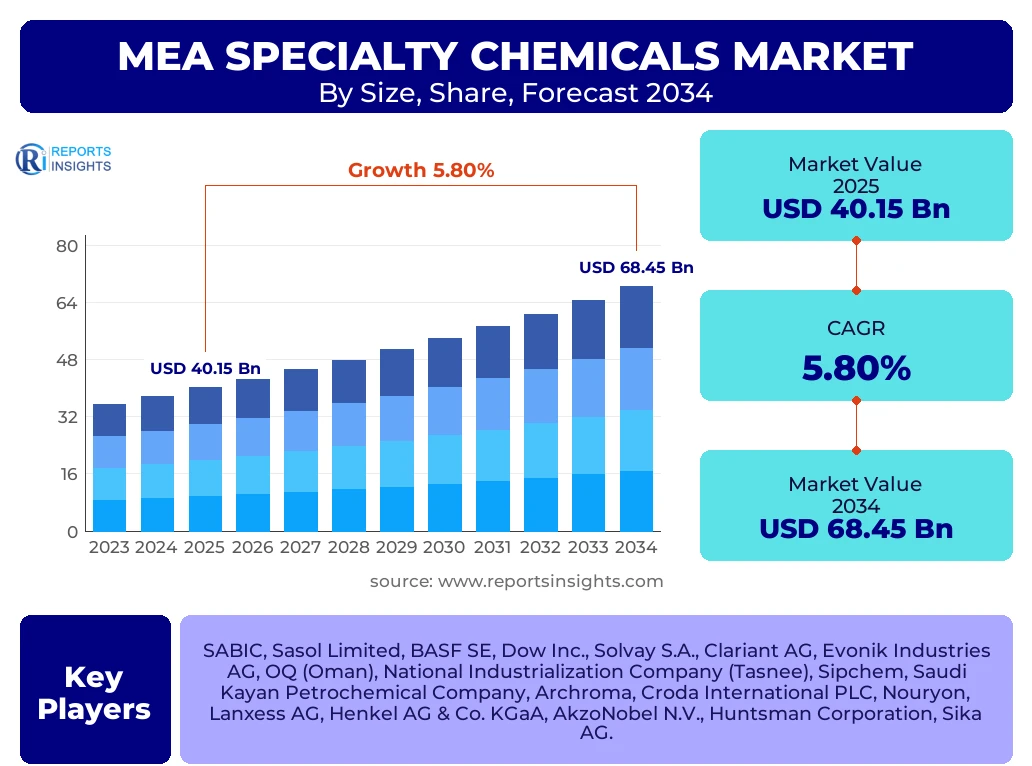
According to Reports Insights Consulting Pvt Ltd, The Mea Specialty Chemicals Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.8% between 2025 and 2034. The market is estimated at USD 42.50 Billion in 2026 and is projected to reach USD 68.45 Billion by the end of the forecast period in 2034.
Key Mea Specialty Chemicals Market Trends & Insights
The Middle East and Africa (MEA) specialty chemicals market is undergoing a profound transformation, shifting from a traditional reliance on bulk commodity exports to a high-value performance-driven sector. This evolution is primarily fueled by the strategic economic diversification plans of Gulf Cooperation Council (GCC) nations, most notably Saudi Arabia’s Vision 2030 and the UAE’s Operation 300bn. These initiatives prioritize the localization of industrial manufacturing, which in turn spikes the demand for specialized chemical inputs such as industrial catalysts, specialty polymers, and advanced lubricants. Furthermore, the region is witnessing a significant pivot toward sustainability, with major players investing in green hydrogen-based ammonia and bio-based chemicals to align with global net-zero targets. Digitalization in chemical processing and the adoption of Industry 4.0 technologies are also enhancing operational efficiencies across the regional supply chain.
- Largest Region: Saudi Arabia holds the largest market share, driven by its massive petrochemical infrastructure and aggressive industrial diversification strategies.
- Fastest Growing Region: Sub-Saharan Africa is emerging as the fastest-growing sub-region, particularly in the agrochemicals and mining chemicals sectors, supported by rising agricultural productivity and mineral extraction activities.
- Largest Segment by Share: Oilfield chemicals remain the dominant segment due to the intensive upstream and downstream oil and gas activities across the Persian Gulf and North Africa.
- Emerging Trend: Rapid expansion of the construction chemicals segment, fueled by mega-projects such as NEOM and the expansion of urban infrastructure in Egypt and the UAE.
- Sustainability Focus: Increasing adoption of water treatment chemicals due to the region's acute water scarcity and the massive scale of desalination projects.
Key Takeaways Mea Specialty Chemicals Market Size & Forecast
The MEA specialty chemicals market is characterized by a robust growth trajectory, underpinned by the convergence of industrial modernization and infrastructure development. Market participants are increasingly focusing on vertical integration to capture higher margins along the value chain. The forecast period between 2025 and 2034 suggests a steady rise in valuation as the region transitions into a global hub for specialty chemical manufacturing, reducing its historical dependence on imports from Europe and Asia. Investors are particularly eyeing the intersection of energy transition and chemical production, where carbon capture and storage (CCS) integrated chemical plants are becoming the new standard for competitiveness.
- Dominant Country: Saudi Arabia is the primary engine of growth, accounting for over 35 percent of the total MEA market value.
- Key Sector Growth: The construction chemicals sector is expected to maintain a high CAGR as the region prepares for major international events and urban expansion.
- Market Driver: Accelerated investment in the mining sectors of South Africa, DRC, and Ghana is propelling the demand for specialized processing chemicals.
- Strategic Pivot: A transition from "volume-driven" to "value-driven" manufacturing is observed among local giants like SABIC and OQ.
- Logistics Advantage: The strategic geographic positioning of the MEA region serves as a bridge between European and Asian markets, facilitating efficient trade of specialty chemical products.
Mea Specialty Chemicals Market Drivers Analysis
The growth of the MEA specialty chemicals market is largely propelled by the strategic mandates of regional governments to move away from crude oil dependency. By investing in downstream specialty segments, countries are creating a more resilient industrial base. Additionally, the rapid urbanization and population growth in Africa and parts of the Middle East necessitate advanced solutions in housing, water management, and food security, all of which are heavy consumers of specialty chemicals.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Economic Diversification Programs (Vision 2030) | +1.8% | Saudi Arabia, UAE, Kuwait | 2025-2034 |
| Infrastructure and Mega-City Projects | +1.5% | Egypt, Saudi Arabia, Qatar | 2025-2030 |
| Technological Advancements in Oil Recovery | +1.2% | UAE, Iraq, Nigeria | 2025-2034 |
| Expansion of Mining Activities | +0.9% | South Africa, Ghana, DRC | 2026-2034 |
Mea Specialty Chemicals Market Restraints Analysis
Despite the positive outlook, the market faces significant headwinds including geopolitical instability and the high volatility of raw material prices which are often linked to global energy markets. Regulatory complexities across different jurisdictions and the high cost of establishing advanced R&D facilities in the region also act as deterrents for some international players. Furthermore, the reliance on skilled expatriate labor in certain high-tech chemical segments remains a challenge for full-scale localization.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Geopolitical Tensions and Supply Chain Risks | -0.7% | Levant Region, Libya, Yemen | 2025-2034 |
| Fluctuating Feedstock Prices | -0.5% | Entire MEA Region | 2025-2028 |
| Stringent Environmental Regulations (Export Market Alignment) | -0.4% | GCC Countries | 2027-2034 |
Mea Specialty Chemicals Market Opportunities Analysis
The shift toward sustainable and green chemistry presents the most significant opportunity for the MEA region. Given the abundant solar energy resources, there is a massive potential for producing green hydrogen, which can be used to manufacture green ammonia and other sustainable chemicals. Additionally, the burgeoning pharmaceutical and cosmetic industries in the Middle East are creating a new demand frontier for high-purity specialty ingredients and active pharmaceutical ingredients (APIs).
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Green Hydrogen and Bio-based Chemicals | +2.1% | Oman, UAE, Morocco | 2028-2034 |
| Growth in Water Desalination and Treatment | +1.4% | Saudi Arabia, Israel, Jordan | 2025-2034 |
| Expansion of Cosmetic and Personal Care Manufacturing | +1.1% | Turkey, UAE, South Africa | 2026-2034 |
Mea Specialty Chemicals Market Challenges Impact Analysis
One of the primary challenges is the competitive pressure from Asian chemical manufacturers, particularly from China and India, who often benefit from economies of scale and lower production costs. Additionally, the MEA region must navigate the "Double Transition"—the dual challenge of digitalizing chemical plants while simultaneously decarbonizing production processes to meet international trade requirements like the EU's Carbon Border Adjustment Mechanism (CBAM).
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Competition from Low-Cost Asian Imports | -0.8% | East Africa, GCC | 2025-2034 |
| Shortage of Specialized Local R&D Talent | -0.6% | Saudi Arabia, UAE, Qatar | 2025-2030 |
| Compliance with International Carbon Standards (CBAM) | -0.5% | Exporters to Europe (North Africa/GCC) | 2026-2034 |
Mea Specialty Chemicals Market - Updated Report Scope
This report provides an exhaustive analysis of the MEA specialty chemicals market, covering over 20 product categories and their applications across 15+ end-use industries. It provides granular data on regional production capacities, trade flows, and the strategic positioning of both regional champions and multinational corporations. The scope includes a detailed forecast of the market's transition toward specialty segments such as electronic chemicals, flavors and fragrances, and high-performance polymers, reflecting the latest shifts in consumer behavior and industrial requirements.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 40.15 Billion |
| Market Forecast in 2034 | USD 68.45 Billion |
| Growth Rate | 5.8% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | SABIC, Sasol Limited, BASF SE, Dow Inc., Solvay S.A., Clariant AG, Evonik Industries AG, OQ (Oman), National Industrialization Company (Tasnee), Sipchem, Saudi Kayan Petrochemical Company, Archroma, Croda International PLC, Nouryon, Lanxess AG, Henkel AG & Co. KGaA, AkzoNobel N.V., Huntsman Corporation, Sika AG. |
| Regions Covered | Middle East (Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain, Turkey, Israel, Rest of Middle East), Africa (South Africa, Nigeria, Egypt, Algeria, Morocco, Rest of Africa). |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The MEA specialty chemicals market is segmented primarily by product type and end-user industry. The oilfield chemicals segment currently dominates the market, supported by the extensive oil extraction activities in the Persian Gulf and North Africa. However, the construction chemicals segment is exhibiting the highest growth rate due to massive investments in residential and commercial infrastructure. The agrochemicals segment is also critical, particularly in the African continent, as countries strive for food self-sufficiency through modern agricultural practices.
- Oilfield Chemicals: Includes corrosion inhibitors, scale inhibitors, biocides, and surfactants used in upstream and midstream operations.
- Construction Chemicals: Comprises concrete admixtures, flooring chemicals, waterproofing compounds, and repair and rehabilitation chemicals for urban mega-projects.
- Water Treatment Chemicals: Encompasses coagulants, flocculants, disinfectants, and anti-scalants, essential for the region's desalination plants.
- Agrochemicals: Focuses on advanced pesticides, herbicides, and specialty fertilizers tailored for arid and semi-arid climates.
- Specialty Polymers: High-performance materials used in automotive parts, electronics, and durable consumer goods.
- Industrial & Institutional (I&I) Cleaners: Driven by the expanding hospitality, healthcare, and commercial sectors across the Middle East.
Regional Highlights
- Saudi Arabia: The largest market in the region, fueled by the Saudi Vision 2030 and the expansion of the Jubail and Yanbu industrial cities.
- United Arab Emirates (UAE): A major hub for specialty chemical trade and distribution, with a growing focus on high-end specialty polymers and construction chemicals.
- South Africa: The leading market in Sub-Saharan Africa, with a strong emphasis on mining chemicals and industrial cleaning solutions.
- Egypt: Emerging as a major manufacturing base for construction chemicals and agrochemicals, supported by recent industrial reforms and infrastructure growth.
- Nigeria: Significant potential in oilfield chemicals and consumer-focused specialty chemicals due to its large population and oil reserves.
- Turkey: A bridge between Europe and Asia, boasting a diverse specialty chemical sector with strengths in textile, automotive, and coating chemicals.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Mea Specialty Chemicals Market.- SABIC (Saudi Basic Industries Corporation)
- Sasol Limited
- BASF SE
- Dow Inc.
- Solvay S.A.
- Clariant AG
- Evonik Industries AG
- OQ (Oman)
- National Industrialization Company (Tasnee)
- Sipchem (Sahara International Petrochemical Company)
- Saudi Kayan Petrochemical Company
- Archroma
- Croda International PLC
- Nouryon
- Lanxess AG
- Henkel AG & Co. KGaA
- AkzoNobel N.V.
- Huntsman Corporation
- Sika AG
- Halliburton (Specialty Chemicals Division)
Frequently Asked Questions
What is the current market size of the MEA Specialty Chemicals market?
The MEA specialty chemicals market is estimated to be valued at approximately USD 40.15 Billion in 2025 and is expected to grow significantly over the forecast period reaching USD 68.45 Billion by 2034.
Which country is leading the growth in the MEA region?
Saudi Arabia is the leading country in the region, driven by its extensive industrial diversification initiatives and its role as a global petrochemical powerhouse.
What are the primary drivers for the construction chemicals segment in the MEA?
The primary drivers include massive government-led infrastructure projects such as Saudi Arabia's NEOM, the expansion of Cairo's administrative capital, and the ongoing urban development in the UAE and Qatar.
How is the "Green Initiative" affecting the regional chemical market?
The green initiative is prompting companies to invest in renewable energy-powered chemical production, green hydrogen, and sustainable water treatment solutions, aligning regional exports with global environmental standards.
What is the expected CAGR for the MEA Specialty Chemicals market from 2025 to 2034?
The market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.8% during the forecast period of 2025 to 2034.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
