Rubber Processing Chemicals Market
Rubber Processing Chemicals Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711252 | Published On : October 22, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Rubber Processing Chemicals Market Size
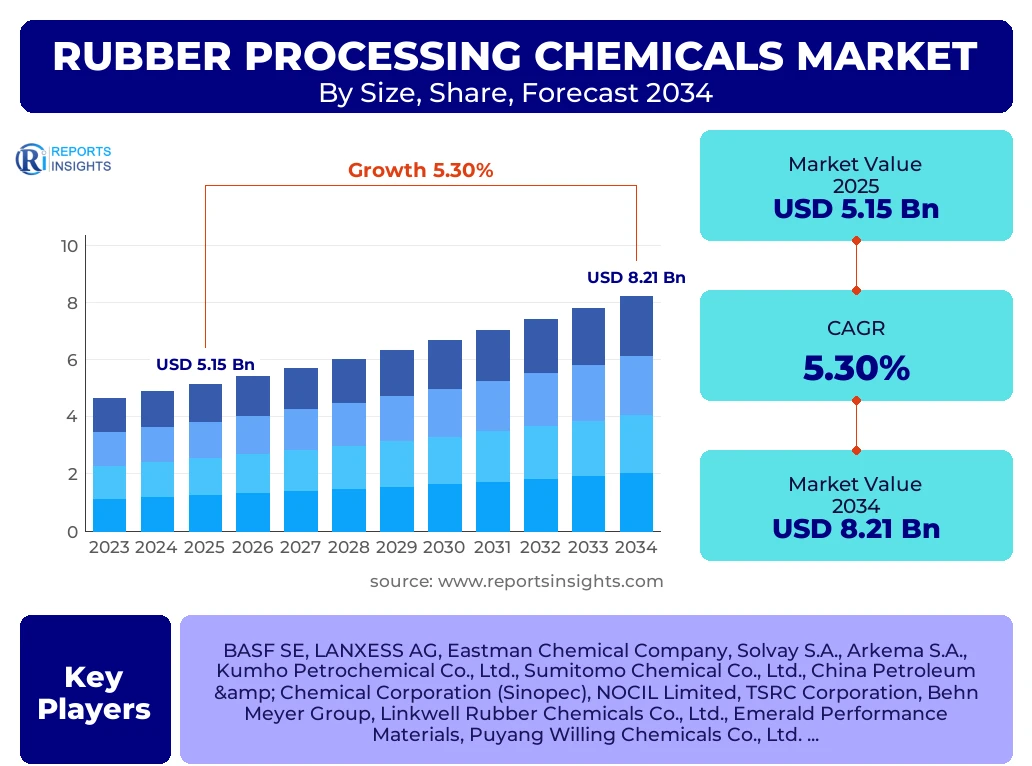
According to Reports Insights Consulting Pvt Ltd, The Rubber Processing Chemicals Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.3% between 2025 and 2034. The market is estimated at USD 5.42 Billion in 2026 and is projected to reach USD 8.21 Billion by the end of the forecast period in 2034.
The global rubber processing chemicals sector is undergoing a significant transformation driven by the escalating demand from the automotive industry and the industrial manufacturing sector. These chemicals, which include accelerators, antioxidants, and vulcanizing agents, are essential for enhancing the physical properties of rubber, such as durability, heat resistance, and elasticity. The shift toward high-performance tires and the increasing adoption of electric vehicles (EVs) are necessitating advanced chemical formulations that can withstand higher torque and provide lower rolling resistance. This technological evolution is a primary catalyst for market expansion during the forecast period.
Furthermore, the market is characterized by a strategic pivot toward sustainable and bio-based chemical solutions. Regulatory pressures across Europe and North America regarding the environmental impact of traditional rubber chemicals are pushing manufacturers to innovate. As a result, the integration of green chemistry and the development of eco-friendly processing aids are becoming central to competitive strategies. The robust industrialization in emerging economies, particularly in the Asia-Pacific region, continues to provide a fertile ground for market growth, supported by favorable government policies and infrastructure development projects.
Key Rubber Processing Chemicals Market Trends & Insights
The Rubber Processing Chemicals market is increasingly influenced by the intersection of material science and environmental sustainability. Stakeholders are focusing on the development of non-toxic and non-carcinogenic accelerators to comply with international safety standards such as REACH and EPA guidelines. Competitive benchmarking reveals that leading companies are investing heavily in Research and Development (R&D) to differentiate their product portfolios through specialty chemicals that improve the longevity of synthetic rubber products used in extreme conditions. The rise of automation in chemical processing is also enhancing production efficiency and consistency.
- Largest Region: Asia-Pacific remains the dominant force in the market, accounting for over 50% of the total market share, driven by massive tire production hubs in China, India, and Southeast Asia.
- Fastest Growing Region: The Asia-Pacific region is also the fastest-growing market, supported by rapid urbanization and the expansion of the regional automotive manufacturing base.
- Largest Product Segment: Antidegradants represent the largest segment by share, as they are critical in preventing the degradation of rubber products exposed to oxygen, ozone, and heat.
- Emerging Trend: The growing demand for specialty rubber chemicals in the production of Electric Vehicle (EV) tires, which require specific properties like high load-bearing capacity and noise reduction.
- Regulatory Influence: Increasing stringency in environmental regulations is driving the phase-out of certain sulfenamide accelerators and secondary amines in favor of safer alternatives.
Key Takeaways Rubber Processing Chemicals Market Size & Forecast
The comprehensive analysis of the rubber processing chemicals market indicates a resilient growth trajectory despite macroeconomic fluctuations. The tire industry remains the primary consumer, accounting for approximately 70% of the market volume. Forecasts suggest that the integration of digital twins and AI in chemical manufacturing will optimize yield and reduce waste, further bolstering the market's economic viability. Key takeaways emphasize that market leaders are focusing on strategic acquisitions and partnerships to secure raw material supply chains and expand their geographic footprint in high-growth corridors.
- Tire Dominance: The tire application segment will continue to lead the market, with a projected CAGR of 5.5% as global vehicle production recovers and replacement cycles shorten.
- Sustainability Focus: Bio-based rubber chemicals are expected to witness a surge in demand, reflecting the broader industry trend toward carbon neutrality.
- Strategic Hubs: China and India are identified as the most critical growth engines, with domestic capacity expansions and favorable export-import dynamics.
- Market Maturity: North American and European markets are reaching maturity, focusing more on high-value specialty chemicals and circular economy initiatives rather than volume growth.
- Innovation Frontier: The development of multi-functional additives that combine acceleration and protection properties is a key area of focus for next-generation chemical suppliers.
Rubber Processing Chemicals Market Drivers Analysis
The market is primarily driven by the systemic growth of the global automotive industry and the increasing requirement for high-performance elastomers in industrial applications. As the complexity of rubber formulations increases to meet modern safety and durability standards, the reliance on specialized processing chemicals becomes indispensable.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Automotive Production and EV Transition | +1.8% | Global (Strongest in APAC and Europe) | 2025 - 2034 |
| Infrastructure Development and Construction Activity | +1.2% | India, China, Middle East | 2025 - 2030 |
| Advancements in Green Tire Technology | +0.9% | North America, Germany, Japan | 2026 - 2034 |
| Expansion of the Aerospace and Defense Sectors | +0.5% | United States, France | 2027 - 2034 |
Rubber Processing Chemicals Market Restraints Analysis
Environmental concerns and stringent regulatory frameworks pose significant hurdles for the market. The high cost of R&D for developing compliant alternatives and the volatility of petrochemical-based raw material prices often squeeze the profit margins of manufacturers.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Environmental and Health Regulations (REACH) | -0.8% | European Union, North America | 2025 - 2034 |
| Fluctuations in Crude Oil and Petrochemical Prices | -0.6% | Global | 2025 - 2030 |
| Trade Barriers and Geopolitical Tensions | -0.4% | United States, China | 2025 - 2028 |
Rubber Processing Chemicals Market Opportunities Analysis
Opportunities lie in the development of sustainable chemical pathways and the expansion into niche applications such as medical-grade rubber and high-precision electronic components. The shift toward circularity in the rubber industry presents a unique opening for chemicals that facilitate rubber recycling.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Bio-derived Processing Aids | +1.1% | Western Europe, United States | 2026 - 2034 |
| Growth in Demand for Non-Tire Industrial Rubber | +0.7% | Southeast Asia, Latin America | 2025 - 2034 |
| Technological Integration in Rubber Recycling | +0.5% | Global | 2028 - 2034 |
Rubber Processing Chemicals Market Challenges Impact Analysis
Maintaining product consistency across global supply chains while adhering to varying regional safety standards remains a core challenge. Additionally, the phase-out of traditional, low-cost chemicals requires massive capital reinvestment in new manufacturing processes.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Disruptions for Key Intermediates | -0.5% | Global | 2025 - 2027 |
| High Capital Investment for Sustainable Transition | -0.4% | Medium and Small Enterprises | 2025 - 2030 |
Rubber Processing Chemicals Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the global rubber processing chemicals market, covering technical specifications, market dynamics, and a competitive landscape assessment. It provides granular insights into chemical types, specific rubber applications, and regional consumption patterns to assist stakeholders in making data-driven investment decisions.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 5.15 Billion |
| Market Forecast in 2034 | USD 8.21 Billion |
| Growth Rate | 5.3% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | BASF SE, LANXESS AG, Eastman Chemical Company, Solvay S.A., Arkema S.A., Kumho Petrochemical Co., Ltd., Sumitomo Chemical Co., Ltd., China Petroleum & Chemical Corporation (Sinopec), NOCIL Limited, TSRC Corporation, Behn Meyer Group, Linkwell Rubber Chemicals Co., Ltd., Emerald Performance Materials, Puyang Willing Chemicals Co., Ltd., Shandong Yanggu Huatai Chemical Co., Ltd., General Quimica S.A.U., StairRich, Flexsys (One Rock Capital Partners) |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The global rubber processing chemicals market is segmented based on product type, application, and rubber type. The segmentation allows for a deeper understanding of the diverse requirements across various industries, from high-volume automotive manufacturing to specialized medical device production. Antidegradants and accelerators remain the dominant product segments due to their indispensable role in the vulcanization and protection of rubber matrices. The tire industry continues to be the largest application segment, while the non-tire segment is gaining traction in industrial and consumer goods sectors.
- By Type:
- Accelerators: Including Sulfenamides, Thiazoles, Guanidines, and Thiurams.
- Antidegradants: Including Antioxidants and Antiozonants.
- Vulcanizing Agents: Sulfur-based and Non-sulfur based systems.
- Processing Aids: Plasticizers, Peptizers, and Fatty Acids.
- Others: Flame Retardants, Blowing Agents, and Colorants.
- By Application:
- Tire: Covering Passenger Cars, LCVs, HCVs, and OTR tires.
- Non-Tire: Including Belts & Hoses, Gaskets & Seals, Footwear, Wire & Cable insulation, and Healthcare products.
- By Rubber Type:
- Natural Rubber: High demand in heavy-duty truck tires and medical gloves.
- Synthetic Rubber: Dominating the automotive passenger car segment and industrial hoses.
Regional Highlights
The regional analysis showcases the diverse market conditions across the globe. Asia-Pacific stands out as the epicenter of growth, while Western markets are focusing on sustainability and high-performance niche segments.
- Asia-Pacific: The largest and fastest-growing region. China leads in production volume, while India is witnessing rapid growth due to increasing domestic vehicle ownership and government support for manufacturing. Southeast Asian countries like Thailand and Indonesia are major hubs for both natural rubber production and tire manufacturing.
- North America: A mature market characterized by the presence of major tire manufacturers and a strong focus on innovative chemical solutions for the EV sector. The United States is the primary contributor to growth in this region.
- Europe: This region is at the forefront of regulatory compliance and the development of sustainable rubber chemicals. Germany, France, and Italy are key markets where high-performance automotive parts drive the demand for specialized chemicals.
- Latin America: Growth is driven by the recovery of the automotive industry in Brazil and Mexico, alongside the expansion of the mining and industrial sectors.
- Middle East & Africa: Although a smaller market share, the region is seeing increased investment in petrochemical infrastructure, which supports the local production of rubber chemicals.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Rubber Processing Chemicals Market. The competitive landscape is marked by strategic mergers, capacity expansions, and a heavy emphasis on sustainable R&D. The following companies are the major contributors to the market's technological and economic landscape.
- BASF SE
- LANXESS AG
- Eastman Chemical Company
- Solvay S.A.
- Arkema S.A.
- Kumho Petrochemical Co., Ltd.
- Sumitomo Chemical Co., Ltd.
- China Petroleum & Chemical Corporation (Sinopec)
- NOCIL Limited
- TSRC Corporation
- Behn Meyer Group
- Linkwell Rubber Chemicals Co., Ltd.
- Emerald Performance Materials
- Puyang Willing Chemicals Co., Ltd.
- Shandong Yanggu Huatai Chemical Co., Ltd.
- General Quimica S.A.U.
- StairRich
- Flexsys (One Rock Capital Partners)
- Sennics Co., Ltd.
- Agrofert (Duslo)
Frequently Asked Questions
What are the primary types of rubber processing chemicals used today?
The primary types include accelerators, which speed up the vulcanization process; antidegradants (antioxidants and antiozonants), which protect rubber from environmental factors; and vulcanizing agents like sulfur. Other chemicals include processing aids, plasticizers, and blowing agents.
Which industry is the largest consumer of rubber processing chemicals?
The tire industry is the largest consumer, accounting for approximately 70% of the total market volume. This includes tires for passenger cars, commercial vehicles, and off-the-road (OTR) machinery.
How are environmental regulations affecting the market?
Environmental regulations such as REACH in Europe and similar standards in North America are forcing the phase-out of hazardous chemicals. This is driving innovation in non-toxic, eco-friendly, and bio-based rubber processing chemicals.
What is the projected growth rate of the market through 2034?
The market is projected to grow at a Compound Annual Growth Rate (CAGR) of approximately 5.3% from 2025 to 2034, reaching a value of over USD 8.2 Billion by the end of the forecast period.
Why is the Asia-Pacific region dominant in this market?
Asia-Pacific dominates due to the concentration of global tire manufacturing in China, India, and Southeast Asia. Additionally, the region has abundant natural rubber resources and a rapidly expanding automotive sector.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
