Gypsum Board Market
Gypsum Board Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710988 | Published On : September 25, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Gypsum Board Market Size
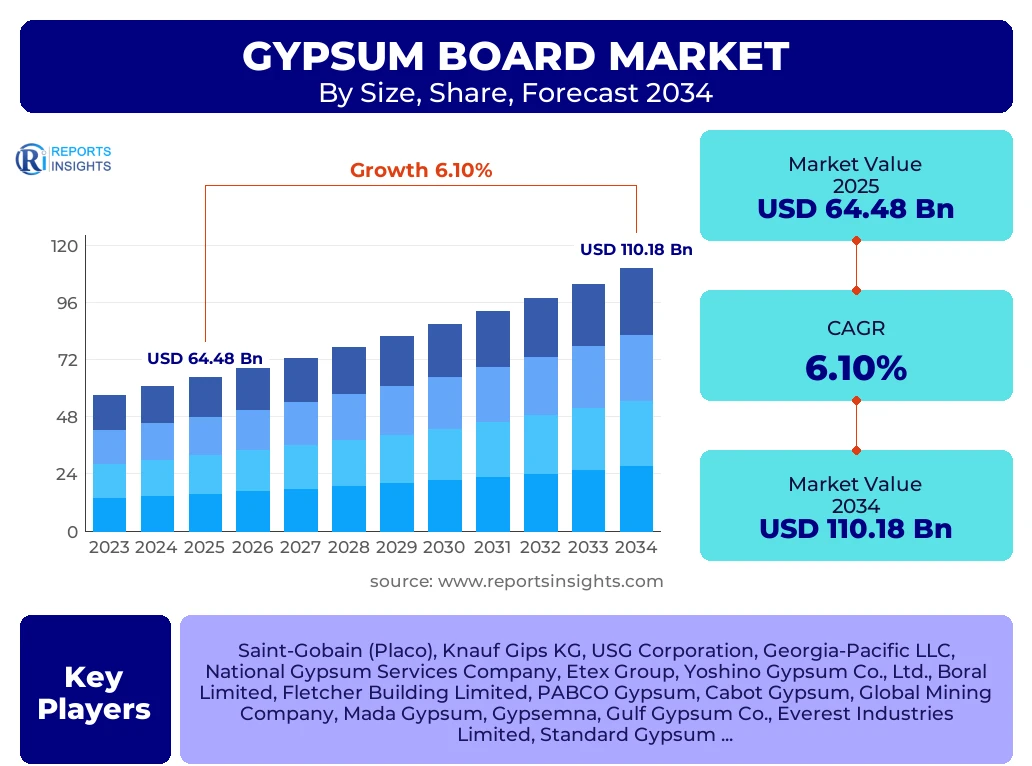
According to Reports Insights Consulting Pvt Ltd, The Gypsum Board Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.1% between 2026 and 2034. The market is estimated at USD 68.42 Billion in 2026 and is projected to reach USD 110.18 Billion by the end of the forecast period in 2034.
Key Gypsum Board Market Trends & Insights
The global gypsum board market is currently undergoing a significant transformation driven by the rapid evolution of construction technologies and a global shift toward sustainable building materials. Market analysis indicates a rising preference for lightweight, fire-resistant, and sound-insulating materials in both residential and commercial sectors. Modern architectural designs are increasingly utilizing specialized gypsum products, such as moisture-resistant and high-impact boards, to enhance building longevity and occupant safety. Furthermore, the integration of recycled gypsum and the development of synthetic gypsum from flue-gas desulfurization (FGD) processes are reshaping the supply chain, aligning the industry with circular economy principles and stringent environmental regulations.
- Largest Region: Asia-Pacific currently holds the largest market share, driven by massive urbanization projects in China and India.
- Fastest Growing Region: Middle East and Africa (MEA) is projected to be the fastest-growing region due to large-scale infrastructure projects like Saudi Arabia’s Vision 2030.
- Leading Product Segment: Wallboard remains the largest segment by product type, accounting for over 50% of the total market volume.
- Dominant End-Use: The residential sector continues to lead in terms of value, fueled by the global housing demand and home renovation trends.
- Material Innovation: Increasing adoption of glass-mat gypsum boards for exterior applications is a major emerging trend in mature markets.
Key Takeaways Gypsum Board Market Size & Forecast
The market trajectory for gypsum boards remains robust, underpinned by the structural shift from traditional wet construction methods (brick and mortar) to dry construction techniques. This transition is motivated by the need for shorter construction timelines, reduced labor costs, and improved aesthetic flexibility. Forecasts indicate that the market will benefit from the expansion of institutional infrastructure, including hospitals and schools, where acoustic performance and fire safety are non-negotiable. Additionally, the growing popularity of modular and prefabricated construction is acting as a force multiplier for gypsum board consumption globally.
- The global market value is set to exceed USD 110 billion by 2034, reflecting steady demand across all geographic tiers.
- North America and Europe are witnessing high demand for specialized performance boards, particularly those with VOC-absorption capabilities.
- China remains the single largest national market, contributing significantly to the volume of gypsum board production and consumption.
- Technological advancements in manufacturing are allowing for thinner yet stronger boards, optimizing logistics and installation efficiency.
- Strategic mergers and acquisitions among key players are consolidating the market, enabling broader distribution networks and R&D synergy.
Gypsum Board Market Drivers Analysis
The primary driver for the gypsum board market is the unprecedented rate of global urbanization, particularly in emerging economies where residential and commercial construction is peaking. Governments are implementing stricter building codes regarding fire safety and energy efficiency, which naturally favors the use of gypsum-based systems. Additionally, the rising cost of manual labor in developed nations is pushing developers toward dry-wall systems that allow for rapid installation with minimal on-site waste.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Global Urbanization & Housing Demand | +2.1% | India, China, Southeast Asia | 2025 - 2034 |
| Adoption of Rapid Drywall Construction | +1.5% | USA, Germany, UK | 2025 - 2030 |
| Stringent Fire Safety Regulations | +1.2% | European Union, GCC Countries | 2026 - 2034 |
| Expansion of Institutional Infrastructure | +1.3% | Global | 2025 - 2034 |
Gypsum Board Market Restraints Analysis
Despite growth, the market faces significant hurdles related to the availability and price volatility of raw materials. While synthetic gypsum is widely used, the global shift away from coal-fired power plants (the primary source of FGD gypsum) is creating long-term supply concerns. Furthermore, the heavyweight nature of the product makes it highly sensitive to fluctuations in transportation and fuel costs, often limiting the economic radius of manufacturing facilities.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Fluctuating Raw Material Prices | -0.8% | North America, Europe | Ongoing |
| Logistical & Transportation Costs | -0.6% | Global | 2025 - 2034 |
| Environmental Impact of Natural Mining | -0.4% | Brazil, India | 2027 - 2034 |
Gypsum Board Market Opportunities Analysis
The green building movement presents the most substantial opportunity for the gypsum board industry. Products that contribute to LEED or BREEAM certifications are seeing higher margins and faster adoption. There is also a significant untapped market in the renovation and remodeling sector of aging urban centers in North America and Europe, where gypsum boards are used to improve thermal and acoustic insulation without major structural overhauls.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Demand for Sustainable & Recycled Products | +1.8% | Western Europe, Scandinavia | 2025 - 2034 |
| Renovation & Interior Refurbishment Trends | +1.4% | USA, Japan | 2026 - 2034 |
| Advancements in Modular Construction | +1.1% | Australia, South Korea | 2025 - 2030 |
Gypsum Board Market Challenges Impact Analysis
The industry must navigate the challenge of product substitution, where alternative materials like fiber cement boards or plywood are used in specific moisture-heavy or external environments. Additionally, waste management remains a critical issue, as gypsum board waste in landfills can produce toxic gases if not handled correctly, leading to increased regulatory pressure on disposal and recycling mandates.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Competition from Substitute Materials | -0.5% | Southeast Asia, Latin America | 2025 - 2034 |
| Waste Disposal Regulations | -0.4% | United Kingdom, Canada | 2026 - 2034 |
Gypsum Board Market - Updated Report Scope
This report provides a comprehensive examination of the global gypsum board industry, covering technological innovations, regulatory landscapes, and competitive dynamics. It includes granular data on production volumes, consumption patterns, and pricing trends across six major geographic regions and over 20 key countries. The scope extends to a detailed analysis of the supply chain, from raw gypsum extraction to final end-user applications in various building types.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 64.48 Billion |
| Market Forecast in 2034 | USD 110.18 Billion |
| Growth Rate | 6.1% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Saint-Gobain (Placo), Knauf Gips KG, USG Corporation, Georgia-Pacific LLC, National Gypsum Services Company, Etex Group, Yoshino Gypsum Co., Ltd., Boral Limited, Fletcher Building Limited, PABCO Gypsum, Cabot Gypsum, Global Mining Company, Mada Gypsum, Gypsemna, Gulf Gypsum Co., Everest Industries Limited, Standard Gypsum, Shandong Taihe Dongxin Co., Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The gypsum board market is segmented primarily by product type, board characteristics, and end-use applications, reflecting the diverse needs of the global construction industry. Performance-based boards, such as those designed for fire resistance and acoustic dampening, are seeing the highest growth rates due to modern building codes. The segmentation also highlights the difference between residential and non-residential applications, with residential demand being more susceptible to interest rate changes and housing starts, while commercial demand is driven by corporate infrastructure and retail expansion.
- By Product Type:
- Wallboard: The primary segment used for internal partitioning and lining.
- Ceiling Board: Specialized lightweight boards designed to prevent sagging in overhead applications.
- Pre-decorated Board: Boards that come with factory-applied finishes to reduce on-site labor.
- By Type (Functionality):
- Regular: Standard boards for general applications.
- Fire-resistant: Enhanced with glass fibers and additives for high-temperature performance.
- Moisture-resistant: Treated with wax or silicone for use in kitchens and bathrooms.
- Impact-resistant: Reinforced for high-traffic areas like schools and hospitals.
- By End-Use:
- Residential: Includes single-family homes and multi-family apartments.
- Commercial: Offices, retail spaces, and hotels.
- Institutional: Educational facilities and healthcare centers.
- Industrial: Warehouses and manufacturing units.
Regional Highlights
- Asia-Pacific: The regional powerhouse, led by China, which accounts for nearly 40% of global production. India is emerging as a critical growth hub due to massive government-led housing initiatives.
- North America: A mature market where the focus is on high-performance boards and sustainable manufacturing. The US market is characterized by high penetration of drywall systems in residential construction.
- Europe: Driven by strict energy efficiency standards (Green Deal) and a strong culture of interior renovation. Germany, France, and the UK are the leading consumers.
- Middle East & Africa: Rapidly expanding due to tourism-related infrastructure and luxury residential projects in the GCC region.
- Latin America: Brazil and Mexico are the primary markets, with growth linked to stabilizing economic conditions and urban development.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Gypsum Board Market.- Saint-Gobain (France)
- Knauf Gips KG (Germany)
- USG Corporation (United States)
- Georgia-Pacific LLC (United States)
- National Gypsum Services Company (United States)
- Etex Group (Belgium)
- Yoshino Gypsum Co., Ltd. (Japan)
- Boral Limited (Australia)
- Fletcher Building Limited (New Zealand)
- PABCO Gypsum (United States)
- Cabot Gypsum (Canada)
- Global Mining Company (Oman)
- Mada Gypsum (Saudi Arabia)
- Gypsemna (UAE)
- Gulf Gypsum Co. (Qatar)
- Everest Industries Limited (India)
- Standard Gypsum (United States)
- Shandong Taihe Dongxin Co., Ltd. (China)
Frequently Asked Questions
What is the current market size of the global Gypsum Board industry?
The global gypsum board market is estimated to be valued at approximately USD 68.42 Billion in 2026, with projections indicating it will reach USD 110.18 Billion by 2034.
Which region is expected to grow the fastest in the Gypsum Board market?
The Middle East and Africa (MEA) region is expected to exhibit the highest growth rate due to massive investment in infrastructure and economic diversification projects.
What are the primary drivers for Gypsum Board adoption?
Key drivers include rapid urbanization, the shift toward dry construction to save time and labor, and stringent building regulations regarding fire safety and acoustic insulation.
What are the different types of gypsum boards available?
Common types include regular wallboard, fire-resistant boards (Type X), moisture-resistant boards (Greenboard), impact-resistant boards, and specialized ceiling boards.
How is the industry addressing environmental sustainability?
The industry is increasingly using synthetic gypsum (FGD gypsum), implementing board-to-board recycling programs, and developing low-carbon manufacturing processes to meet global sustainability targets.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted