Emulsion Polymer Market
Emulsion Polymer Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711107 | Published On : October 08, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Emulsion Polymer Market Size
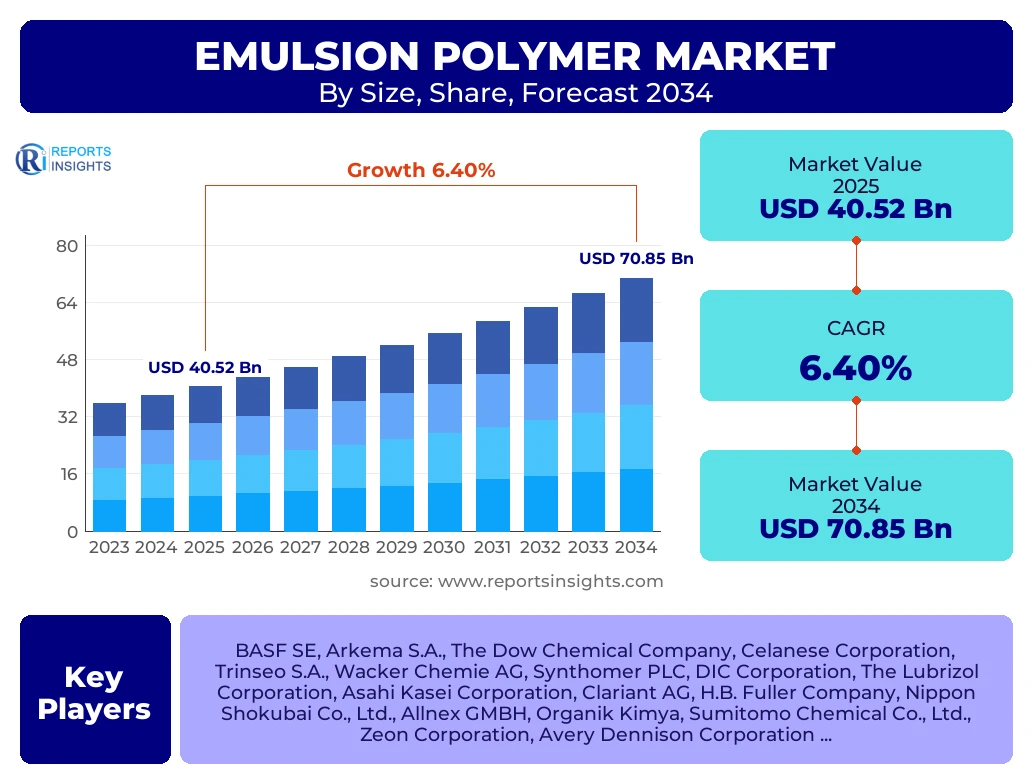
According to Reports Insights Consulting Pvt Ltd, The Emulsion Polymer Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.4% between 2025 and 2034. The market is estimated at USD 43.12 Billion in 2026 and is projected to reach USD 70.85 Billion by the end of the forecast period in 2034.
Key Emulsion Polymer Market Trends & Insights
The global emulsion polymer market is undergoing a significant transformation driven by the transition from solvent-borne to water-borne systems, primarily due to stringent environmental regulations regarding Volatile Organic Compounds (VOCs). Stakeholders are increasingly focusing on sustainable chemistry, leading to the development of bio-based emulsion polymers derived from renewable feedstocks. The Asia-Pacific region continues to dominate the landscape, fueled by rapid urbanization and infrastructure development, while North America and Europe are witnessing a surge in high-performance specialty emulsions for automotive and industrial coatings. Competitive benchmarking indicates that leading companies are prioritizing R&D in nanostructured emulsions and self-crosslinking technologies to enhance durability and chemical resistance in end-use applications.
- Asia-Pacific is the largest and fastest-growing region, accounting for over 45% of the total market share due to burgeoning construction and automotive sectors in China and India.
- The Acrylics segment remains the largest product type, driven by its versatile application in architectural coatings and adhesives.
- Paints and Coatings represent the largest application segment, supported by the global shift toward eco-friendly and low-odor interior decorative paints.
- Increased adoption of emulsion polymers in the non-woven textile industry for hygiene and medical products is emerging as a critical growth frontier.
- Advancements in controlled radical polymerization (CRP) are allowing manufacturers to produce polymers with precise molecular weights and architectures.
Key Takeaways Emulsion Polymer Market Size & Forecast
The market trajectory for emulsion polymers is characterized by steady expansion across diverse industrial verticals, with the forecast period highlighting a robust recovery in the construction sector and a surge in packaging demand. Investors and market participants are closely monitoring the volatility of raw material prices, such as acrylic acid, styrene, and butadiene, which directly impact profit margins. The integration of digital twins and AI-driven molecular modeling is streamlining the development of customized emulsion formulations, significantly reducing time-to-market for new products. Furthermore, the push for circular economy initiatives is encouraging the recycling of emulsion-based products, particularly in paper and board applications.
- China and India are the leading countries in terms of production capacity and consumption, with massive government investments in smart city projects.
- The transition toward REACH-compliant and APEO-free surfactants is now a standard requirement in Western markets, influencing global supply chain dynamics.
- The adhesives and sealants segment is expected to witness the highest CAGR within the application category, particularly in the automotive lightweighting sector.
- Styrene-butadiene latex demand remains concentrated in the paper coating and carpet backing industries, although it faces competition from synthetic alternatives.
- Strategic mergers and acquisitions are being utilized by top-tier players to acquire specialized technology in pressure-sensitive adhesives (PSA) and high-performance elastomers.
Emulsion Polymer Market Drivers Analysis
The growth of the emulsion polymer market is primarily propelled by the rigorous implementation of environmental safety standards and the rising demand for high-performance architectural coatings. As global populations migrate to urban centers, the demand for residential and commercial infrastructure necessitates large volumes of paints, adhesives, and sealants that utilize emulsion polymer technology. Additionally, the automotive industry's shift toward water-based coatings to meet sustainability goals provides a significant tailwind for specialized polymer dispersions.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shift from Solvent-borne to Water-borne Systems | +1.8% | Global (High in EU and NA) | 2025 - 2034 |
| Rapid Urbanization in Emerging Economies | +1.5% | China, India, Southeast Asia | 2025 - 2030 |
| Demand for Eco-friendly Paints and Coatings | +1.2% | North America, Western Europe | 2026 - 2034 |
| Growth in Flexible Packaging Sector | +0.9% | Global | 2025 - 2034 |
Emulsion Polymer Market Restraints Analysis
Despite the positive outlook, the market faces challenges related to the fluctuation of petrochemical feedstock prices and the logistical complexities of transporting liquid dispersions. The dependency on crude oil derivatives makes the market sensitive to geopolitical tensions and supply chain disruptions. Furthermore, the technical limitations of water-based systems in extreme weather conditions, such as slow drying times in high humidity, remain a bottleneck for certain industrial applications.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Volatility in Raw Material Prices (Styrene, Butadiene) | -0.7% | Global | 2025 - 2034 |
| Stringent Regulatory Approvals for New Monomers | -0.5% | Europe (ECHA/REACH) | 2025 - 2028 |
| High Transportation and Storage Costs | -0.4% | North America, APAC | 2026 - 2034 |
Emulsion Polymer Market Opportunities Analysis
The development of bio-based monomers and the integration of nanotechnology into emulsion polymerization present lucrative opportunities for market expansion. The rising popularity of bio-derived acrylic acid and succinic acid allows manufacturers to produce "green" emulsions that appeal to environmentally conscious consumers. Additionally, the expansion of the e-commerce sector is driving the demand for pressure-sensitive adhesives used in labeling and packaging, creating a new growth avenue for specialized polymer dispersions.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Bio-based Emulsion Polymer Development | +1.4% | Europe, United States | 2027 - 2034 |
| Expansion in Medical and Hygiene Textiles | +1.1% | Global | 2025 - 2034 |
| Nanotechnology-enabled Polymer Dispersions | +0.8% | Japan, South Korea, Germany | 2028 - 2034 |
Emulsion Polymer Market Challenges Impact Analysis
Technical challenges regarding the freeze-thaw stability of water-based emulsions and the competition from alternative technologies like UV-curable coatings pose significant hurdles. Ensuring consistent quality across diverse manufacturing sites and managing the waste generated during the emulsion process are ongoing operational challenges. Additionally, the market must adapt to the increasing consumer demand for "zero-additive" and "biocide-free" formulations, which complicates the shelf-life stability of the products.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Competition from Powder Coatings and UV-Curing | -0.6% | Global | 2025 - 2034 |
| Freeze-Thaw Stability Issues in Cold Climates | -0.3% | Canada, Northern Europe, Russia | Ongoing |
| Managing Microplastic Regulations | -0.5% | European Union | 2026 - 2030 |
Emulsion Polymer Market - Updated Report Scope
This report provides a comprehensive analysis of the global emulsion polymer industry, covering technical specifications, market dynamics, and competitive landscapes. It examines the entire value chain, from raw material suppliers of monomers and surfactants to the end-users in construction, automotive, and packaging sectors. The scope includes a detailed breakdown of chemical types, application segments, and regional performance metrics, offering stakeholders a clear roadmap for investment and strategic planning through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 40.52 Billion |
| Market Forecast in 2034 | USD 70.85 Billion |
| Growth Rate | 6.4% CAGR |
| Number of Pages | 274 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | BASF SE, Arkema S.A., The Dow Chemical Company, Celanese Corporation, Trinseo S.A., Wacker Chemie AG, Synthomer PLC, DIC Corporation, The Lubrizol Corporation, Asahi Kasei Corporation, Clariant AG, H.B. Fuller Company, Nippon Shokubai Co., Ltd., Allnex GMBH, Organik Kimya, Sumitomo Chemical Co., Ltd., Zeon Corporation, Avery Dennison Corporation, Kamsons Chemicals Pvt. Ltd., Mallard Creek Polymers. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The emulsion polymer market is segmented based on product chemistry and end-use application. Acrylics dominate the market due to their superior weather resistance and clarity, making them ideal for exterior paints. Vinyl acetate polymers are widely utilized in woodworking and paper adhesives due to their excellent bonding strength. Styrene-butadiene latex remains essential for high-speed paper coating applications and carpet backing. The emergence of high-performance Polyurethane Dispersions (PUDs) is catering to the demand for premium automotive interiors and luxury leather goods.
- By Product Type:
- Acrylics: The leading segment, sub-divided into pure acrylics for high-end coatings and styrene acrylics for cost-effective applications.
- Vinyl Acetate Polymers: Heavily used in adhesives and paper processing.
- Styrene-Butadiene (SB) Latex: Majorly applied in the paper and textile industries.
- Polyurethane Dispersions: Growing demand in specialized coatings for plastics and wood.
- Other Polymers: Including Nitrile Butadiene and Ethylene Vinyl Acetate.
- By Application:
- Paints & Coatings: Largest consumer of emulsion polymers for architectural and industrial uses.
- Adhesives & Sealants: Significant growth in pressure-sensitive adhesives and construction bonding.
- Paper & Paperboard: Used for enhancing printability and barrier properties.
- Textiles & Non-wovens: Essential for fabric finishing and binder applications in hygiene products.
- Others: Includes leather treatment and specialized construction additives.
Regional Highlights
- Asia-Pacific: The dominant region in terms of both production and consumption. China leads the global market, supported by its massive manufacturing base for consumer electronics and automotive parts. India is identified as the fastest-growing market due to the "Housing for All" initiative and rapid industrialization.
- North America: A mature market characterized by high innovation in specialty emulsions. The focus is on low-VOC and sustainable products, with the United States being a key hub for R&D in bio-based polymers.
- Europe: The most regulated market, with strict REACH compliance driving the shift toward eco-friendly dispersions. Germany and France are major contributors to the demand for high-performance industrial coatings.
- Latin America: Expected to show moderate growth, with Brazil and Mexico seeing increased demand in the construction and packaging sectors as economic stability improves.
- Middle East & Africa: Growth is driven by large-scale infrastructure projects in the GCC countries and the developing construction sector in African nations.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Emulsion Polymer Market.- BASF SE
- Arkema S.A.
- The Dow Chemical Company
- Celanese Corporation
- Trinseo S.A.
- Wacker Chemie AG
- Synthomer PLC
- DIC Corporation
- The Lubrizol Corporation
- Asahi Kasei Corporation
- Clariant AG
- H.B. Fuller Company
- Nippon Shokubai Co., Ltd.
- Allnex GMBH
- Organik Kimya
- Sumitomo Chemical Co., Ltd.
- Zeon Corporation
- Avery Dennison Corporation
- Kamsons Chemicals Pvt. Ltd.
- Mallard Creek Polymers
Frequently Asked Questions
What is the current market size of the Emulsion Polymer Market?
The global emulsion polymer market size is estimated at USD 40.52 Billion in 2025 and is projected to reach approximately USD 70.85 Billion by 2034, growing at a CAGR of 6.4%.
Which application segment holds the largest share in the Emulsion Polymer Market?
The Paints & Coatings segment holds the largest market share, driven by the global transition to water-based, eco-friendly decorative and industrial paints.
Which region is expected to grow the fastest during the forecast period?
The Asia-Pacific region is expected to be the fastest-growing region, fueled by rapid urbanization, infrastructure development, and rising industrial activities in China and India.
What are the key drivers for the Emulsion Polymer Market?
Primary drivers include stringent environmental regulations against VOC emissions, the shift from solvent-borne to water-borne systems, and rising demand from the construction and packaging industries.
What are the major challenges facing the Emulsion Polymer industry?
Key challenges include the volatility of raw material prices (petrochemical feedstocks), high transportation costs for liquid dispersions, and competition from alternative technologies like UV-curable and powder coatings.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
