Electric Vehicle Adhesives Market
Electric Vehicle Adhesives Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711956 | Published On : November 22, 2026 |
Format : 


 | Author : Ashraf Shehata
Electric Vehicle Adhesives Market Size
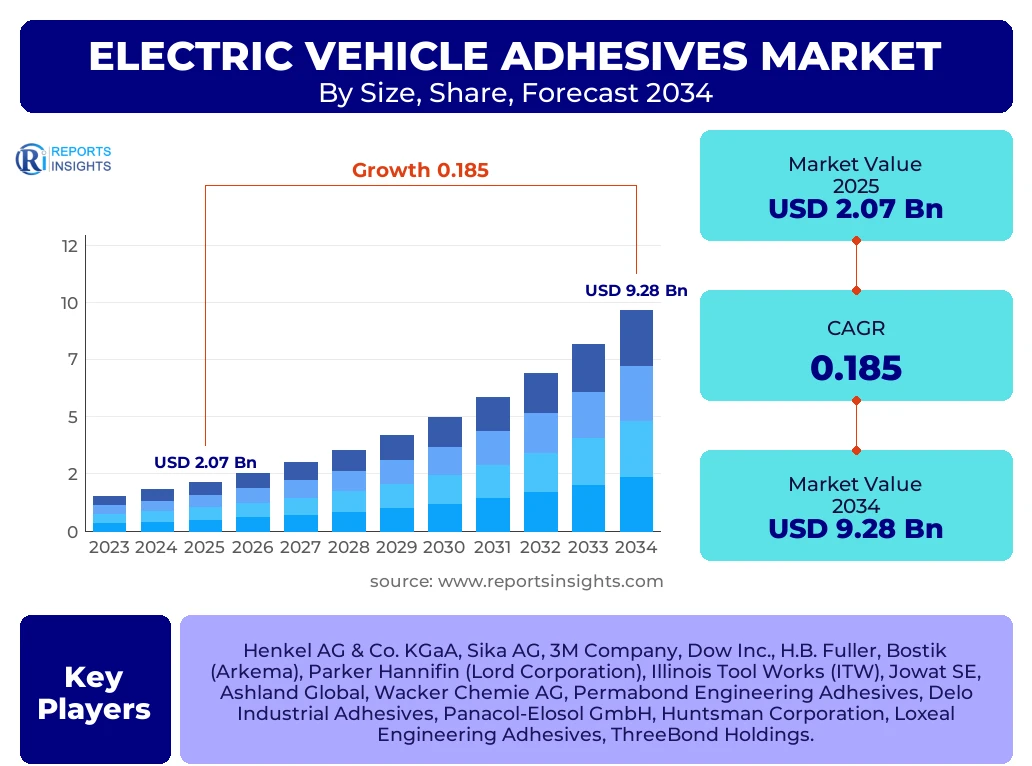
According to Reports Insights Consulting Pvt Ltd, The Electric Vehicle Adhesives Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 18.5% between 2025 and 2034. The market is estimated at USD 2.45 Billion in 2026 and is projected to reach USD 9.28 Billion by the end of the forecast period in 2034.
Key Electric Vehicle Adhesives Market Trends & Insights
The global shift toward sustainable mobility has fundamentally altered the chemical and material landscape of the automotive industry. As original equipment manufacturers (OEMs) transition from internal combustion engines to battery electric vehicles, the demand for specialized adhesive solutions has surged. These materials are no longer just secondary joining components but are now critical to the structural integrity, thermal management, and safety of high-voltage battery systems. Current market analysis indicates a significant move toward "cell-to-pack" (CTP) designs, which eliminate module housings and rely heavily on structural bonding to maintain rigidity while reducing weight. Furthermore, the integration of multi-material bonding—joining dissimilar materials like aluminum, carbon fiber, and high-strength steel—has become a central technological trend, driving the adoption of high-performance polyurethanes and epoxies.
- Asia-Pacific is currently the largest and fastest-growing region, driven by massive production volumes in China and significant investments in India and South Korea.
- The Battery Pack Application segment holds the largest market share, as adhesives are indispensable for cell bonding, sealing, and thermal interface management.
- Polyurethane-based adhesives represent the largest resin segment due to their versatility, impact resistance, and favorable curing profiles in automated assembly lines.
- There is a growing trend toward "Green Chemistry," with manufacturers developing bio-based or recyclable adhesives to align with the circular economy goals of modern EV production.
Key Takeaways Electric Vehicle Adhesives Market Size & Forecast
The market is entering a phase of rapid maturity where technical specifications are becoming increasingly standardized. Stakeholders are focusing on optimizing the "Total Cost of Ownership" by reducing assembly cycle times through fast-curing UV or moisture-cure adhesive technologies. Research indicates that as battery energy densities increase, the role of adhesives in mitigating thermal runaway becomes a primary safety requirement. The transition to 800V architectures in premium EVs is also creating a niche for high-dielectric strength adhesives that prevent electrical arcing within compact battery modules. Market forecasts suggest that the proliferation of commercial electric vehicles and electric buses will provide a secondary wave of growth for heavy-duty structural bonding agents through 2034.
- China remains the global leader in both production and consumption, accounting for over 45% of the total market volume as of 2025.
- Structural adhesives are rapidly replacing traditional mechanical fasteners, such as rivets and bolts, to achieve weight reduction and improved crashworthiness.
- Thermal Interface Materials (TIMs) are the most critical sub-segment within the battery category, essential for heat dissipation during rapid charging cycles.
- Sustainability regulations in the European Union are forcing a shift away from adhesives containing high Volatile Organic Compounds (VOCs), favoring aqueous or solvent-free formulations.
Electric Vehicle Adhesives Market Drivers Analysis
The primary driver for the electric vehicle adhesives market is the unrelenting industry-wide push for vehicle lightweighting to extend driving range. Every kilogram saved in the chassis or battery enclosure translates directly into improved watt-hour per kilometer efficiency. Additionally, the complexity of modern EV battery architectures requires bonding solutions that provide vibration damping and environmental sealing, which mechanical fasteners cannot achieve with the same level of reliability. The global expansion of charging infrastructure and government subsidies for EV purchases are also indirect but powerful catalysts for the high-volume production of adhesive-intensive vehicle platforms.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shift to Cell-to-Pack (CTP) Battery Architectures | +5.2% | Global / China Focus | 2025 - 2034 |
| Government Regulations on CO2 Emissions & EV Subsidies | +4.8% | European Union / North America | 2025 - 2030 |
| Advancements in Multi-Material Structural Bonding | +3.5% | Germany / Japan / USA | 2026 - 2034 |
| Increased Demand for Fast-Charging Thermal Management | +5.0% | Global | 2025 - 2034 |
Electric Vehicle Adhesives Market Restraints Analysis
Despite the optimistic growth trajectory, the market faces significant hurdles related to the volatility of raw material prices, particularly for petroleum-derived resins and specialized additives. Furthermore, the high initial cost of sophisticated dispensing and curing equipment can be a barrier for smaller tier-2 suppliers. There is also the technical challenge of "end-of-life" battery recycling; traditional high-strength structural adhesives make it difficult to disassemble battery packs for cell second-life applications or material recovery, leading to potential regulatory friction with right-to-repair and recycling mandates.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Complexity in Battery Disassembly for Recycling | -2.1% | Europe / North America | 2027 - 2034 |
| Raw Material Price Volatility (Epoxy/Silicone) | -1.5% | Global | 2025 - 2028 |
| High Capital Expenditure for Automated Dispensing | -1.2% | Developing Markets (ASEAN/LATAM) | 2025 - 2030 |
Electric Vehicle Adhesives Market Opportunities Analysis
The emergence of solid-state battery technology presents a transformative opportunity for the adhesives market, requiring entirely new classes of stable, high-pressure bonding agents. Additionally, the development of "Debond-on-Demand" adhesives—materials that maintain structural integrity during the vehicle's life but can be released through specific thermal or electrical triggers—is a major white-space opportunity. Expansion into emerging economies like India and Brazil, where EV adoption is just beginning to scale, offers significant first-mover advantages for global adhesive manufacturers who can localize their supply chains.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Debond-on-Demand Technologies | +3.8% | Germany / USA / South Korea | 2028 - 2034 |
| Expansion in Southeast Asian EV Manufacturing Hubs | +2.9% | Thailand / Vietnam / India | 2026 - 2034 |
| Bio-Based and Sustainable Resin Formulations | +2.4% | Europe / Japan | 2025 - 2034 |
Electric Vehicle Adhesives Market Challenges Impact Analysis
One of the most persistent challenges is the requirement for adhesives to maintain performance across extreme temperature ranges, from sub-zero winters to the intense heat generated during rapid DC charging. Ensuring long-term durability (15+ years) under constant mechanical vibration and environmental exposure is a high bar for material science. Additionally, the lack of standardized testing protocols across different OEMs leads to fragmented product development cycles, forcing adhesive suppliers to maintain a vast and expensive portfolio of customized formulations.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Long-Term Durability Standards | -1.8% | Global | Ongoing |
| Lack of Industry-Wide Testing Standardization | -1.4% | Global OEM Landscape | 2025 - 2030 |
Electric Vehicle Adhesives Market - Updated Report Scope
This report provides a granular analysis of the global electric vehicle adhesives ecosystem, covering the entire value chain from raw material suppliers to automotive OEMs. It encompasses detailed volume and value forecasts, competitive benchmarking, and technological roadmaps for the next decade. The scope includes all major chemistries and application areas, providing a holistic view of how material science is enabling the next generation of electrified transportation.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 2.07 Billion |
| Market Forecast in 2034 | USD 9.28 Billion |
| Growth Rate | 18.5% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Henkel AG & Co. KGaA, Sika AG, 3M Company, Dow Inc., H.B. Fuller, Bostik (Arkema), Parker Hannifin (Lord Corporation), Illinois Tool Works (ITW), Jowat SE, Ashland Global, Wacker Chemie AG, Permabond Engineering Adhesives, Delo Industrial Adhesives, Panacol-Elosol GmbH, Huntsman Corporation, Loxeal Engineering Adhesives, ThreeBond Holdings. |
| Regions Covered | North America (US, Canada), Europe (Germany, France, UK, Italy, Rest of Europe), Asia Pacific (China, Japan, India, South Korea, Rest of APAC), Latin America (Brazil, Mexico), Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is characterized by a high degree of technical segmentation, where the choice of adhesive is dictated by the specific thermal, mechanical, and electrical requirements of the vehicle component. Structural adhesives are primarily used in the chassis and battery frame, whereas non-structural adhesives dominate the interior and sensor assemblies. The following categories represent the current market framework:
- By Resin Type:
- Epoxy: Preferred for high-strength structural bonding and battery cell encapsulation.
- Polyurethane: Widely used for windshield bonding and battery tray sealing due to its flexibility.
- Silicone: Critical for thermal management and sealing in high-temperature environments.
- Acrylic: Gaining traction for its fast curing and ability to bond oily metals.
- By Application:
- Battery Pack: Includes thermal interface materials, cell-to-module bonding, and housing seals.
- Powertrain: Focuses on motor magnets, inverters, and gearbox assemblies.
- Exterior: Structural bonding of body panels and lightweight composite integrations.
- Interior: Low-VOC bonding for seating, dashboards, and electronic displays.
- By Vehicle Type:
- Passenger Cars: The volume leader, utilizing advanced lightweighting adhesives.
- Commercial Vehicles: Focused on heavy-duty durability and long-cycle vibrations.
Regional Highlights
- Asia-Pacific: Dominates the global market with a share exceeding 50% in terms of volume. China's mature EV supply chain and the presence of major battery manufacturers like CATL and BYD drive massive consumption of thermal and structural adhesives.
- Europe: The second-largest market, characterized by stringent environmental regulations (REACH) and a focus on premium EV manufacturing. Germany is the regional hub for innovation in structural bonding for high-performance vehicles.
- North America: Experiencing robust growth due to the expansion of Tesla’s manufacturing footprint and new battery plants ("Gigafactories") in the United States. The region focuses heavily on automation-compatible adhesive solutions.
- Rest of the World: Emerging growth in Latin America and India is expected to accelerate as local governments implement "Make in India" and similar manufacturing incentive programs for electric mobility.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Electric Vehicle Adhesives Market.- Henkel AG & Co. KGaA
- Sika AG
- 3M Company
- Dow Inc.
- H.B. Fuller
- Bostik (Arkema Group)
- Parker Hannifin (Lord Corporation)
- Illinois Tool Works (ITW)
- Wacker Chemie AG
- Huntsman Corporation
- Jowat SE
- Ashland Global
- Delo Industrial Adhesives
- Panacol-Elosol GmbH
- ThreeBond Holdings
- Permabond Engineering Adhesives
- Loxeal Engineering Adhesives
- Master Bond Inc.
Frequently Asked Questions
What is the current market size of the Electric Vehicle Adhesives industry?
The market is estimated to be valued at approximately USD 2.07 Billion in 2025 and is projected to reach USD 9.28 Billion by 2034, growing at a CAGR of 18.5%.
Which application segment holds the largest share?
The Battery Pack application segment holds the largest share, as it requires extensive use of thermal interface materials, structural bonding, and environmental sealing to ensure safety and performance.
Why are adhesives replacing mechanical fasteners in EVs?
Adhesives provide superior lightweighting, better stress distribution, vibration damping, and the ability to bond dissimilar materials, which is crucial for extending EV range and improving crash safety.
Which region is expected to witness the fastest growth?
Asia-Pacific is the fastest-growing region, fueled by the massive scale of EV production in China, South Korea, and the emerging manufacturing sector in India.
What are the main technical challenges for EV adhesive manufacturers?
Key challenges include ensuring long-term durability in extreme temperatures, developing "recycling-friendly" debonding solutions, and keeping pace with rapidly changing battery architectures.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
