Forklift Market
Forklift Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_702632 | Published On : October 14, 2026 |
Format : 


 | Author : Ashraf Shehata
Forklift Market Size
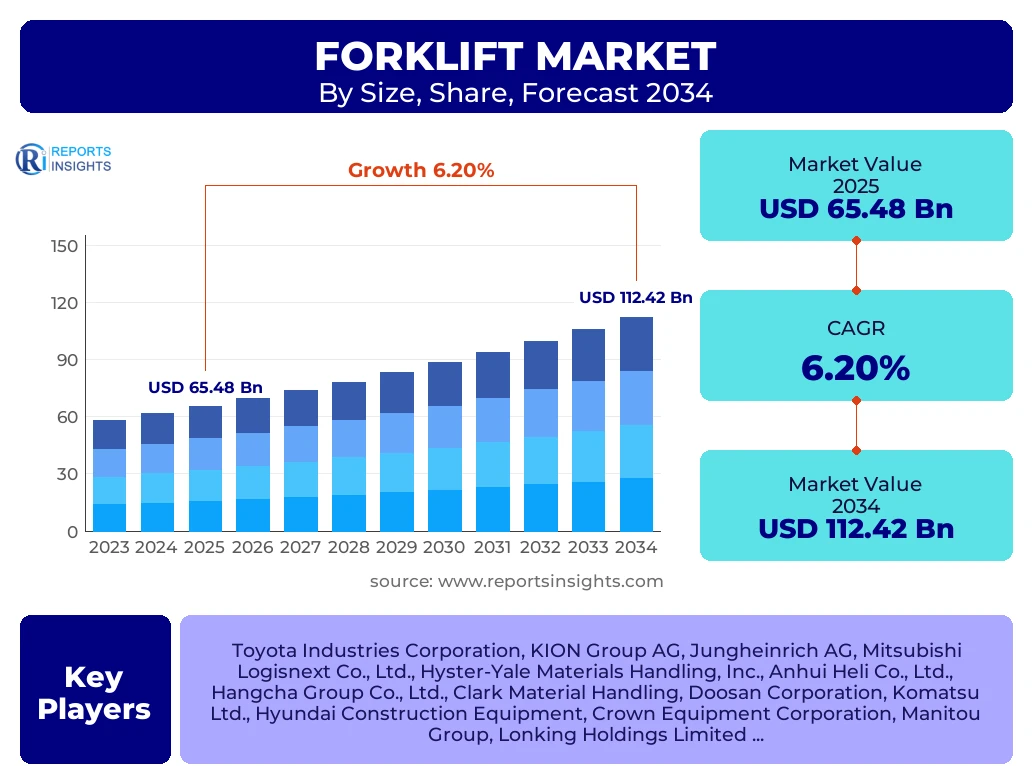
According to Reports Insights Consulting Pvt Ltd, The Forklift Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2025 and 2034. The market is estimated at USD 69.54 Billion in 2026 and is projected to reach USD 112.42 Billion by the end of the forecast period in 2034.
Key Forklift Market Trends & Insights
The global forklift market is currently undergoing a transformative phase driven by the convergence of industrial automation, the rapid expansion of e-commerce, and a paradigm shift toward sustainable energy solutions. As global supply chains become more complex, the demand for efficient material handling equipment has escalated, prompting manufacturers to integrate advanced technologies such as the Internet of Things (IoT), telematics, and autonomous navigation systems. The transition from internal combustion engine (ICE) forklifts to electric-powered alternatives is the most significant trend, fueled by stringent carbon emission regulations and the superior total cost of ownership (TCO) offered by lithium-ion battery technology. Furthermore, the integration of warehouse management systems (WMS) with material handling hardware is optimizing throughput and reducing operational downtime in high-density storage environments.
The market is also witnessing a surge in the adoption of Automated Guided Vehicles (AGVs) and Autonomous Mobile Robots (AMRs) as enterprises seek to mitigate labor shortages and improve safety standards. Competitive benchmarking indicates that leading market participants are focusing on modular designs that allow for easier maintenance and adaptability to diverse indoor and outdoor applications. Regional insights suggest that while developed markets in Europe and North America are focusing on high-end automation and green energy, emerging economies in the Asia-Pacific region are experiencing volume-driven growth due to massive investments in infrastructure and manufacturing hubs. The following points summarize the primary regional and segmental dynamics shaping the current landscape:
- Asia-Pacific is the largest and fastest-growing regional market, accounting for a significant share of global production and consumption.
- The Electric Forklift segment is the fastest-growing power source category, driven by indoor warehouse requirements and environmental mandates.
- Class III (Electric Warehouse Pedestrian Trucks) holds a dominant share in terms of unit volume due to the proliferation of small to medium-sized retail warehouses.
- The E-commerce and Logistics sector remains the largest end-use segment, requiring high-velocity material movement solutions.
- Lithium-ion technology is rapidly replacing lead-acid batteries as the preferred energy storage solution due to faster charging and longer lifespans.
Key Takeaways Forklift Market Size & Forecast
The long-term outlook for the forklift market remains robust, with a projected valuation exceeding USD 112 billion by 2034. This growth is underpinned by the structural shift in consumer behavior toward online shopping, which necessitates large-scale logistics infrastructure and advanced fulfillment centers. Market participants are increasingly focusing on the development of heavy-duty electric forklifts capable of competing with traditional diesel counterparts in outdoor and rugged environments. Strategic collaborations between forklift OEMs and software developers are also becoming more common, as the industry moves toward a "Product-as-a-Service" model where data analytics and fleet management play a central role in value creation.
- China and India are identified as the leading growth engines within the Asia-Pacific region, supported by government initiatives such as Made in China 2025 and Make in India.
- The forecast period will see a significant decline in the market share of Internal Combustion (IC) engine forklifts in favor of zero-emission alternatives.
- Warehouse automation and the integration of artificial intelligence for predictive maintenance are becoming critical competitive differentiators.
- The manufacturing sector, particularly automotive and electronics, continues to be a major contributor to the steady demand for high-capacity forklifts.
- Safety innovations, including 360-degree camera systems and proximity sensors, are seeing universal adoption across all forklift classes to reduce workplace accidents.
Forklift Market Drivers Analysis
The primary driver for the forklift market is the unprecedented expansion of the global e-commerce industry, which has redefined warehouse operations and logistics requirements. Companies are forced to optimize their vertical storage and horizontal movement to manage a higher volume of stock-keeping units (SKUs). Additionally, the global push for decarbonization is driving the replacement of older ICE fleets with electric models, supported by subsidies and favorable regulatory frameworks in many jurisdictions. Technological advancements in battery energy density and autonomous navigation are further accelerating the replacement cycle of aging equipment.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| E-commerce Logistics Expansion | +2.4% | Global (Strongest in US & China) | 2025 - 2034 |
| Electrification and Green Energy Transition | +1.8% | Europe and North America | 2025 - 2030 |
| Industrial Automation and Industry 4.0 | +1.2% | Germany, Japan, South Korea | 2026 - 2034 |
| Infrastructure Development in Emerging Markets | +0.8% | India, Southeast Asia, Brazil | 2025 - 2032 |
Forklift Market Restraints Analysis
Despite strong growth prospects, the forklift market faces restraints such as high initial capital expenditure for advanced automated and electric models. For small and medium-sized enterprises (SMEs), the upfront cost of lithium-ion technology and the necessary charging infrastructure can be a significant barrier to entry. Furthermore, fluctuations in raw material prices, particularly for steel and battery-grade minerals like lithium and cobalt, can impact manufacturer margins and lead to price volatility for end-users. Regulatory compliance regarding safety and emissions also varies significantly across regions, creating complexities for global manufacturers.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Investment for Automation | -1.1% | Global (Affecting SMEs) | 2025 - 2028 |
| Supply Chain Disruptions for Components | -0.7% | Global | 2025 - 2027 |
| Stringent Environmental Regulations (ICE) | -0.4% | European Union | 2025 - 2034 |
Forklift Market Opportunities Analysis
The emergence of hydrogen fuel cell forklifts represents a major opportunity for the market, particularly for high-throughput 24/7 operations where battery charging downtime is unacceptable. Hydrogen offers rapid refueling and constant power delivery, making it ideal for large-scale cold storage and heavy industrial applications. Additionally, the integration of AI-driven telematics provides a secondary revenue stream for OEMs through data-driven services, such as predictive maintenance, fleet optimization, and safety monitoring. The growing rental and leasing market also provides an opportunity to reach customers who prefer operational expenditure (OPEX) models over capital expenditure (CAPEX).
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Hydrogen Fuel Cell Adoption | +1.5% | Japan, USA, Germany | 2027 - 2034 |
| Telematics and Fleet Management Software | +1.1% | Global | 2025 - 2034 |
| Expansion of Rental and Leasing Services | +0.9% | Latin America, SE Asia | 2025 - 2030 |
Forklift Market Challenges Impact Analysis
One of the primary challenges facing the industry is the shortage of skilled operators and technicians capable of managing and maintaining advanced electronic and autonomous systems. As forklifts become more sophisticated, the gap between traditional mechanical skills and modern software-driven diagnostics continues to widen. Additionally, cybersecurity risks associated with connected fleets present a new challenge for logistics providers, as any breach could lead to significant operational disruptions or safety hazards. Maintaining high performance in extreme environments, such as deep-freeze warehouses, also remains a technical hurdle for battery-powered equipment.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Labor Shortage and Skill Gaps | -0.8% | North America and Western Europe | 2025 - 2034 |
| Cybersecurity for Connected Fleets | -0.5% | Highly Digitized Markets | 2026 - 2034 |
| Interoperability of Mixed Fleets | -0.3% | Global | 2025 - 2030 |
Forklift Market - Updated Report Scope
This comprehensive report provides a detailed analysis of the global forklift market across five major geographical regions and various technical segments. The scope includes historical data from 2020 to 2024, a baseline assessment for 2025, and a rigorous forecast through 2034. The research methodology integrates primary insights from industry experts with secondary data from financial reports, trade associations, and government databases to ensure high accuracy in market sizing and trend analysis. The report covers various forklift classes, power sources, and end-user industries, offering a 360-degree view of the competitive landscape and technological evolution.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 65.48 Billion |
| Market Forecast in 2034 | USD 112.42 Billion |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Toyota Industries Corporation, KION Group AG, Jungheinrich AG, Mitsubishi Logisnext Co., Ltd., Hyster-Yale Materials Handling, Inc., Anhui Heli Co., Ltd., Hangcha Group Co., Ltd., Clark Material Handling, Doosan Corporation, Komatsu Ltd., Hyundai Construction Equipment, Crown Equipment Corporation, Manitou Group, Lonking Holdings Limited, EP Equipment, LiuGong Machinery Co., Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The forklift market is segmented based on class, power source, tonnage, and end-user application to provide a granular understanding of growth pockets. The classification system developed by the Industrial Truck Association (ITA) remains the industry standard, with Class I, II, and III representing the electric fleet that is currently seeing the most rapid innovation. Internal Combustion (IC) forklifts, classified under Class IV and V, continue to hold relevance in heavy-duty outdoor applications, particularly in construction and port logistics, though they are under pressure from tightening emission norms. The tonnage segmentation reveals that the "Below 5 Tons" category is the most voluminous, catering to the majority of standard warehouse operations.
- By Class: Class I (Electric Motor Rider), Class II (Electric Motor Narrow Aisle), Class III (Electric Motor Hand), Class IV (Internal Combustion - Cushion Tire), Class V (Internal Combustion - Pneumatic Tire).
- By Power Source: Electric (Lithium-ion, Lead-acid), Internal Combustion Engine (Diesel, LPG, Gasoline), Hydrogen Fuel Cell.
- By Tonnage: Light Duty (Below 5 Tons), Medium Duty (5-10 Tons), Heavy Duty (Above 10 Tons).
- By End-User: Logistics, Retail/E-commerce, Automotive, Food & Beverage, Construction, Mining, and Chemical Processing.
Regional Highlights
- Asia-Pacific: The region is the largest market shareholder, dominated by China, which acts as both a massive consumer and a leading global exporter of forklifts. India is the fastest-growing market in the region due to the modernization of its logistics sector.
- North America: A leader in the adoption of autonomous and AI-integrated forklifts. The US market is driven by high labor costs, which incentivize investment in automation and Class II/III warehouse trucks.
- Europe: The most advanced region in terms of electrification and sustainability. Countries like Germany and France have high penetration rates for electric forklifts due to strict environmental regulations and well-developed charging infrastructures.
- Latin America: Expected to show steady growth driven by the expansion of the retail sector in Brazil and Mexico, with a focus on cost-effective internal combustion models transitioning gradually to electric.
- Middle East & Africa: Growth is primarily linked to infrastructure projects and the expansion of major shipping hubs in the UAE and Saudi Arabia.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Forklift Market.- Toyota Industries Corporation
- KION Group AG
- Jungheinrich AG
- Mitsubishi Logisnext Co., Ltd.
- Hyster-Yale Materials Handling, Inc.
- Anhui Heli Co., Ltd.
- Hangcha Group Co., Ltd.
- Clark Material Handling
- Doosan Corporation
- Komatsu Ltd.
- Hyundai Construction Equipment
- Crown Equipment Corporation
- Manitou Group
- Lonking Holdings Limited
- EP Equipment
- LiuGong Machinery Co., Ltd.
- Godrej & Boyce Mfg. Co. Ltd.
- Hubtex Maschinenbau GmbH
Frequently Asked Questions
What is the projected market size of the global Forklift Market by 2034?
The global forklift market is projected to reach approximately USD 112.42 billion by 2034, growing at a CAGR of 6.2% from the base year 2025.
Which region holds the largest share of the Forklift Market?
Asia-Pacific currently holds the largest market share and is expected to remain the dominant region through 2034, fueled by industrialization in China and India.
What are the main factors driving the shift to electric forklifts?
The primary drivers include stringent government emission regulations, lower operational costs of lithium-ion batteries, and the increasing need for indoor warehouse-compatible equipment.
How is automation impacting the forklift industry?
Automation is leading to the rise of AGVs and AMRs, which help companies reduce labor costs, enhance precision in material handling, and improve overall warehouse safety.
What are the key classes of forklifts used in modern warehouses?
The most common classes in warehouses are Class I (Electric Riders), Class II (Narrow Aisle Trucks), and Class III (Electric Hand Trucks/Pallet Jacks) due to their zero emissions and maneuverability.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
