DNA Repair Drugs Market
DNA Repair Drugs Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711312 | Published On : October 26, 2026 |
Format : 


 | Author : Erika Grotto
DNA Repair Drugs Market Size
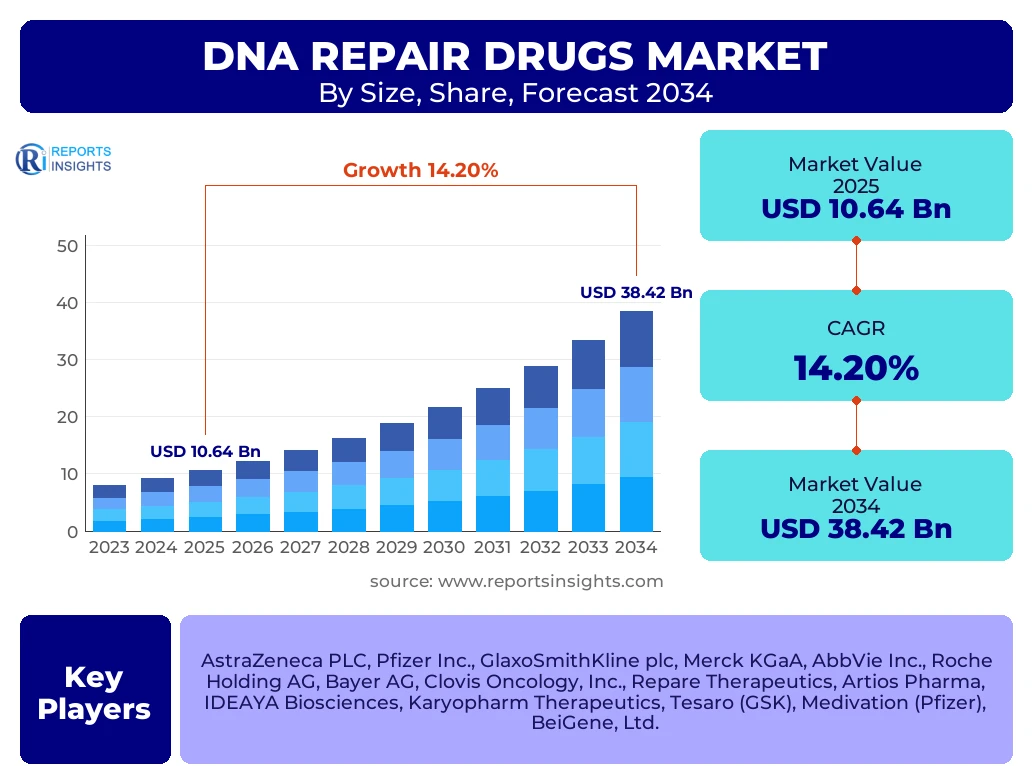
According to Reports Insights Consulting Pvt Ltd, The DNA Repair Drugs Market is projected to grow at a Compound Growth Rate (CAGR) of 14.2% between 2025 and 2034. The market is estimated at USD 12.15 Billion in 2026 and is projected to reach USD 38.42 Billion by the end of the forecast period in 2034.
Key DNA Repair Drugs Market Trends & Insights
The global landscape for DNA Repair Drugs is undergoing a transformative shift as precision oncology moves from broad-spectrum treatments to molecularly targeted therapies. Recent insights indicate that the integration of DNA Damage Response (DDR) inhibitors with existing immunotherapy protocols is the primary driver of market expansion. Stakeholders are increasingly focusing on synthetic lethality, a mechanism where the combination of two genetic deficiencies leads to cell death, which has proven highly effective in treating BRCA-mutated cancers. Furthermore, the rise of personalized medicine and advanced genomic sequencing has enabled clinicians to identify specific DNA repair deficiencies in patients, allowing for the administration of highly specialized therapeutic agents. Competitive benchmarking reveals that leading pharmaceutical entities are aggressively pursuing multi-indication approvals for PARP inhibitors, expanding their utility from ovarian cancer to breast, prostate, and pancreatic malignancies.
- North America remains the largest regional market due to high healthcare expenditure and early adoption of targeted therapies.
- The Asia Pacific region is identified as the fastest-growing market, fueled by increasing cancer incidence and expanding biotechnology infrastructure in China and India.
- The PARP Inhibitors segment currently holds the largest market share by drug class, driven by established clinical success and robust sales of frontline therapies.
- Combination therapies involving DNA Repair Drugs and immune checkpoint inhibitors are emerging as a dominant trend in clinical trial pipelines.
- Advancements in liquid biopsy technology are facilitating real-time monitoring of DNA repair drug efficacy and resistance patterns.
Key Takeaways DNA Repair Drugs Market Size & Forecast
The DNA Repair Drugs market is characterized by rapid technological evolution and a deepening understanding of the human genome. Market analysis suggests that the transition toward frontline maintenance therapy in various oncology segments will significantly bolster long-term revenue streams. Investors and healthcare providers are closely monitoring the emergence of next-generation DDR targets, such as ATR, ATM, and DNA-PK inhibitors, which are expected to address the limitations of first-generation PARP inhibitors, particularly in patients who have developed resistance. The forecast period anticipates a surge in regulatory approvals as clinical data matures, supported by a favorable landscape for orphan drug designations and accelerated approval pathways in major economies.
- The United States is the leading country in terms of value, supported by a concentration of major pharmaceutical headquarters and high R&D investment.
- Ovarian cancer remains the primary application area, though prostate and breast cancer segments are capturing significant market share.
- Technological integration of AI in drug discovery is reducing the lead time for identifying novel DNA repair targets.
- Strategic collaborations between diagnostic companies and pharmaceutical firms are essential for the co-development of companion diagnostics.
- The shift toward outpatient oral oncology medications is improving patient compliance and market penetration for DNA repair agents.
DNA Repair Drugs Market Drivers Analysis
The expansion of the DNA Repair Drugs market is primarily fueled by the rising global prevalence of chronic malignancies and the critical need for therapies that minimize damage to healthy tissues. The shift toward precision medicine, supported by government initiatives and increased funding for genomics research, is creating a fertile environment for the adoption of DNA Damage Response inhibitors.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Global Cancer Prevalence | +4.2% | Global | 2025-2034 |
| Advancements in Synthetic Lethality Research | +3.5% | North America and Europe | 2026-2030 |
| Increased Investment in Precision Oncology | +2.8% | USA, China, Germany | 2025-2034 |
| FDA Approvals for Expanded Indications | +3.7% | United States | 2025-2028 |
DNA Repair Drugs Market Restraints Analysis
Despite the high growth potential, the market faces significant hurdles including the exorbitant cost of specialized oncology treatments and the complex regulatory requirements for biological drugs. Additionally, the emergence of drug resistance mechanisms in patients undergoing prolonged treatment remains a critical concern for clinicians and manufacturers alike.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Therapy and Reimbursement Issues | -2.1% | Developing Economies | 2025-2034 |
| Development of Acquired Drug Resistance | -1.8% | Global | 2027-2034 |
| Stringent Regulatory Approval Pathways | -1.2% | Europe and North America | 2025-2030 |
DNA Repair Drugs Market Opportunities Analysis
The untapped potential in emerging markets and the exploration of DNA repair pathways beyond oncology, such as in neurodegenerative diseases and aging, present significant growth avenues. The development of next-generation inhibitors targeting ATR and DNA-PK pathways offers a major opportunity to treat patients who do not respond to traditional PARP inhibitors.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Next-Generation ATR/ATM Inhibitors | +4.5% | Japan, UK, USA | 2028-2034 |
| Expansion into Emerging Markets (APAC/LATAM) | +3.2% | China, India, Brazil | 2026-2034 |
| Application in Non-Oncology Segments | +1.5% | Global | 2030-2034 |
DNA Repair Drugs Market Challenges Impact Analysis
Market participants must navigate the challenges of high clinical trial failure rates and the intense competition from alternative therapies like CAR-T cell therapy and antibody-drug conjugates (ADCs). Ensuring the safety and managing the toxicity profiles of combination therapies also remains a pivotal technical challenge.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Attrition Rates in Clinical Trials | -2.5% | Global | 2025-2034 |
| Competition from CAR-T and ADC Therapies | -1.5% | North America | 2026-2034 |
| Complex Manufacturing and Supply Chain Logistics | -0.8% | Global | 2025-2028 |
DNA Repair Drugs Market - Updated Report Scope
The scope of this report covers a comprehensive analysis of the DNA Repair Drugs sector, encompassing various drug classes, clinical indications, and geographical regions. It evaluates the competitive landscape, highlighting the strategic initiatives of key players and the impact of technological advancements on market dynamics through the forecast period of 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 10.64 Billion |
| Market Forecast in 2034 | USD 38.42 Billion |
| Growth Rate | 14.2% CAGR |
| Number of Pages | 274 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | AstraZeneca PLC, Pfizer Inc., GlaxoSmithKline plc, Merck KGaA, AbbVie Inc., Roche Holding AG, Bayer AG, Clovis Oncology, Inc., Repare Therapeutics, Artios Pharma, IDEAYA Biosciences, Karyopharm Therapeutics, Tesaro (GSK), Medivation (Pfizer), BeiGene, Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The DNA Repair Drugs market is segmented based on the mechanism of action, therapeutic application, and end-user accessibility. Understanding these segments is crucial for identifying high-growth opportunities and tailoring R&D efforts toward unmet clinical needs.
- By Drug Class:
- PARP Inhibitors: The most mature segment, featuring drugs like Olaparib and Niraparib.
- ATR Inhibitors: Emerging class targeting the Ataxia Telangiectasia and Rad3-related protein.
- ATM Inhibitors: Focus on Ataxia Telangiectasia Mutated kinase for radiosensitization.
- DNA-PK Inhibitors: Targeting DNA-dependent protein kinase for complex double-strand break repair.
- Other DDR Inhibitors: Including WEE1 and CHK1/2 inhibitors.
- By Indication:
- Ovarian Cancer: Historically the largest segment due to high BRCA mutation prevalence.
- Breast Cancer: Growing rapidly with the expansion of PARP inhibitors in HER2-negative patients.
- Prostate Cancer: Significant growth following recent approvals for metastatic castration-resistant cases.
- Lung Cancer: Increasing focus on DDR inhibitors as part of combination regimens for SCLC and NSCLC.
- By Distribution Channel:
- Hospital Pharmacies: Leading channel due to the requirement for specialized administration.
- Retail Pharmacies: Increasing share with the availability of oral formulations.
- Online Pharmacies: Fastest-growing segment driven by digital health adoption.
Regional Highlights
- North America: This region holds the largest market share, estimated at approximately 42% in 2025. The dominance is attributed to advanced genomic research facilities, high healthcare spending, and a robust pipeline of clinical trials. The United States is the primary contributor to this regional valuation.
- Europe: Europe is the second-largest market, characterized by strong government support for cancer research and a well-established regulatory framework through the EMA. Countries like Germany, France, and the UK are at the forefront of DDR drug adoption.
- Asia Pacific: This is the fastest-growing region with an expected CAGR of over 16%. The growth is driven by a massive patient population, increasing investments in biotech hubs in China and Singapore, and improving access to oncology medications.
- Latin America and MEA: These regions are witnessing gradual growth due to improving healthcare infrastructure and rising awareness of targeted cancer therapies. Brazil and South Africa are key markets within these territories.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the DNA Repair Drugs Market.- AstraZeneca PLC
- Pfizer Inc.
- GlaxoSmithKline plc
- Merck KGaA
- AbbVie Inc.
- Roche Holding AG
- Bayer AG
- Clovis Oncology, Inc.
- Repare Therapeutics
- Artios Pharma
- IDEAYA Biosciences
- Karyopharm Therapeutics
- BeiGene, Ltd.
- Sierra Oncology (GSK)
- Impact Therapeutics
- Zenith Epigenetics
- AstraZeneca-Merck Alliance
Frequently Asked Questions
What are DNA Repair Drugs and how do they work in cancer treatment?
DNA Repair Drugs, primarily DNA Damage Response (DDR) inhibitors, work by blocking the proteins that cancer cells use to fix their damaged DNA. By inhibiting these repair mechanisms, specifically through synthetic lethality (like PARP inhibitors in BRCA-mutant cells), the drugs cause the cancer cells to accumulate fatal genomic damage and die, while sparing more healthy cells compared to traditional chemotherapy.
Which drug class currently dominates the DNA Repair Drugs market?
The PARP (Poly ADP-ribose polymerase) inhibitor class currently dominates the market. This is due to the early clinical success and regulatory approval of several frontline drugs such as Olaparib (Lynparza), Niraparib (Zejula), and Rucaparib (Rubraca), which have established roles in treating ovarian, breast, and prostate cancers.
What is the projected growth rate of the market through 2034?
The DNA Repair Drugs market is projected to grow at a Compound Annual Growth Rate (CAGR) of 14.2% from 2025 to 2034. This growth is driven by the expansion of clinical indications, the development of next-generation ATR and ATM inhibitors, and the increasing adoption of personalized medicine globally.
What are the main challenges facing the DNA Repair Drugs market?
Key challenges include the high cost of treatment which limits accessibility in developing nations, the inevitable development of drug resistance in patients, and the high risk of failure in clinical trials for novel DDR targets. Managing toxicity profiles when these drugs are used in combination with other therapies also remains a significant concern.
Which region is expected to show the fastest growth in the DNA Repair Drugs market?
The Asia Pacific region is expected to show the fastest growth over the forecast period. Factors such as a rising incidence of cancer, significant improvements in healthcare infrastructure, and increasing pharmaceutical R&D investment in countries like China and India are the primary catalysts for this rapid expansion.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
