Bone Cancer Treatment Market
Bone Cancer Treatment Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711286 | Published On : October 24, 2026 |
Format : 


 | Author : Erika Grotto
Bone Cancer Treatment Market Size
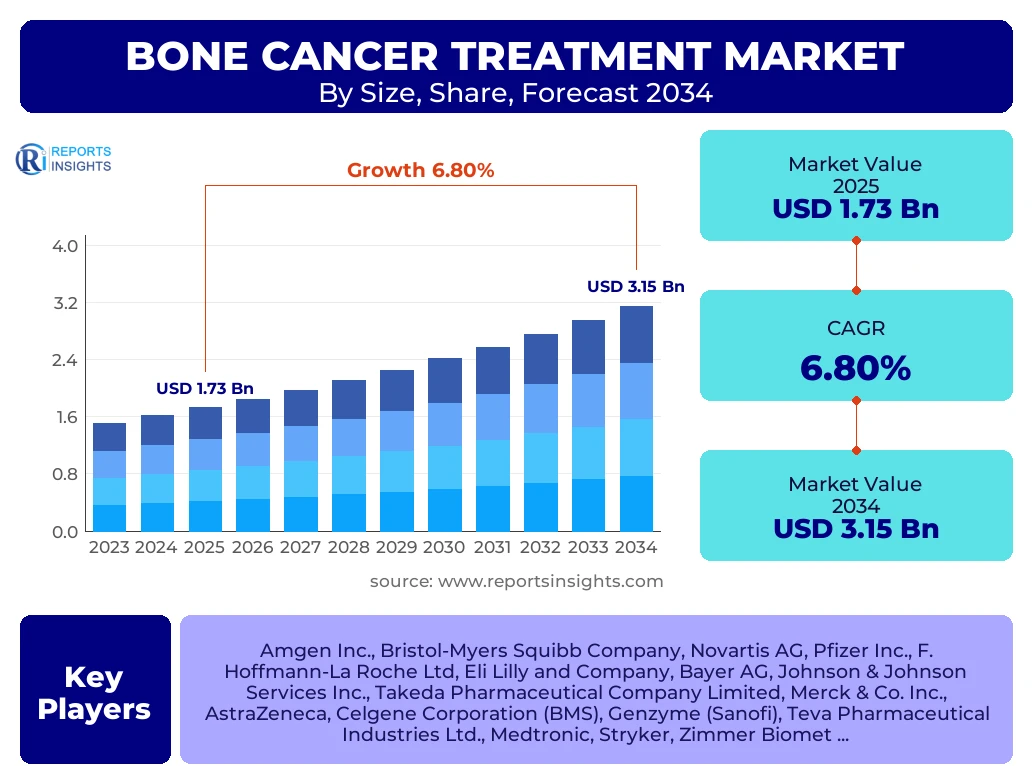
According to Reports Insights Consulting Pvt Ltd, The Bone Cancer Treatment Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.8% between 2025 and 2034. The market is estimated at USD 1.85 Billion in 2026 and is projected to reach USD 3.15 Billion by the end of the forecast period in 2034.
Key Bone Cancer Treatment Market Trends & Insights
The Bone Cancer Treatment market is currently undergoing a significant paradigm shift, transitioning from conventional cytotoxic chemotherapy toward highly precise, molecularly targeted interventions and advanced immunotherapy protocols. Stakeholders are increasingly focusing on the integration of artificial intelligence in radiological diagnostics and the adoption of liquid biopsies for early-stage detection. The market is characterized by a high degree of research and development activity, particularly in the realm of rare pediatric bone cancers such as Ewing sarcoma and osteosarcoma. Strategic collaborations between pharmaceutical giants and specialized biotechnology firms are accelerating the pipeline for orphan drugs, which receive accelerated regulatory pathways, thereby influencing global market dynamics and competitive benchmarking across key regions.
- Largest Region: North America remains the dominant market share holder due to high healthcare expenditure and advanced oncology infrastructure.
- Fastest Growing Region: Asia-Pacific is anticipated to exhibit the highest CAGR, driven by improving healthcare accessibility and rising diagnostic rates in emerging economies like China and India.
- Largest Segment: The chemotherapy segment currently holds the largest market share, though targeted therapy is gaining rapid ground.
- Leading End-User: Hospitals continue to lead the market share as primary centers for complex surgical procedures and intensive therapy.
Key Takeaways Bone Cancer Treatment Market Size & Forecast
The long-term trajectory for the Bone Cancer Treatment market remains robust, supported by an aging global population and increased awareness regarding early symptom identification. Analysts note that the shift toward personalized medicine is not merely a trend but a fundamental structural change in how oncology providers approach treatment regimens. The forecast period 2025-2034 suggests a steady rise in the adoption of biologics and biosimilars, which will help alleviate the cost burden on healthcare systems while maintaining efficacy. Key countries such as the United States, Germany, and Japan are leading in terms of innovation, while the rest of the world catches up through technology transfer and localized manufacturing of essential oncology medications.
- The United States represents the largest national market, backed by a sophisticated reimbursement framework and extensive clinical trial networks.
- Immunotherapy is projected to become a critical growth pillar, specifically for patients who show resistance to traditional chemotherapy.
- Technological advancements in limb-salvage surgeries are reducing the necessity for amputations, improving patient quality of life.
- Orphan drug designations are providing significant financial incentives for players targeting rare bone malignancies.
- The rise of specialized oncology clinics is diversifying the provider landscape, offering more focused care environments.
Bone Cancer Treatment Market Drivers Analysis
Market drivers for bone cancer treatment are multi-faceted, ranging from clinical advancements to demographic shifts. The primary catalyst is the increasing incidence of primary bone cancers and the rising prevalence of metastatic bone disease resulting from breast, prostate, and lung cancers. Furthermore, the expansion of genomic sequencing allows for the identification of specific genetic mutations, enabling the use of targeted therapies that offer higher success rates with fewer systemic side effects. Government initiatives and increased funding for cancer research also play a pivotal role in maintaining the market’s upward momentum.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Advancements in Targeted and Immunotherapy | +2.4% | Global (High in North America & Europe) | 2025–2034 |
| Rising Incidence of Metastatic Bone Disease | +1.8% | Developed Economies | 2025–2030 |
| Increased Government Funding for Orphan Drugs | +1.2% | USA and EU-5 | 2026–2034 |
| Integration of AI in Early Diagnostics | +0.9% | Japan, South Korea, USA | 2027–2034 |
Bone Cancer Treatment Market Restraints Analysis
Despite strong growth prospects, the market faces significant headwinds. The exorbitant cost of novel therapies, particularly immunotherapies and monoclonal antibodies, limits access in low-and-middle-income countries. Additionally, the complex regulatory landscape for drug approval and the stringent clinical trial requirements often delay the market entry of promising candidates. Side effects associated with high-dose chemotherapy and radiation also remain a concern, leading to patient non-compliance or the need for extensive supportive care, which further increases the total cost of treatment.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Specialized Oncology Drugs | -1.5% | Global (High in Emerging Markets) | 2025–2034 |
| Stringent Regulatory Approval Cycles | -0.8% | EU and North America | 2025–2029 |
Bone Cancer Treatment Market Opportunities Analysis
The market is ripe with opportunities for expansion, particularly through the development of biosimilars which can provide more affordable alternatives to expensive biologics. There is also a burgeoning opportunity in the application of 3D printing for customized bone implants used in reconstructive surgeries following tumor excision. Furthermore, expanding healthcare infrastructure in the BRICS nations offers a largely untapped patient population that is increasingly seeking modern oncology solutions. Tele-oncology and remote monitoring services also present new avenues for market players to enhance patient engagement and treatment adherence.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Biosimilars Development for Bone Cancer | +1.7% | Asia-Pacific and Latin America | 2026–2034 |
| 3D Printing in Reconstructive Surgery | +1.1% | Germany, USA, Japan | 2028–2034 |
Bone Cancer Treatment Market Challenges Impact Analysis
Addressing the challenges within the Bone Cancer Treatment market requires a multifaceted approach to overcome scientific and logistical hurdles. The rarity of primary bone cancers makes it difficult to recruit large patient cohorts for clinical trials, leading to prolonged development timelines. Furthermore, the development of multi-drug resistance in advanced-stage patients continues to be a major clinical challenge. Logistical issues, such as the cold-chain requirements for biologics and the need for specialized medical personnel to administer advanced therapies, also restrict the availability of treatment in remote or underdeveloped regions.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Patient Recruitment for Rare Cancer Trials | -0.7% | Global | 2025–2034 |
| Development of Drug Resistance | -1.0% | Global | 2025–2034 |
Bone Cancer Treatment Market - Updated Report Scope
This report provides a comprehensive examination of the Bone Cancer Treatment market, encompassing historical data, current market sizing, and future projections. It analyzes the clinical landscape, technological breakthroughs, and the shifting regulatory environment that governs the approval of oncology therapeutics. The scope includes a detailed evaluation of primary bone cancers like osteosarcoma and chondrosarcoma, as well as secondary metastatic bone cancers, providing stakeholders with actionable insights into the competitive landscape and regional growth pockets.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.73 Billion |
| Market Forecast in 2034 | USD 3.15 Billion |
| Growth Rate | 6.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Amgen Inc., Bristol-Myers Squibb Company, Novartis AG, Pfizer Inc., F. Hoffmann-La Roche Ltd, Eli Lilly and Company, Bayer AG, Johnson & Johnson Services Inc., Takeda Pharmaceutical Company Limited, Merck & Co. Inc., AstraZeneca, Celgene Corporation (BMS), Genzyme (Sanofi), Teva Pharmaceutical Industries Ltd., Medtronic, Stryker, Zimmer Biomet, Smith & Nephew |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Bone Cancer Treatment market reveals a diverse landscape where treatment modalities are chosen based on the histological type and stage of the malignancy. Osteosarcoma remains the most prevalent primary bone cancer, particularly in the pediatric and adolescent demographic, driving the demand for specialized chemotherapy protocols. Chondrosarcoma, often resistant to chemotherapy, drives the surgical and radiation therapy segments. The rise of targeted therapy is a defining feature of modern segmentation, as drugs targeting specific proteins or genes become the standard of care for refractory cases. The hospital segment remains the dominant end-user, but there is a clear trend toward outpatient care for long-term therapy administration.
- By Type:
- Osteosarcoma (Leading segment in pediatric cases)
- Ewing Sarcoma (Highly aggressive, driving research in immunotherapy)
- Chondrosarcoma (Dominant in older populations, surgery-focused)
- Chordoma and Others (Rare subtypes with specialized orphan drug pipelines)
- By Treatment:
- Chemotherapy (Traditional backbone of treatment)
- Targeted Therapy (Focus on kinase inhibitors and monoclonal antibodies)
- Immunotherapy (Checkpoint inhibitors and CAR-T cell exploration)
- Radiation Therapy (Proton therapy and external beam radiation)
- Surgery (Limb-salvage and reconstructive procedures)
- By End-User:
- Hospitals (Comprehensive care and surgical centers)
- Specialty Clinics (Focused on chemotherapy and radiation)
- Academic & Research Institutes (Clinical trial hubs)
Regional Highlights
- North America: Currently holds the largest market share (approx. 40%) due to a robust healthcare infrastructure, high awareness, and rapid adoption of novel FDA-approved therapies.
- Europe: The second-largest market, characterized by strong governmental support for oncology research and a well-established regulatory framework via the EMA.
- Asia-Pacific: Anticipated to be the fastest-growing region with a CAGR of over 8%, driven by massive healthcare investments in China, India, and Southeast Asia.
- Latin America: Growing at a steady pace as healthcare access improves in Brazil and Mexico, with a focus on generic oncology drugs.
- Middle East & Africa: Emerging market with growing potential in medical tourism and increased public health focus on cancer screening.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Bone Cancer Treatment Market.- Amgen Inc.
- Bristol-Myers Squibb Company
- Novartis AG
- Pfizer Inc.
- F. Hoffmann-La Roche Ltd
- Eli Lilly and Company
- Bayer AG
- Johnson & Johnson Services Inc.
- Takeda Pharmaceutical Company Limited
- Merck & Co. Inc.
- AstraZeneca
- Celgene Corporation
- Genzyme (Sanofi)
- Teva Pharmaceutical Industries Ltd.
- Medtronic
- Stryker
- Zimmer Biomet
- Smith & Nephew
- Eisai Co., Ltd.
- Kyowa Kirin Co., Ltd.
Frequently Asked Questions
What is the current market size of the Bone Cancer Treatment industry?
As of 2026, the market is estimated at USD 1.85 Billion and is expected to grow significantly due to advancements in immunotherapy and a rising incidence of metastatic cases.
Which treatment type is expected to see the fastest growth?
Targeted therapy and immunotherapy are expected to witness the highest growth rates as they offer better efficacy and lower toxicity compared to traditional chemotherapy.
Who are the leading players in the Bone Cancer Treatment market?
Major players include global pharmaceutical leaders such as Amgen, Novartis, Pfizer, and Roche, alongside orthopedic specialists like Stryker and Zimmer Biomet.
What are the primary drivers for this market?
Key drivers include the aging global population, increased incidence of primary and secondary bone cancers, and the development of breakthrough orphan drugs.
Which region holds the largest market share?
North America currently dominates the market, followed by Europe, due to high healthcare spending and the presence of advanced medical facilities.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
