Lung Cancer Therapeutics Market
Lung Cancer Therapeutics Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711041 | Published On : October 01, 2026 |
Format : 


 | Author : Erika Grotto
Lung Cancer Therapeutics Market Size
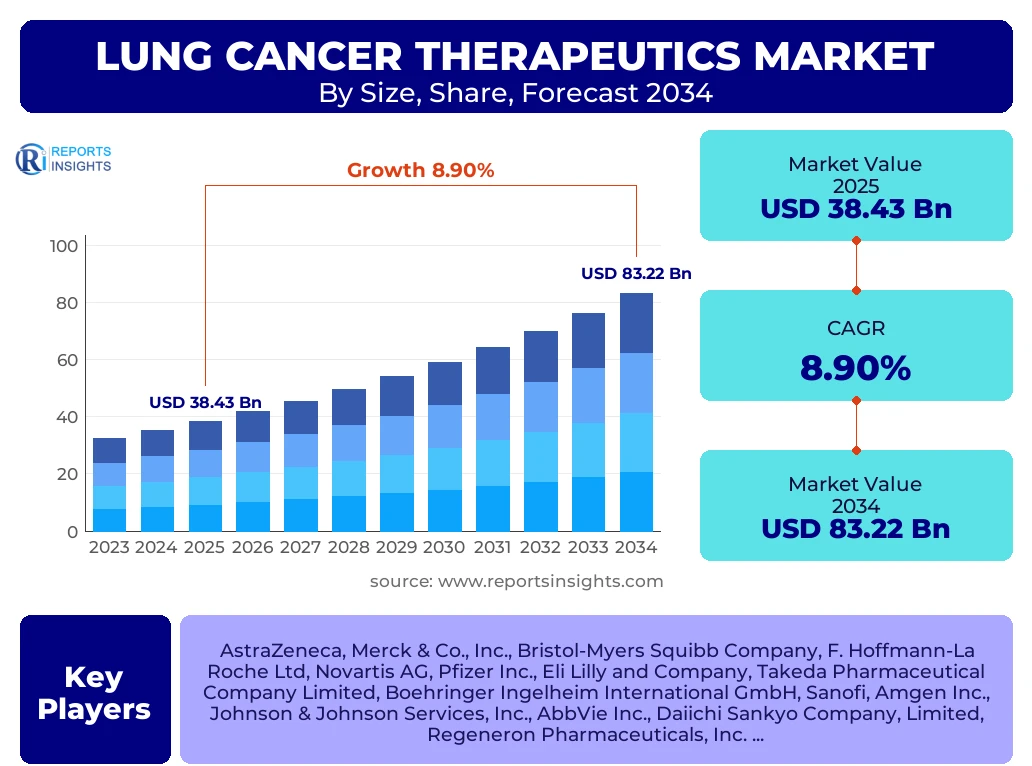
According to Reports Insights Consulting Pvt Ltd, The Lung Cancer Therapeutics Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.9% between 2026 and 2034. The market is estimated at USD 41.85 Billion in 2026 and is projected to reach USD 83.22 Billion by the end of the forecast period in 2034.
Key Lung Cancer Therapeutics Market Trends & Insights
The global lung cancer therapeutics landscape is undergoing a paradigm shift from traditional cytotoxic chemotherapy toward high-precision oncology and multifaceted immunotherapy regimens. Strategic analysis reveals that patient outcomes are increasingly tied to molecular profiling, which allows for the deployment of targeted inhibitors and immune checkpoint blockers. Research indicates that the integration of Artificial Intelligence (AI) in clinical decision-making and the rise of liquid biopsies for real-time monitoring are the primary catalysts reshaping the competitive environment across North America, Europe, and Asia-Pacific.
- Largest Region: North America remains the dominant regional market due to high healthcare expenditure, early adoption of novel biologics, and a robust pipeline of late-stage clinical trials.
- Fastest Growing Region: Asia-Pacific is anticipated to exhibit the highest CAGR during the forecast period, driven by increasing tobacco consumption in emerging economies, improving diagnostic infrastructure, and supportive government initiatives for affordable oncology care.
- Largest Segment: Non-Small Cell Lung Cancer (NSCLC) represents the largest market share by disease type, accounting for approximately 85% of all lung cancer cases globally.
- Dominant Therapy: Targeted therapy currently leads the market in terms of value, owing to the high cost of specialized kinase inhibitors and their efficacy in patients with specific genetic mutations such as EGFR, ALK, and ROS1.
Key Takeaways Lung Cancer Therapeutics Market Size & Forecast
The trajectory of the lung cancer therapeutics market is defined by a significant transition toward personalized medicine and combination therapies. Stakeholders are focusing on overcoming drug resistance and expanding the use of immunotherapy in early-stage disease settings. The market forecast reflects a stable upward trend as the global burden of lung cancer persists, necessitating advanced therapeutic interventions that offer both improved survival rates and better quality of life for patients across various demographics.
- Prevalence Impact: Lung cancer remains the leading cause of cancer-related mortality worldwide, sustaining a constant demand for innovative therapeutic solutions.
- Strategic Collaborations: Key players are increasingly engaging in strategic mergers and licensing agreements to bolster their oncology portfolios, particularly in the realm of Antibody-Drug Conjugates (ADCs).
- Regulatory Momentum: Frequent FDA and EMA approvals for breakthrough therapies, including orphan drug designations, are significantly shortening the time-to-market for high-impact drugs.
- Emergence of Biosimilars: The market is witnessing the entry of biosimilars for blockbuster biologics, which is expected to enhance treatment accessibility while intensifying price competition.
Lung Cancer Therapeutics Market Drivers Analysis
The primary driver for the lung cancer therapeutics market is the rapid advancement in genomic testing and molecular diagnostics. By identifying specific genetic alterations, clinicians can prescribe targeted therapies that offer superior efficacy and lower toxicity compared to traditional treatments. Furthermore, the increasing geriatric population worldwide is a critical factor, as lung cancer incidence rises significantly with age. The synergy between pharmaceutical innovation and supportive regulatory frameworks is accelerating the availability of next-generation treatments.
Additionally, the rising awareness regarding early screening programs is resulting in higher detection rates at manageable stages, subsequently increasing the patient pool seeking therapeutic intervention. The shift toward outpatient care and home-based administration of certain oncology drugs is also contributing to market growth by improving patient adherence and reducing the burden on healthcare facilities. The heavy investment in R&D by major pharmaceutical entities ensures a steady stream of first-in-class drugs entering the market.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Advancements in Precision Medicine | +3.2% | Global (Strongest in US & Germany) | 2025 - 2034 |
| Rising Prevalence of Smoking and Pollution | +2.5% | Asia-Pacific & Middle East | 2025 - 2034 |
| Expansion of Immunotherapy Indications | +2.1% | North America & Europe | 2026 - 2030 |
| Favorable Reimbursement Policies | +1.1% | Europe & North America | 2025 - 2034 |
Lung Cancer Therapeutics Market Restraints Analysis
Despite the positive growth outlook, the market faces significant restraints, primarily the exorbitant cost of advanced therapies. High-priced immunotherapies and targeted drugs often place a heavy financial burden on patients and healthcare systems, particularly in low-to-middle-income countries where insurance coverage is limited. This "financial toxicity" can restrict market penetration and lead to disparities in treatment access. Regulatory complexities and the stringent requirements for clinical trial data also pose hurdles for the rapid commercialization of new molecules.
Another major restraint is the development of multi-drug resistance in lung cancer cells. Patients often experience relapses as the tumor evolves to bypass the therapeutic mechanisms of current drugs, necessitating constant and expensive cycles of new drug development. Moreover, the adverse side effects associated with certain therapies, such as immune-related adverse events (irAEs) in immunotherapy, can lead to treatment discontinuation or the need for secondary medical management, impacting the overall market growth potential.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Treatment | -1.8% | Latin America & Africa | 2025 - 2034 |
| Development of Drug Resistance | -1.2% | Global | 2026 - 2034 |
| Stringent Regulatory Approval Cycles | -0.9% | European Union & Japan | 2025 - 2030 |
Lung Cancer Therapeutics Market Opportunities Analysis
The emergence of Antibody-Drug Conjugates (ADCs) represents one of the most promising opportunities in the lung cancer therapeutics market. These "biological missiles" deliver potent cytotoxic agents directly to cancer cells, minimizing damage to healthy tissues and offering a new line of defense for patients who have failed prior treatments. Furthermore, the integration of real-world evidence (RWE) in clinical development is allowing companies to optimize drug performance and gain faster regulatory approvals for expanded indications.
Expansion into emerging markets provides a massive untapped opportunity. As healthcare infrastructure improves in countries like India, Brazil, and China, the demand for sophisticated oncology drugs is expected to surge. Strategic partnerships between multinational pharmaceutical companies and local players for drug distribution and manufacturing can facilitate market entry and optimize costs. Additionally, the development of combination therapies—combining immunotherapy with targeted agents or radiation—is a growing field that promises to enhance survival outcomes and open new revenue streams.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Antibody-Drug Conjugates (ADCs) | +2.8% | United States, Japan, & China | 2026 - 2034 |
| Growth in Medical Tourism & Emerging Infrastructure | +1.5% | India & Southeast Asia | 2027 - 2034 |
| Personalized Cancer Vaccines | +1.2% | Global (Research focus in Germany) | 2028 - 2034 |
Lung Cancer Therapeutics Market Challenges Impact Analysis
The lung cancer therapeutics market is challenged by the high failure rate of oncology drugs in clinical trials. Oncology has one of the lowest success rates from Phase I to FDA approval, which translates to high R&D risks and sunk costs for pharmaceutical companies. Additionally, the heterogeneity of lung cancer tumors makes it difficult to develop a universal therapeutic approach, requiring high levels of customization that complicate manufacturing and supply chain logistics.
Geopolitical tensions and trade disruptions also pose a challenge to the global supply of essential APIs (Active Pharmaceutical Ingredients) and biologics. Furthermore, the increasing pressure from governments and healthcare payers for value-based pricing models is forcing companies to demonstrate significant clinical benefits to justify premium pricing. This transition requires extensive comparative effectiveness research, which adds to the overall cost and time of drug development.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Clinical Trial Failure Rates | -1.5% | Global | 2025 - 2034 |
| Supply Chain Vulnerabilities | -0.7% | APAC & North America | 2025 - 2028 |
| Complexity of Tumor Heterogeneity | -1.1% | Global | 2025 - 2034 |
Lung Cancer Therapeutics Market - Updated Report Scope
This comprehensive report provides an in-depth analysis of the global lung cancer therapeutics market, covering technological advancements, regulatory landscapes, and competitive dynamics. The scope extends across various treatment modalities and cancer types, offering detailed forecasts and strategic recommendations for stakeholders aiming to capitalize on emerging trends and mitigate potential risks in the oncology sector.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 38.43 Billion |
| Market Forecast in 2034 | USD 83.22 Billion |
| Growth Rate | 8.9% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | AstraZeneca, Merck & Co., Inc., Bristol-Myers Squibb Company, F. Hoffmann-La Roche Ltd, Novartis AG, Pfizer Inc., Eli Lilly and Company, Takeda Pharmaceutical Company Limited, Boehringer Ingelheim International GmbH, Sanofi, Amgen Inc., Johnson & Johnson Services, Inc., AbbVie Inc., Daiichi Sankyo Company, Limited, Regeneron Pharmaceuticals, Inc., Merck KGaA, Bayer AG, GSK plc, Eisai Co., Ltd., Beigene. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the lung cancer therapeutics market is primarily driven by the histological classification of the disease and the specific molecular drivers present in the tumor. Non-Small Cell Lung Cancer (NSCLC) remains the dominant segment due to its high prevalence and the availability of a wide range of targeted and immune-based therapies. Small Cell Lung Cancer (SCLC), though less common, is seeing increased research activity in the immunotherapy space after decades of limited innovation.
- By Type:
- Non-Small Cell Lung Cancer (NSCLC): Includes Adenocarcinoma, Squamous cell carcinoma, and Large cell carcinoma.
- Small Cell Lung Cancer (SCLC): Characterized by rapid growth and early metastasis, often treated with chemotherapy and immunotherapy combinations.
- By Treatment Modality:
- Targeted Therapy: Focused on specific mutations such as EGFR, ALK, BRAF, and KRAS.
- Immunotherapy: Utilizing checkpoint inhibitors like Pembrolizumab, Nivolumab, and Atezolizumab.
- Chemotherapy: Often used as a foundational treatment or in combination with newer agents.
- Radiation Therapy: Essential for localized disease management and palliative care.
- By Distribution Channel:
- Hospital Pharmacies: Leading channel due to the requirement for intravenous administration and specialized monitoring.
- Retail Pharmacies: Increasing share for oral targeted therapies.
- Online Pharmacies: Growing segment driven by digital health adoption and convenience.
Regional Highlights
- North America: The largest market share holder, driven by advanced diagnostic infrastructure, high healthcare spending (approx. 18% of GDP in the US), and the presence of major pharmaceutical headquarters. The region leads in the adoption of immunotherapy and molecularly targeted agents.
- Europe: The second-largest market, characterized by centralized healthcare systems and strong government support for cancer research. Countries like Germany, France, and the UK are at the forefront of implementing standardized NGS testing for lung cancer patients.
- Asia-Pacific: The fastest-growing region. Rapidly aging populations in Japan and China, coupled with rising pollution levels and tobacco use, are driving incidence rates. The market is also benefiting from the expansion of medical insurance and the presence of major generic and biosimilar manufacturers.
- Latin America & MEA: These regions show steady growth potential as healthcare access expands. While currently limited by economic volatility and infrastructure gaps, increasing focus on public health initiatives is expected to boost therapeutic uptake over the decade.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Lung Cancer Therapeutics Market.- AstraZeneca
- Merck & Co., Inc.
- Bristol-Myers Squibb Company
- F. Hoffmann-La Roche Ltd
- Novartis AG
- Pfizer Inc.
- Eli Lilly and Company
- Takeda Pharmaceutical Company Limited
- Boehringer Ingelheim International GmbH
- Sanofi
- Amgen Inc.
- Johnson & Johnson Services, Inc.
- AbbVie Inc.
- Daiichi Sankyo Company, Limited
- Regeneron Pharmaceuticals, Inc.
- Merck KGaA
- Bayer AG
- GSK plc
- Eisai Co., Ltd.
- Beigene
Frequently Asked Questions
What is the projected market size of the Lung Cancer Therapeutics Market by 2034?
The global lung cancer therapeutics market is projected to reach approximately USD 83.22 Billion by 2034, growing at a CAGR of 8.9% from 2026 onwards.
Which type of lung cancer holds the largest market share?
Non-Small Cell Lung Cancer (NSCLC) holds the largest market share, accounting for about 85% of all lung cancer cases and driving the majority of therapeutic demand.
What are the leading therapeutic classes in the market?
Targeted therapy and Immunotherapy (Checkpoint Inhibitors) are the leading therapeutic classes, significantly outpacing traditional chemotherapy in terms of revenue growth and patient outcomes.
Which region is expected to grow the fastest during the forecast period?
The Asia-Pacific region is expected to be the fastest-growing market due to increasing cancer incidence, improving healthcare access, and rising pharmaceutical investments in the region.
What are the main challenges facing the lung cancer therapeutics market?
Key challenges include the high cost of treatment, development of drug resistance in tumors, and high clinical trial failure rates, which impact both patient access and pharmaceutical profitability.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted