Dental Laboratories Market
Dental Laboratories Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711178 | Published On : October 15, 2026 |
Format : 


 | Author : Erika Grotto
Dental Laboratories Market Size
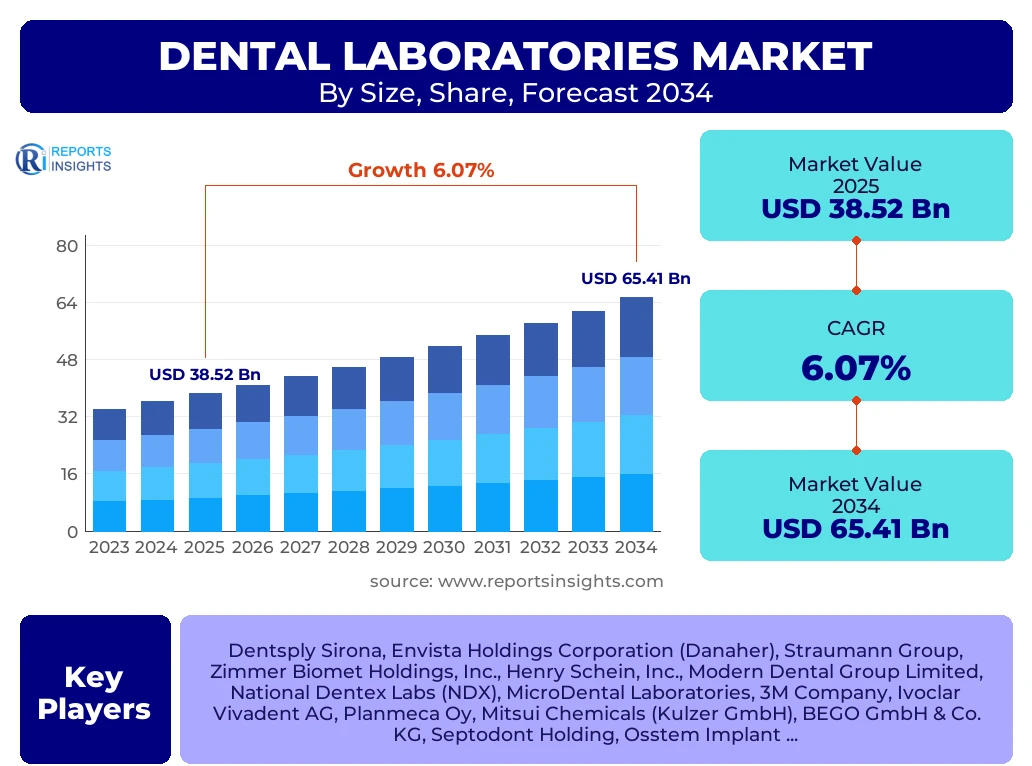
According to Reports Insights Consulting Pvt Ltd, The Dental Laboratories Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.07% between 2025 and 2034. The market is estimated at USD 41.25 Billion in 2026 and is projected to reach USD 65.41 Billion by the end of the forecast period in 2034.
Key Dental Laboratories Market Trends & Insights
The dental laboratories market is undergoing a significant paradigm shift driven by the rapid integration of digital workflows and additive manufacturing technologies. Traditionally a craft-based industry relying on manual wax-ups and casting, the modern dental lab is now a high-tech center utilizing CAD/CAM (Computer-Aided Design and Computer-Aided Manufacturing) systems and high-precision 3D printing. These advancements have drastically reduced turnaround times for prosthetics while simultaneously increasing the accuracy and biocompatibility of dental restorations. Competitive benchmarking indicates that labs investing in open-architecture digital systems are gaining a significant edge over traditional counterparts by offering more diverse product portfolios, including complex implant-supported bars and highly aesthetic monolithic zirconia crowns. Furthermore, the rising demand for cosmetic dentistry and clear aligner therapy is pushing laboratories to expand their specialized orthodontic and aesthetic service lines.
- Largest Region: North America remains the dominant market owing to high per capita dental expenditure and the early adoption of advanced digital dentistry.
- Fastest Growing Region: Asia-Pacific is expected to witness the highest CAGR due to the expanding geriatric population and increasing dental tourism in countries like India and Thailand.
- Largest Segment: The Restorative segment, specifically crowns and bridges, continues to hold the largest market share by value.
- Leading Material: Zirconia and glass-ceramics are rapidly replacing traditional porcelain-fused-to-metal (PFM) due to superior aesthetics and durability.
Key Takeaways Dental Laboratories Market Size & Forecast
The global dental laboratories market is characterized by a high degree of fragmentation, although significant consolidation is occurring in mature markets. Stakeholders are increasingly focused on the total cost of ownership for digital equipment and the ROI associated with automated milling centers. The forecast period anticipates a steady rise in the volume of dental implants and aesthetic procedures, supported by an aging global population that requires extensive restorative care. Additionally, the shift toward chairside milling by some dental clinics presents a competitive challenge to traditional labs, forcing them to pivot toward more complex, high-value customized solutions that cannot be produced in-office. Analysis suggests that the integration of Artificial Intelligence (AI) in design software will be the next major frontier, further optimizing lab efficiency and reducing the margin of human error in prosthetic design.
- North America Market Share: Holds approximately 38% of the global market share as of 2025.
- Implants Growth: The dental implants segment is projected to be the most lucrative sub-segment during the forecast period.
- Consolidation Trend: Large-scale lab networks are acquiring boutique labs to create "super-labs" with centralized digital production hubs.
- Labor Dynamics: A shortage of skilled dental technicians is driving the urgent adoption of automation and robotic milling.
Dental Laboratories Market Drivers Analysis
The primary driver of the dental laboratories market is the globally aging population, which is susceptible to tooth loss and periodontal diseases, necessitating crowns, bridges, and dentures. As life expectancy increases, the demand for long-term restorative solutions remains high. Furthermore, the rising awareness regarding oral hygiene and the increasing prevalence of dental caries in developing economies are significantly boosting procedure volumes. The cosmetic dentistry boom, fueled by social media influence and increased disposable income, has led to a surge in elective procedures such as veneers and clear aligners.
Technological innovation acts as a secondary but powerful driver. The transition from physical impressions to intraoral scanning has streamlined the communication between dentists and labs, reducing the likelihood of remakes and improving patient comfort. This digital connectivity allows for a more efficient supply chain and enables labs to service a broader geographic area without the logistical constraints of physical mold shipping. Moreover, government initiatives and dental insurance expansions in various regions are making specialized dental care more accessible to the middle-class population.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Digitalization & CAD/CAM Integration | +1.8% | Global (Strongest in Europe/US) | 2025-2034 |
| Aging Global Population | +1.5% | Japan, Germany, USA | 2025-2034 |
| Rising Demand for Cosmetic Dentistry | +1.2% | Brazil, UAE, South Korea | 2026-2032 |
| Expansion of Dental Insurance Coverage | +0.9% | India, China, USA | 2025-2030 |
Dental Laboratories Market Restraints Analysis
High capital investment requirements for advanced digital equipment remain a significant restraint, particularly for small and medium-sized laboratories. The cost of high-end five-axis milling machines, industrial-grade 3D printers, and proprietary design software can be prohibitive, creating a barrier to entry and limiting the modernization of traditional labs. This often leads to a digital divide where only large-scale laboratories can leverage the efficiencies of scale, while smaller labs struggle to maintain competitive pricing.
Furthermore, the industry faces a critical shortage of skilled dental technicians who are proficient in both traditional morphology and digital design. The learning curve for new software and the maintenance of complex machinery add to the operational overhead. Regulatory hurdles and stringent quality standards for dental prosthetic materials, particularly in the European Union under the Medical Device Regulation (MDR), also increase compliance costs and time-to-market for new materials and products.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Capital Expenditure | -0.7% | Emerging Markets (LAMEA) | 2025-2028 |
| Scarcity of Skilled Technicians | -0.5% | North America & Europe | 2025-2034 |
| Strict Regulatory Compliance (MDR) | -0.4% | European Union | 2025-2027 |
Dental Laboratories Market Opportunities Analysis
The emergence of Artificial Intelligence (AI) in dental design presents a transformative opportunity for laboratories to maximize productivity. AI algorithms can now automate the initial design of crowns and aligners by analyzing thousands of scans to predict the optimal anatomical shape, which significantly reduces the time spent on manual design tweaks. This allows labs to scale their production without a proportional increase in headcount. Additionally, the rise of "Teledentistry" and direct-to-consumer models for orthodontic aligners opens new revenue streams for labs that can partner with tech-driven dental platforms.
Another significant opportunity lies in the development of biocompatible 3D printing resins for permanent restorations. While 3D printing is currently dominated by temporary prosthetics and models, the approval of materials for long-term use in the mouth will revolutionize the cost structure of restorative dentistry. Developing regions in Southeast Asia and Latin America also offer untapped potential, as rising economic stability leads to increased healthcare spending and a shift toward more sophisticated dental treatments beyond basic extractions.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| AI-Driven Design Automation | +1.4% | Global | 2027-2034 |
| Permanent 3D Printed Restorations | +1.1% | Germany, USA, Japan | 2026-2034 |
| Market Expansion in APAC | +1.3% | Vietnam, Indonesia, India | 2025-2034 |
Dental Laboratories Market Challenges Impact Analysis
The increasing prevalence of chairside CAD/CAM systems in dental clinics is a direct challenge to the traditional lab business model. Dentists can now scan, design, and mill simple restorations like single-unit crowns in a single visit, bypassing the laboratory entirely for basic cases. This forces laboratories to focus on more complex, multi-unit, or high-aesthetic cases that require the specialized expertise of a dental technician, effectively shrinking the market for "bread and butter" lab work. Furthermore, the volatility of raw material prices, particularly for precious metals used in alloys, creates pricing instability.
Cybersecurity is also emerging as a critical challenge as laboratories become more digitally interconnected. The exchange of sensitive patient data and proprietary design files between clinics and labs via cloud platforms makes the industry a target for data breaches. Ensuring HIPAA and GDPR compliance in a digital-first workflow requires ongoing investment in IT infrastructure and security protocols, which can be a burden for many lab owners.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Competition from Chairside Milling | -1.1% | Developed Markets | 2025-2034 |
| Raw Material Price Volatility | -0.6% | Global | Ongoing |
| Data Security & Privacy Risks | -0.3% | USA, Europe | 2025-2034 |
Dental Laboratories Market - Updated Report Scope
This report provides a comprehensive quantitative and qualitative analysis of the global dental laboratories industry, covering the evolution from analog to digital dental technologies. It encompasses market valuations, regional trends, and a detailed examination of the competitive landscape, including M&A activity and technological patent filings. The scope extends across various material types, equipment categories, and prosthetic applications to provide a 360-degree view of the sector's health and trajectory.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 38.52 Billion |
| Market Forecast in 2034 | USD 65.41 Billion |
| Growth Rate | 6.07% CAGR |
| Number of Pages | 268 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Dentsply Sirona, Envista Holdings Corporation (Danaher), Straumann Group, Zimmer Biomet Holdings, Inc., Henry Schein, Inc., Modern Dental Group Limited, National Dentex Labs (NDX), MicroDental Laboratories, 3M Company, Ivoclar Vivadent AG, Planmeca Oy, Mitsui Chemicals (Kulzer GmbH), BEGO GmbH & Co. KG, Septodont Holding, Osstem Implant, Kuraray Noritake Dental Inc., VITA Zahnfabrik. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The dental laboratories market is segmented based on product type, material, and equipment, each reflecting different growth dynamics. The restorative segment is the primary revenue generator, supported by the ongoing need for crowns and bridges. However, the orthodontic segment is experiencing the fastest growth, largely due to the explosive demand for clear aligners and the shift toward digital treatment planning. Material-wise, the industry is seeing a massive transition away from porcelain-fused-to-metal (PFM) toward all-ceramic materials like Zirconia and Lithium Disilicate, which offer superior aesthetic properties and minimize the risk of allergic reactions. The equipment segment is dominated by CAD/CAM systems, as labs prioritize digital integration to increase throughput and precision.
- By Product:
- Restorative: Crowns, Bridges, Inlays, and Onlays.
- Orthodontic: Clear Aligners, Traditional Braces, and Retainers.
- Endodontic: Files, Obturation materials, and related lab services.
- Implants: Abutments and Implant-supported prosthetics.
- Oral Care: Customized mouthguards and whitening trays.
- By Material:
- All-Ceramics: High-translucency Zirconia and Glass Ceramics.
- Metal-Ceramics: Traditional PFM restorations.
- Metals: Non-precious and precious alloys for frameworks.
- Plastics/Polymers: High-performance polymers for dentures and 3D printing.
- By Equipment:
- Milling Machines: 4-axis and 5-axis dry/wet mills.
- 3D Printers: SLA, DLP, and LCD printers for dental applications.
- Scanners: Desktop lab scanners and intraoral scanner support.
- Furnaces: Sintering, porcelain, and casting furnaces.
Regional Highlights
- North America: The largest market share holder, driven by a highly developed dental infrastructure, high adoption of digital dentistry, and a strong presence of major market players. The US market is characterized by significant laboratory consolidation and a high demand for premium restorative materials.
- Europe: A mature market with a strong emphasis on quality and aesthetics. Germany and Italy are key hubs for dental laboratory equipment and material innovation. The region faces challenges from strict medical device regulations but remains a leader in high-end prosthetic manufacturing.
- Asia-Pacific: The fastest-growing region, led by China, India, and South Korea. Growth is fueled by increasing dental awareness, a massive population base, and the rise of dental tourism. Many large-scale laboratory groups are setting up production facilities in this region to leverage lower labor costs and high demand.
- Latin America: Brazil is a major player in this region, particularly in the cosmetic dentistry and implantology sectors. The market is growing steadily as middle-class disposable income increases.
- Middle East & Africa: A developing market with significant growth potential in urban centers like Dubai and Riyadh, where there is a growing demand for advanced aesthetic dental procedures and high-quality laboratory services.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Dental Laboratories Market.- Dentsply Sirona
- Envista Holdings Corporation
- Straumann Group
- Zimmer Biomet Holdings, Inc.
- Henry Schein, Inc.
- Modern Dental Group Limited
- National Dentex Labs
- MicroDental Laboratories
- 3M Company
- Ivoclar Vivadent AG
- Planmeca Oy
- Mitsui Chemicals (Kulzer GmbH)
- BEGO GmbH & Co. KG
- Septodont Holding
- Osstem Implant
- Kuraray Noritake Dental Inc.
- VITA Zahnfabrik
- GC Corporation
- Shofu Inc.
- Amann Girrbach AG
Frequently Asked Questions
What is the projected market size of the Dental Laboratories Market by 2034?
The global Dental Laboratories Market is projected to reach approximately USD 65.41 Billion by 2034, growing at a CAGR of 6.07% from 2025.
What are the main factors driving growth in this market?
The primary drivers include an aging global population requiring restorative care, the rapid adoption of digital CAD/CAM technologies, and a rising demand for cosmetic dentistry and clear aligners.
Which region is expected to show the highest growth rate?
The Asia-Pacific region is expected to be the fastest-growing market due to increasing dental health awareness, expanding healthcare infrastructure, and rising disposable incomes in countries like China and India.
How is 3D printing impacting dental laboratories?
3D printing is revolutionizing the industry by enabling the rapid production of dental models, surgical guides, and temporary prosthetics with high precision, significantly reducing labor costs and production time.
Who are the leading players in the Dental Laboratories Market?
Top players include Dentsply Sirona, Envista Holdings, Straumann Group, Henry Schein, and Modern Dental Group, among others who lead in material and equipment innovation.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
