Prothrombin Complex Concentrate Market
Prothrombin Complex Concentrate Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711639 | Published On : November 10, 2026 |
Format : 


 | Author : Erika Grotto
Prothrombin Complex Concentrate Market Size
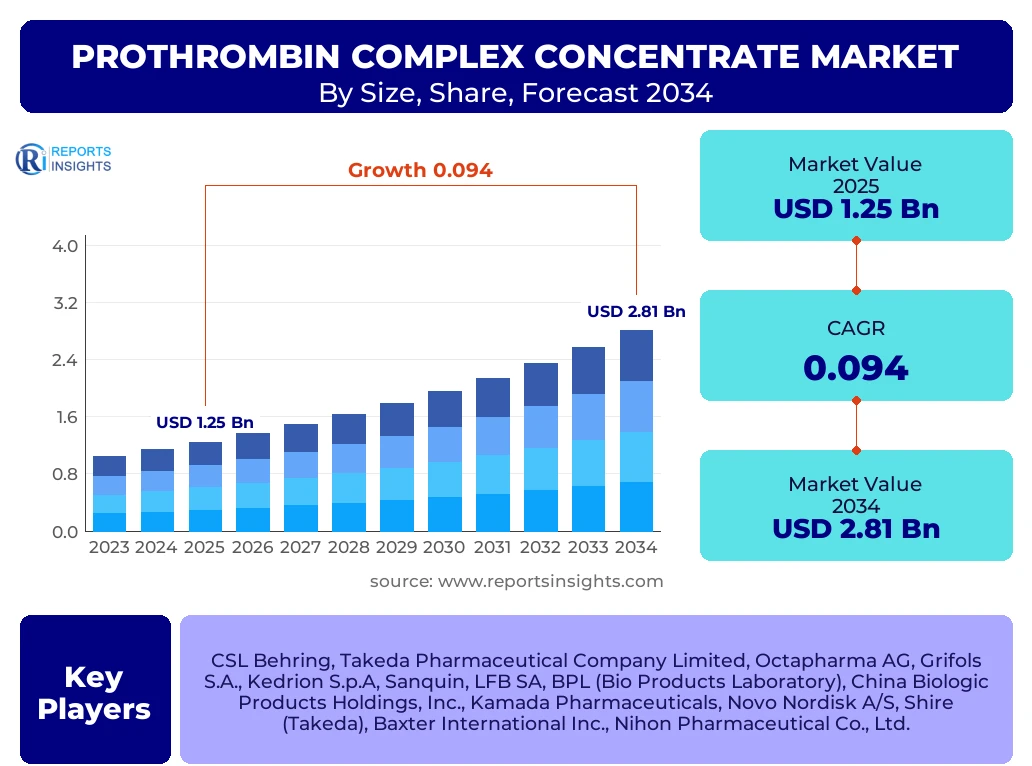
According to Reports Insights Consulting Pvt Ltd, The Prothrombin Complex Concentrate Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 9.4% between 2025 and 2034. The market is estimated at USD 1.37 Billion in 2026 and is projected to reach USD 2.81 Billion by the end of the forecast period in 2034.
Key Prothrombin Complex Concentrate Market Trends & Insights
The Prothrombin Complex Concentrate (PCC) market is undergoing a significant transition characterized by the increasing adoption of 4-factor PCC (4F-PCC) over traditional 3-factor variants. This shift is primarily driven by the clinical superiority of 4-factor concentrates in achieving rapid international normalized ratio (INR) reversal without the need for supplemental Factor VII. Research indicates that clinicians are increasingly prioritizing PCC over Fresh Frozen Plasma (FFP) due to the reduced risk of volume overload and faster administration times, which are critical in emergency trauma and intracranial hemorrhage scenarios. Furthermore, the integration of Point-of-Care (POC) coagulation testing in emergency departments is streamlining the utilization of PCC, allowing for more precise dosing and improved patient outcomes in acute bleeding management.
Another prominent trend is the geographical expansion of plasma fractionation facilities, particularly in the Asia-Pacific region. As healthcare infrastructure improves in emerging economies, there is a rising focus on self-sufficiency in blood-derived products. Strategic collaborations between global pharmaceutical leaders and regional health authorities are facilitating the localized production of PCC, thereby reducing logistics costs and improving availability. Additionally, the market is seeing a surge in clinical trials exploring the off-label use of PCC for reversing the effects of Direct Oral Anticoagulants (DOACs), such as Factor Xa inhibitors, which represents a substantial white-space opportunity for market participants.
- Largest Region: North America currently holds the largest market share, driven by advanced trauma care protocols and high awareness of anticoagulant reversal therapies.
- Fastest Growing Region: Asia-Pacific is expected to exhibit the highest CAGR due to increasing geriatric populations and expanding healthcare investments in China and India.
- Largest Segment: The 4-Factor Prothrombin Complex Concentrate segment dominates the market in terms of value share and clinical preference.
- Leading Application: Acquired Coagulation Factor Deficiency, particularly warfarin-related reversal, remains the primary revenue generator for the industry.
Key Takeaways Prothrombin Complex Concentrate Market Size & Forecast
The global outlook for the Prothrombin Complex Concentrate market remains highly positive, with robust growth expected across all major regional corridors. The forecast period highlights a critical juncture where the convergence of aging demographics and the rising prevalence of cardiovascular diseases will necessitate more frequent use of anticoagulant therapies, subsequently driving the demand for effective reversal agents. Stakeholders are focusing on optimizing the cost-effectiveness of PCC treatments to encourage broader adoption in secondary and tertiary care settings. Moreover, the shift toward personalized medicine is influencing the development of weight-based and individualized dosing regimens for PCC, enhancing safety profiles and reducing the incidence of thromboembolic complications.
- Dominant Market Position: The United States leads the global market, accounting for a significant portion of total revenue due to favorable reimbursement policies and high per-capita healthcare spending.
- Product Innovation: Continued R&D into lyophilized (freeze-dried) formulations is improving the shelf-life and storage flexibility of PCC, making it more viable for pre-hospital and emergency medical services (EMS) use.
- Strategic Mergers: The market is characterized by high consolidation, with the top five players controlling over 70% of the total market share, focusing on capacity expansion and plasma collection network optimization.
- Regulatory Influence: Stringent FDA and EMA guidelines regarding plasma-derived products ensure high safety standards but also act as a barrier to entry for smaller, regional manufacturers.
Prothrombin Complex Concentrate Market Drivers Analysis
The expansion of the PCC market is fundamentally underpinned by the rising incidence of chronic conditions requiring long-term anticoagulation therapy. As the global population ages, the prevalence of atrial fibrillation and venous thromboembolism is increasing, leading to a broader pool of patients managed on Vitamin K Antagonists (VKAs). When these patients experience major bleeding or require urgent surgery, PCC provides the fastest and most effective means of restoring hemostasis. Furthermore, the shift in clinical guidelines favoring PCC over FFP for urgent warfarin reversal is a powerful driver, as professional medical societies increasingly recognize the benefits of lower infusion volumes and faster correction of coagulopathy.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Prevalence of Atrial Fibrillation | +3.2% | Global (High in Europe/North America) | 2025 - 2034 |
| Shift from FFP to PCC in Trauma Protocols | +2.8% | North America & Western Europe | 2025 - 2030 |
| Increasing Geriatric Population | +2.1% | Japan, China, Germany | 2026 - 2034 |
| Technological Advancements in Plasma Fractionation | +1.3% | Asia-Pacific & Latin America | 2027 - 2034 |
Prothrombin Complex Concentrate Market Restraints Analysis
Despite its clinical benefits, the high cost of Prothrombin Complex Concentrate compared to alternative therapies like Vitamin K or Fresh Frozen Plasma remains a significant restraint, particularly in cost-sensitive healthcare markets. Budgetary constraints in public health systems can limit the stocking of 4-factor PCC in smaller community hospitals. Additionally, there are inherent risks associated with procoagulant therapy, specifically the potential for thromboembolic events such as deep vein thrombosis or myocardial infarction, which necessitates cautious administration and rigorous patient monitoring.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Treatment and Acquisition | -1.5% | Emerging Markets (India, SE Asia) | 2025 - 2034 |
| Risk of Thromboembolic Complications | -0.8% | Global | 2025 - 2034 |
| Strict Regulatory Approvals for Blood Products | -0.6% | European Union & USA | 2025 - 2030 |
Prothrombin Complex Concentrate Market Opportunities Analysis
The potential for PCC to serve as an "off-label" or novel reversal agent for non-vitamin K oral anticoagulants (NOACs) represents a massive growth opportunity. While specific reversal agents like idarucizumab and andexanet alfa have entered the market, their high cost and limited availability in many regions make PCC an attractive alternative for many clinicians. Furthermore, the expansion of emergency medical services and pre-hospital care units in developing nations provides a new channel for PCC distribution. Manufacturers can also explore the development of higher-concentration formulations that allow for even smaller infusion volumes, further differentiating their products in the acute care setting.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Usage in DOAC Reversal (Off-label Potential) | +2.4% | Global | 2026 - 2034 |
| Expansion into Pre-hospital/EMS Settings | +1.7% | North America & Europe | 2027 - 2034 |
| Untapped Potential in Emerging APAC Markets | +1.9% | China, India, Vietnam | 2025 - 2034 |
Prothrombin Complex Concentrate Market Challenges Impact Analysis
The primary challenge facing the PCC market is the volatility in the supply of source plasma. Since PCC is a plasma-derived medicinal product (PDMP), any disruption in the global plasma collection network—whether due to geopolitical instability, regulatory changes, or public health crises—can lead to immediate supply shortages and price fluctuations. Additionally, the market faces competition from recombinant Factor VIIa and newer, targeted reversal agents for specific anticoagulants. Ensuring consistent viral safety and protein purity while maintaining large-scale production efficiency requires continuous investment in sophisticated fractionation and purification technologies.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Vulnerability (Plasma Sourcing) | -1.2% | Global | 2025 - 2034 |
| Competition from Synthetic/Recombinant Alternatives | -0.9% | High-income Countries | 2026 - 2034 |
| Geopolitical Tensions Affecting Trade | -0.5% | Global | 2025 - 2030 |
Prothrombin Complex Concentrate Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the global Prothrombin Complex Concentrate market, spanning across various factor types, clinical applications, and end-user segments. It provides a granular look at the competitive landscape, identifying the market positions of key pharmaceutical entities and their strategic initiatives. The report also evaluates the impact of healthcare reforms, insurance coverage trends, and clinical guideline updates on the future trajectory of the PCC market. Through a combination of historical data analysis and forward-looking forecasting, this report offers stakeholders actionable insights into investment hotspots and emerging demand drivers.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.25 Billion |
| Market Forecast in 2034 | USD 2.81 Billion |
| Growth Rate | 9.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | CSL Behring, Takeda Pharmaceutical Company Limited, Octapharma AG, Grifols S.A., Kedrion S.p.A, Sanquin, LFB SA, BPL (Bio Products Laboratory), China Biologic Products Holdings, Inc., Kamada Pharmaceuticals, Novo Nordisk A/S, Shire (Takeda), Baxter International Inc., Nihon Pharmaceutical Co., Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Prothrombin Complex Concentrate market reflects the diverse clinical needs and the evolution of blood-product technology. By categorizing the market based on product type, application, and end-user, we gain a clear understanding of where the highest value resides. Currently, 4-factor PCC leads the market as it contains significant amounts of Factor VII, which is often deficient in patients on warfarin therapy, unlike 3-factor PCC which requires the addition of plasma or Factor VII for complete reversal. This efficiency makes 4-factor PCC the standard of care in North America and much of Europe.
Application-based segmentation reveals that acquired factor deficiency, particularly related to anticoagulant therapy, is the most common reason for PCC administration. However, the use of PCC in surgical settings—especially cardiac and orthopedic surgeries where heavy blood loss is expected—is a rapidly growing sub-segment. Hospitals remain the primary end-users, but the growing infrastructure of ambulatory surgery centers (ASCs) is beginning to capture a notable portion of the market as they handle more complex procedures requiring on-site hemostatic agents.
- By Product Type:
- 3-Factor Prothrombin Complex Concentrate
- 4-Factor Prothrombin Complex Concentrate
- By Application:
- Acquired Coagulation Factor Deficiency (Warfarin Reversal)
- Congenital Coagulation Factor Deficiency
- Trauma and Emergency Bleeding
- Perioperative Bleeding Management
- By End-User:
- Hospitals and Clinics
- Ambulatory Surgery Centers
- Blood Centers and Emergency Units
Regional Highlights
North America maintains a commanding lead in the global market, underpinned by a sophisticated healthcare system and rapid adoption of 4-factor PCC (Kcentra). The high cost of healthcare in the US, combined with comprehensive insurance coverage for emergency procedures, facilitates the use of expensive but efficient reversal agents. Furthermore, the presence of major industry players and a large number of clinical trials conducted in this region keep North America at the forefront of the PCC market.
Europe follows North America closely, with countries like Germany, France, and the UK exhibiting high usage rates for PCC in trauma care. The regulatory environment in Europe, governed by the EMA, has been supportive of PCC use for a wide range of indications. In the Asia-Pacific region, market growth is accelerating due to the modernization of hospital systems and a growing middle class that can afford advanced medical treatments. China and India are emerging as major hubs for plasma fractionation, which is expected to lower the cost of PCC and increase its penetration in these high-population markets.
- North America: Largest market share; highest adoption rate of 4-factor PCC; leading trauma care protocols.
- Europe: Mature market; strong presence of European-based fractionation leaders like Octapharma and Grifols.
- Asia-Pacific: Fastest growing region; rising geriatric population; significant investments in healthcare infrastructure.
- Latin America & MEA: Steady growth; increasing awareness of coagulopathy management; focus on reducing maternal mortality in trauma/surgery.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Prothrombin Complex Concentrate Market.- CSL Behring
- Takeda Pharmaceutical Company Limited
- Octapharma AG
- Grifols S.A.
- Kedrion S.p.A
- Sanquin
- LFB SA
- Bio Products Laboratory (BPL)
- China Biologic Products Holdings, Inc.
- Kamada Pharmaceuticals
- Nihon Pharmaceutical Co., Ltd.
- Biotest AG
- Baxter International Inc.
- Emergent BioSolutions
- Novo Nordisk A/S
Frequently Asked Questions
What is the primary difference between 3-factor and 4-factor PCC?
The primary difference lies in the concentration of Factor VII. 4-factor PCC contains significant amounts of Factor VII in addition to Factors II, IX, and X, along with Protein C and S. 3-factor PCC has low or negligible amounts of Factor VII and often requires the co-administration of FFP or recombinant Factor VIIa to achieve effective hemostasis in warfarin-treated patients.
Why is PCC preferred over Fresh Frozen Plasma (FFP) for urgent warfarin reversal?
PCC is preferred because it can be administered in a much smaller volume, reducing the risk of Transfusion-Associated Circulatory Overload (TACO). Additionally, PCC does not require blood group matching and can be reconstituted and infused much faster than FFP, which must be thawed, saving critical minutes in emergency situations.
What are the most common side effects associated with Prothrombin Complex Concentrate?
The most significant risk is the potential for thromboembolic events, such as stroke, pulmonary embolism, or deep vein thrombosis, because PCC introduces concentrated clotting factors into the blood. Other side effects may include headache, nausea, and in rare cases, hypersensitivity or allergic reactions.
How is the pricing of PCC determined in the global market?
PCC pricing is largely determined by the cost of plasma collection and the complexity of the fractionation process. Because it is a blood-derived product, costs are higher than synthetic drugs. Regional pricing also varies based on government procurement contracts, hospital purchasing volumes, and the level of local competition.
Can PCC be used for the reversal of Direct Oral Anticoagulants (DOACs)?
While specific agents like andexanet alfa are designed for Factor Xa inhibitors, PCC is frequently used "off-label" for DOAC reversal when specific agents are unavailable or too expensive. Clinical data suggests that high-dose 4-factor PCC can help restore hemostatic balance, though it is not yet the FDA-approved standard for all DOACs.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
