Oncology Nutrition Market
Oncology Nutrition Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711640 | Published On : November 10, 2026 |
Format : 


 | Author : Erika Grotto
Oncology Nutrition Market Size
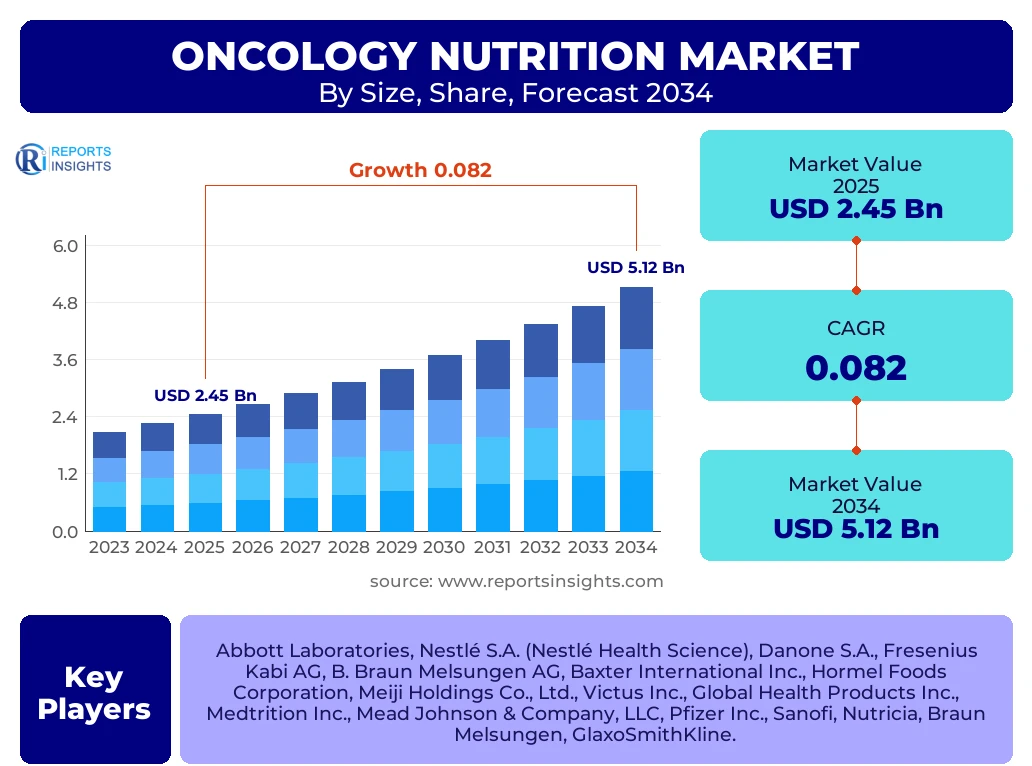
According to Reports Insights Consulting Pvt Ltd, The Oncology Nutrition Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.2% between 2025 and 2034. The market is estimated at USD 2.65 Billion in 2026 and is projected to reach USD 5.12 Billion by the end of the forecast period in 2034.
The oncology nutrition market serves as a critical pillar in the comprehensive care of cancer patients, addressing the pervasive issue of malnutrition and cachexia associated with various malignancies and their treatments. As clinical evidence continues to highlight the direct correlation between nutritional status and patient outcomes, including tolerance to chemotherapy and reduced hospital readmission rates, the demand for specialized formulas has surged. Stakeholders are increasingly focusing on medical foods that provide high protein, omega-3 fatty acids, and specific micronutrients tailored to the metabolic shifts occurring during oncological therapy.
The expansion of the market is further underpinned by the transition toward personalized medicine, where nutritional interventions are designed based on the specific type of cancer, the stage of the disease, and the individual metabolic profile of the patient. Advancements in enteral and parenteral delivery systems, coupled with a growing preference for home-based nutritional support, are reshaping the competitive landscape. With a rising global geriatric population more susceptible to cancer and a heightened focus on supportive care in emerging economies, the market is positioned for sustained long-term growth.
Key Oncology Nutrition Market Trends & Insights
The oncology nutrition landscape is currently undergoing a transformative phase driven by the integration of immunonutrition and digital health tracking. Current research suggests that pre-operative nutritional optimization significantly reduces post-surgical complications, leading to a higher adoption rate of specialized formulas in surgical oncology. Furthermore, there is a notable shift toward plant-based and organic clinical nutrition options as patients seek "cleaner" ingredient profiles even within medical-grade products. Competitive benchmarking reveals that leading companies are investing heavily in R&D to develop formulas that are not only nutritionally superior but also more palatable to patients suffering from taste alterations due to chemotherapy.
- Largest Region: North America remains the dominant region due to advanced healthcare infrastructure, high awareness regarding clinical nutrition, and favorable reimbursement policies.
- Fastest Growing Region: Asia-Pacific is expected to witness the highest CAGR, fueled by increasing healthcare expenditures, a rising incidence of cancer in populous nations like China and India, and expanding pharmaceutical distribution networks.
- Largest Segment by Share: The Head and Neck Cancer segment holds a significant market share as these patients frequently experience dysphagia and mechanical obstructions, necessitating specialized enteral nutrition.
- Leading Product Category: Standard Formulas continue to lead in volume, though Specialty Formulas designed for specific metabolic needs are the fastest-growing sub-segment in terms of value.
Key Takeaways Oncology Nutrition Market Size & Forecast
Market projections indicate a robust trajectory as oncologists increasingly incorporate registered dietitians into multidisciplinary care teams. The forecast period will likely see a convergence of biotechnology and nutrition, with the development of bioactive compounds that can mitigate the inflammatory responses triggered by tumors. Investors and stakeholders should note that while hospital-based sales remain the primary revenue stream, the online pharmacy and home-care segments are experiencing accelerated growth due to the convenience they offer to chronically ill patients. Strategic collaborations between nutritional companies and oncology centers are becoming a standard entry and expansion strategy in competitive markets.
- Prevalence Impact: The increasing global burden of cancer, with an estimated 20 million new cases annually, serves as the primary volume driver for nutritional interventions.
- Home-Care Growth: The shift toward outpatient cancer care is boosting the demand for easy-to-use enteral feeding pumps and shelf-stable nutritional supplements.
- Regulatory Influence: Stringent FDA and EFSA regulations regarding the labeling and clinical validation of medical foods are raising the barrier to entry, favoring established players with strong clinical trial portfolios.
- Segment Dominance: Enteral nutrition remains the preferred route over parenteral nutrition due to its lower cost and lower risk of infection, maintaining a dominant market position throughout the forecast period.
Oncology Nutrition Market Drivers Analysis
The primary driver for the oncology nutrition market is the rising global incidence of cancer, which necessitates supportive care to prevent muscle wasting and treatment interruptions. Additionally, the growing body of clinical evidence linking early nutritional intervention to improved survival rates is compelling healthcare providers to standardize nutritional screening for all newly diagnosed cancer patients.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Global Cancer Prevalence | +2.8% | Global | 2025 - 2034 |
| Advancements in Enteral Delivery Systems | +1.5% | North America & Europe | 2025 - 2030 |
| Increased Focus on Immunonutrition | +2.1% | Germany, Japan, USA | 2026 - 2034 |
| Growth in Home-Based Healthcare Services | +1.8% | UK, USA, Canada | 2025 - 2032 |
Oncology Nutrition Market Restraints Analysis
Despite the positive growth outlook, the market faces significant hurdles, particularly regarding the high cost of specialized medical foods which may not be fully covered by insurance in developing regions. Furthermore, the physiological side effects of chemotherapy, such as severe nausea and vomiting, can hinder the effective administration of oral and enteral nutrition, limiting the market's reach in specific patient cohorts.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Limited Reimbursement for Medical Foods | -1.2% | Latin America & Africa | 2025 - 2034 |
| High Cost of Specialty Formulations | -0.9% | India, Southeast Asia | 2025 - 2030 |
| Strict Regulatory Approval Processes | -0.7% | European Union | 2025 - 2034 |
Oncology Nutrition Market Opportunities Analysis
The integration of digital health and artificial intelligence presents a massive opportunity for personalizing oncology nutrition. AI-driven platforms can analyze a patient's caloric and protein needs in real-time, adjusting feeding schedules and formula types to match their treatment phase. Additionally, the expansion of clinical nutrition into emerging markets in Africa and Southeast Asia provides a relatively untapped consumer base for standard and affordable nutritional products.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Personalized AI-Driven Nutrition Plans | +2.3% | USA, South Korea | 2027 - 2034 |
| Expansion into Emerging Markets | +1.9% | China, Brazil, India | 2026 - 2034 |
| Development of Plant-Based Medical Foods | +1.4% | Western Europe | 2025 - 2030 |
Oncology Nutrition Market Challenges Impact Analysis
One of the most persistent challenges in this market is the lack of specialized training for healthcare professionals in clinical nutrition, which often leads to the under-diagnosis of malnutrition. Furthermore, supply chain complexities involving the transport of temperature-sensitive or specialized liquid formulas can increase operational costs and affect product availability in remote regions.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shortage of Oncology Dietitians | -1.1% | Global | 2025 - 2034 |
| Supply Chain and Logistics Volatility | -0.6% | Middle East & APAC | 2025 - 2028 |
| Patient Non-Adherence Due to Taste | -0.8% | Global | 2025 - 2034 |
Oncology Nutrition Market - Updated Report Scope
The oncology nutrition market report provides a granular analysis of the global landscape, encompassing historical data from 2020 to 2024 and forward-looking projections up to 2034. It evaluates the impact of macroeconomic factors, technological innovations, and shifting patient demographics on the demand for specialized clinical nutrition. The scope includes a detailed breakdown of enteral and parenteral nutrition, cancer-specific formulations, and distribution channel dynamics across six major geographical regions.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 2.45 Billion |
| Market Forecast in 2034 | USD 5.12 Billion |
| Growth Rate | 8.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Abbott Laboratories, Nestlé S.A. (Nestlé Health Science), Danone S.A., Fresenius Kabi AG, B. Braun Melsungen AG, Baxter International Inc., Hormel Foods Corporation, Meiji Holdings Co., Ltd., Victus Inc., Global Health Products Inc., Medtrition Inc., Mead Johnson & Company, LLC, Pfizer Inc., Sanofi, Nutricia, Braun Melsungen, GlaxoSmithKline. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the oncology nutrition market reveals a complex ecosystem where product demand is highly dependent on the anatomical site of the cancer and the subsequent physiological complications. Head and neck cancers, alongside gastrointestinal malignancies, represent the core of the market because these conditions directly interfere with oral intake. Furthermore, the market is bifurcated by the complexity of the nutrients provided, with elemental formulas gaining traction for patients with severely impaired digestive capacities. The distribution channel analysis shows a gradual shift from hospital-centric procurement to retail and online platforms, reflecting the broader healthcare trend of decentralizing chronic disease management.
- By Cancer Type:
- Head and Neck Cancer: Driven by high dysphagia rates.
- Gastrointestinal Cancer: Focus on malabsorption and nutrient utilization.
- Lung Cancer: Nutritional support for cachexia management.
- Breast Cancer: Focus on weight management and antioxidant support during therapy.
- Blood Cancer: Support during high-dose chemotherapy and bone marrow transplants.
- By Product Type:
- Standard Formulas: Used for patients with normal digestive functions.
- Elemental Formulas: Predigested nutrients for easier absorption.
- Specialty Formulas: Enhanced with protein, fiber, or immune-modulators.
- By Route of Administration:
- Enteral Nutrition: Dominant segment due to safety and cost-effectiveness.
- Parenteral Nutrition: Used for patients with non-functional gastrointestinal tracts.
- By End User:
- Hospitals and Clinics: Primary points of initial prescription and acute care.
- Home Care Settings: Rapidly growing due to long-term nutritional needs.
Regional Highlights
- North America: Currently the largest market shareholder, North America benefits from a sophisticated healthcare system and a strong emphasis on early nutritional screening. The United States leads the region due to its high healthcare spending and the presence of major industry players like Abbott and Baxter.
- Europe: Europe maintains a significant market presence, characterized by advanced research in immunonutrition and high adoption of clinical nutrition guidelines provided by ESPEN (European Society for Clinical Nutrition and Metabolism). Germany, France, and the UK are the key contributors.
- Asia-Pacific: This is the fastest-growing region. Increasing awareness of clinical nutrition, coupled with the rapid expansion of medical infrastructure in China and India, is driving substantial demand. The aging population in Japan also contributes significantly to the regional market value.
- Latin America: The market is expanding as countries like Brazil and Mexico improve their oncology care frameworks and increase reimbursement coverage for enteral nutrition products.
- Middle East and Africa: Growth is driven by the establishment of specialized oncology centers in the GCC countries and a rising burden of non-communicable diseases across the continent.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Oncology Nutrition Market.- Abbott Laboratories
- Nestlé S.A. (Nestlé Health Science)
- Danone S.A. (Nutricia)
- Fresenius Kabi AG
- B. Braun Melsungen AG
- Baxter International Inc.
- Hormel Foods Corporation
- Meiji Holdings Co., Ltd.
- Victus Inc.
- Global Health Products Inc.
- Medtrition Inc.
- Mead Johnson & Company, LLC
- Pfizer Inc.
- Sanofi
- GlaxoSmithKline
- Braun Melsungen
- Acacia Pharma
- Bayer AG
- Ajinomoto Co., Inc.
Frequently Asked Questions
What is the current market size of the global Oncology Nutrition market?
The oncology nutrition market is estimated at USD 2.65 Billion in 2026 and is expected to reach USD 5.12 Billion by 2034, growing at a CAGR of 8.2%.
Which cancer segment drives the most demand for nutritional products?
Head and neck cancers and gastrointestinal cancers are the leading segments due to the high incidence of malnutrition and mechanical difficulties in eating associated with these diseases.
What is the difference between enteral and parenteral nutrition in oncology?
Enteral nutrition involves delivering food via the GI tract (orally or through a tube), while parenteral nutrition delivers nutrients directly into the bloodstream for patients whose digestive systems are not functioning.
Why is the Asia-Pacific region growing the fastest?
Rapidly improving healthcare infrastructure, a large and aging population, and an increasing incidence of cancer in countries like China and India are the primary growth drivers in APAC.
What are the key trends impacting the oncology nutrition market?
Major trends include the rise of personalized nutrition, the integration of AI for monitoring patient needs, the shift toward home-based care, and the increasing use of immunonutrition to improve surgical outcomes.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
