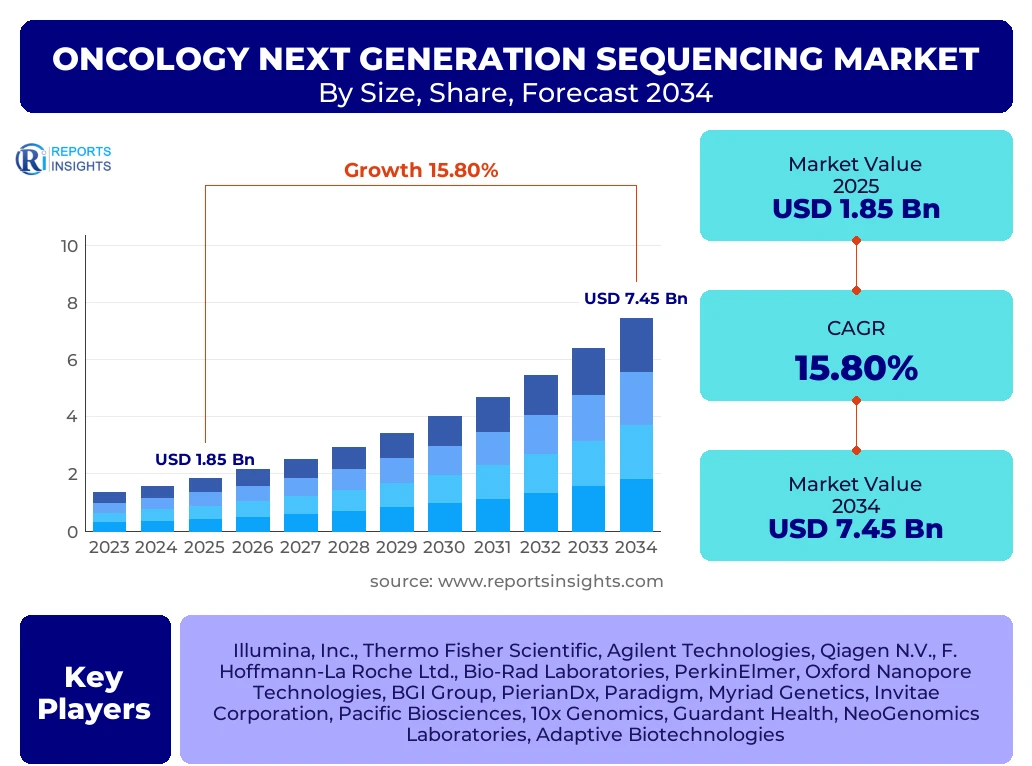
Oncology Next Generation Sequencing Market
Oncology Next Generation Sequencing Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711371 | Published On : October 29, 2026 |
Format : 


 | Author : Erika Grotto
Oncology Next Generation Sequencing Market Size
According to Reports Insights Consulting Pvt Ltd, The Oncology Next Generation Sequencing Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 15.8% between 2025 and 2034. The market is estimated at USD 2.14 Billion in 2026 and is projected to reach USD 7.45 Billion by the end of the forecast period in 2034.
Key Oncology Next Generation Sequencing Market Trends & Insights
The oncology next generation sequencing (NGS) market is undergoing a paradigm shift characterized by the transition from broad-based genomic research toward highly specific clinical diagnostics and personalized therapeutic interventions. Current market intelligence indicates a significant surge in the adoption of liquid biopsy assays, which utilize NGS to detect circulating tumor DNA (ctDNA) with high sensitivity. This non-invasive approach is revolutionizing minimal residual disease (MRD) monitoring and early cancer detection. Furthermore, the integration of artificial intelligence (AI) and machine learning (AI/ML) into bioinformatics pipelines is streamlining the interpretation of complex genomic data, reducing turnaround times for clinical reports. Stakeholders are increasingly focusing on multi-omics integration, combining genomic data with transcriptomic and proteomic insights to provide a holistic view of the tumor microenvironment. Competitive benchmarking reveals that leading organizations are pivoting toward "sample-to-insight" solutions to minimize workflow complexities for diagnostic laboratories.
- North America remains the largest regional market, driven by high healthcare expenditure and early adoption of precision medicine.
- The Asia-Pacific region is documented as the fastest-growing market due to improving laboratory infrastructure and rising cancer prevalence in China and India.
- The Targeted Sequencing and Resequencing segment holds the largest market share owing to its cost-effectiveness and clinical relevance in identifying actionable mutations.
- Consumables represent the highest revenue-generating product category, supported by the recurring need for reagents in high-throughput sequencing workflows.
Key Takeaways Oncology Next Generation Sequencing Market Size & Forecast
The strategic outlook for the oncology NGS market suggests a robust expansion trajectory as sequencing costs continue to decline, making genomic profiling accessible beyond academic research centers. Analysis of market dynamics reveals that the clinical diagnostics application is poised for exponential growth, fueled by the increasing number of FDA-approved companion diagnostics that require NGS-based validation. Forecast models indicate that the transition to decentralized testing—where hospitals perform sequencing in-house rather than outsourcing to reference labs—will be a primary driver for platform sales. Additionally, the regulatory landscape is becoming more favorable, with reimbursed genomic profiling becoming a standard of care for advanced-stage malignancies in developed economies.
- The United States is the leading country globally, supported by a sophisticated regulatory framework and extensive reimbursement coverage for genomic testing.
- Precision medicine initiatives are the primary catalyst for market expansion, shifting oncology treatment from "one-size-fits-all" to molecularly targeted therapies.
- Illumina, Thermo Fisher Scientific, and Roche maintain dominant positions through aggressive R&D and strategic acquisitions of bioinformatics firms.
- Market penetration in emerging economies is accelerating as regional players introduce affordable sequencing platforms and localized diagnostic kits.
Oncology Next Generation Sequencing Market Drivers Analysis
The primary growth engine for the oncology NGS market is the escalating global burden of cancer, necessitating more precise diagnostic and prognostic tools. Traditional biopsy and imaging methods often fail to capture the genetic heterogeneity of tumors, a gap that NGS fills by providing a comprehensive map of somatic and germline mutations. Furthermore, the precipitous drop in the cost per gigabase of sequencing data has democratized the technology, allowing smaller diagnostic facilities to integrate NGS into their routine workflows. The rise of personalized medicine is another critical driver, as pharmaceutical companies increasingly rely on NGS to identify patient cohorts for clinical trials of targeted therapies, thereby increasing the demand for companion diagnostics.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Declining Costs of Genomic Sequencing | +4.2% | Global | 2025 - 2034 |
| Expansion of Precision Medicine & Targeted Therapy | +3.8% | North America & Europe | 2025 - 2030 |
| Increasing Prevalence of Various Cancers | +3.5% | Asia Pacific & Latin America | 2025 - 2034 |
| Regulatory Approvals for NGS-based Companion Diagnostics | +2.9% | United States & EU | 2026 - 2032 |
Oncology Next Generation Sequencing Market Restraints Analysis
Despite the technological advancements, the oncology NGS market faces significant headwinds, primarily related to the complexity of data interpretation and the lack of standardized bioinformatics pipelines. The massive volume of data generated by whole genome or exome sequencing requires sophisticated computational infrastructure and highly skilled personnel, which are often lacking in mid-sized healthcare facilities. Additionally, reimbursement remains a complex hurdle; while coverage for late-stage cancer genomic profiling is improving, many private insurers still view multi-gene panels for early-stage screening as investigational, limiting widespread adoption. Data privacy concerns regarding the storage of sensitive genetic information also pose a challenge to large-scale genomic initiatives.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Complexity in Genomic Data Interpretation | -2.1% | Global | 2025 - 2028 |
| Inconsistent Reimbursement Policies | -1.8% | Europe & APAC | 2025 - 2030 |
| High Initial Capital Expenditure for Platforms | -1.5% | Developing Nations | 2025 - 2034 |
Oncology Next Generation Sequencing Market Opportunities Analysis
The future of oncology NGS lies in the expansion of liquid biopsy applications beyond therapy selection into the realms of screening and early detection. Developing high-sensitivity assays that can identify cancer at Stage I or II presents a multi-billion dollar opportunity. Furthermore, the integration of NGS with other diagnostic modalities, such as digital pathology and radiomics, offers a fertile ground for innovation in multi-modal diagnostics. There is also a significant opportunity in the pharmaceutical sector for the development of "basket" and "umbrella" clinical trials, which require robust NGS screening to match patients with therapies based on their molecular profile rather than the primary site of the tumor. Emerging markets in Southeast Asia and Africa represent untapped potential as healthcare infrastructure improves and regional genomic projects gain momentum.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Liquid Biopsy for Early Cancer Detection | +5.1% | Global | 2027 - 2034 |
| AI-driven Bioinformatics Solutions | +3.4% | North America & Japan | 2025 - 2034 |
| Direct-to-Consumer (DTC) Oncology Genetic Testing | +2.2% | United States & China | 2026 - 2032 |
Oncology Next Generation Sequencing Market Challenges Impact Analysis
One of the most persistent challenges in the oncology NGS sector is the ethical and regulatory ambiguity surrounding "variants of uncertain significance" (VUS). When a sequence reveals a mutation whose clinical impact is unknown, it creates a dilemma for oncologists and anxiety for patients. Furthermore, the rapid pace of technological change often outstrips the ability of clinical guidelines to stay current, leading to variability in the standard of care. Supply chain vulnerabilities for specialized reagents and the need for stringent cold-chain logistics also present operational hurdles, particularly for global diagnostic companies operating in disparate geographic regions.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Standardization of Sequencing Protocols | -1.4% | Global | Ongoing |
| Ethical Issues Regarding Variants of Uncertain Significance | -0.9% | North America & Europe | 2025 - 2034 |
Oncology Next Generation Sequencing Market - Updated Report Scope
The scope of this comprehensive market analysis encompasses the entire value chain of the oncology next generation sequencing industry. It includes a deep dive into the hardware (sequencing platforms), chemistry (reagents and consumables), and software (bioinformatics and data analysis tools) sectors. The report evaluates the market based on diverse cancer types, including breast, lung, colorectal, and hematological malignancies. Furthermore, it examines the shift from research-only use to diagnostic-grade sequencing in clinical settings. The analysis provides granular data on regional trends, competitive positioning, and the impact of macroeconomic factors such as healthcare policy shifts and investment in biotechnology research.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.85 Billion |
| Market Forecast in 2034 | USD 7.45 Billion |
| Growth Rate | 15.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Illumina, Inc., Thermo Fisher Scientific, Agilent Technologies, Qiagen N.V., F. Hoffmann-La Roche Ltd., Bio-Rad Laboratories, PerkinElmer, Oxford Nanopore Technologies, BGI Group, PierianDx, Paradigm, Myriad Genetics, Invitae Corporation, Pacific Biosciences, 10x Genomics, Guardant Health, NeoGenomics Laboratories, Adaptive Biotechnologies |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The oncology NGS market is segmented with high granularity to reflect the diverse applications and technological variations within the industry. The technology segment is dominated by Targeted Sequencing and Resequencing due to its high depth of coverage and lower data complexity, making it ideal for clinical diagnostics. Whole Exome Sequencing (WES) is witnessing increased adoption in identifying rare variants in cancer research. From a product perspective, the consumables segment remains the most lucrative, driven by the recurring demand for high-quality library preparation kits and sequencing reagents. Application-wise, Personalized Medicine is the fastest-growing segment, as genomic profiling becomes integral to selecting the most effective therapeutic agents for specific molecular subtypes of cancer.
- By Technology:
- Whole Genome Sequencing (WGS)
- Whole Exome Sequencing (WES)
- Targeted Sequencing & Resequencing (Gene Panels)
- By Product and Service:
- Consumables (Reagents, Kits)
- NGS Platforms (Sequencers)
- Services (Bioinformatics, Sequencing Services)
- By Application:
- Clinical Diagnostics (Screening, Prognosis, MRD)
- Drug Discovery and Development
- Personalized Medicine / Targeted Therapy
- Academic and Clinical Research
- By Cancer Type:
- Breast Cancer
- Lung Cancer
- Colorectal Cancer
- Prostate Cancer
- Hematological Malignancies
- Other Solid Tumors
- By End-User:
- Hospitals and Clinics
- Diagnostic Laboratories
- Pharmaceutical and Biotechnology Companies
- Academic and Research Institutes
Regional Highlights
- North America: The largest market share holder, North America is characterized by a robust ecosystem of biotech innovators, high genomic literacy among clinicians, and extensive reimbursement for NGS-based multi-gene panels. The United States leads in the integration of NGS into clinical practice guidelines (e.g., NCCN).
- Europe: Europe represents a significant market with a focus on centralized genomic initiatives, such as the UK's Genomic Medicine Service. Germany, France, and the UK are the primary contributors, driven by strong government support for cancer research.
- Asia-Pacific: This is the fastest-growing region. Rapidly improving healthcare infrastructure in China and India, coupled with a massive patient population, is attracting global players. Local companies in China are also developing competitive sequencing platforms.
- Latin America: The market is emerging, with Brazil and Mexico seeing increased investment in diagnostic labs. Growth is limited by high import duties on sequencing equipment and reagents.
- Middle East and Africa: Growth is primarily centered in the GCC countries, which are investing heavily in national genomic projects and precision medicine infrastructure.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Oncology Next Generation Sequencing Market.- Illumina, Inc.
- Thermo Fisher Scientific
- Agilent Technologies
- Qiagen N.V.
- F. Hoffmann-La Roche Ltd.
- Bio-Rad Laboratories
- PerkinElmer, Inc.
- Oxford Nanopore Technologies
- BGI Group
- PierianDx
- Paradigm (A subsidiary of Exact Sciences)
- Myriad Genetics, Inc.
- Invitae Corporation
- Pacific Biosciences
- 10x Genomics
- Guardant Health, Inc.
- NeoGenomics Laboratories
- Adaptive Biotechnologies
- Eurofins Scientific
- Macrogen, Inc.
Frequently Asked Questions
What is the projected CAGR for the Oncology Next Generation Sequencing Market from 2025 to 2034?
The market is projected to grow at a Compound Annual Growth Rate (CAGR) of 15.8%, reaching a valuation of approximately USD 7.45 Billion by 2034, driven by the expansion of precision medicine and clinical diagnostics.
Which technology segment currently dominates the Oncology NGS market?
The Targeted Sequencing and Resequencing segment currently dominates the market because it offers high accuracy for specific actionable mutations at a lower cost compared to Whole Genome Sequencing, making it the preferred choice for clinical use.
What are the primary factors driving the adoption of liquid biopsy in oncology?
The adoption is driven by the non-invasive nature of the test, its ability to capture the heterogeneity of the entire tumor, and its high sensitivity for monitoring minimal residual disease (MRD) and early recurrence.
Who are the leading players in the global Oncology Next Generation Sequencing Market?
The market is led by companies such as Illumina, Thermo Fisher Scientific, Roche, and Agilent Technologies, who dominate through extensive platform installs, recurring consumable revenue, and integrated bioinformatics solutions.
What is the most significant challenge facing the Oncology NGS industry?
The most significant challenge is the complexity of genomic data interpretation and the lack of standardization in bioinformatics, which can lead to inconsistencies in clinical reports and difficulty in interpreting variants of uncertain significance.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
