Cutter Stapler Market
Cutter Stapler Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711266 | Published On : October 23, 2026 |
Format : 


 | Author : Erika Grotto
Cutter Stapler Market Size
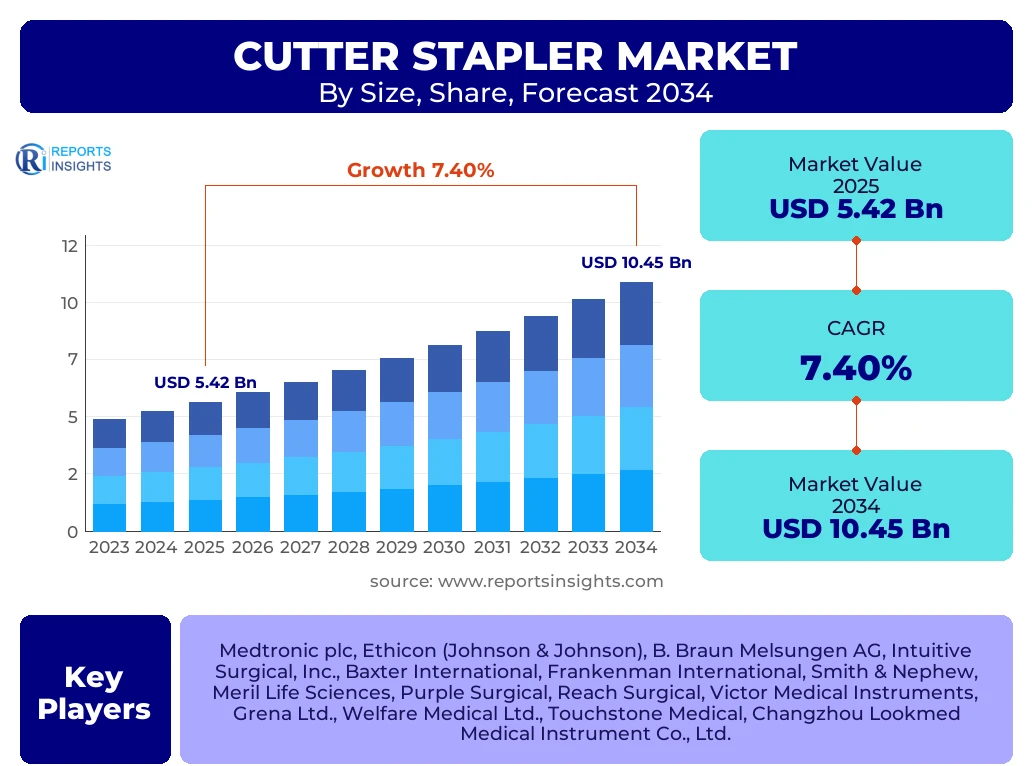
According to Reports Insights Consulting Pvt Ltd, The Cutter Stapler Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.4% between 2025 and 2034. The market is estimated at USD 5.82 Billion in 2026 and is projected to reach USD 10.45 Billion by the end of the forecast period in 2034.
Key Cutter Stapler Market Trends & Insights
The Cutter Stapler Market is undergoing a significant transformation driven by the transition from traditional open surgeries to minimally invasive procedures. Current market intelligence indicates a sharp rise in the adoption of powered and electronic stapling systems that offer superior precision and reduced tissue trauma compared to manual variants. Furthermore, the integration of advanced sensors and smart technology within stapling devices allows for real-time feedback on tissue thickness, which is a critical factor in reducing post-operative complications such as anastomotic leaks. Strategic benchmarking reveals that market leaders are increasingly focusing on specialized staplers for bariatric and thoracic applications, where tissue management is exceptionally complex.
- Largest Region: North America currently holds the largest market share, driven by a high volume of complex surgical procedures and early adoption of advanced medical technologies.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR due to expanding healthcare infrastructure and a rising prevalence of chronic diseases requiring surgical intervention.
- Largest Segment: The Endoscopic Stapler segment dominates the market in terms of value share, fueled by the global shift toward laparoscopic surgery.
- Leading Technology: Powered staplers are witnessing the fastest adoption rates among healthcare providers seeking to minimize surgeon fatigue and improve consistency.
Key Takeaways Cutter Stapler Market Size & Forecast
The global outlook for the Cutter Stapler market remains robust as surgical volumes recover and expand beyond pre-pandemic levels. Market analysis suggests that the demand for high-quality wound closure solutions is no longer confined to developed economies but is rapidly accelerating in emerging markets. The forecast period is expected to see a consolidation of market players as larger entities acquire niche innovators to enhance their product portfolios in the robotic-assisted surgery space. Additionally, the move toward value-based healthcare is pushing manufacturers to demonstrate the cost-effectiveness of premium stapling devices through reduced readmission rates and shorter hospital stays.
- The global market value is set to exceed USD 10 Billion by 2034, maintaining a steady upward trajectory.
- Technological convergence between stapling devices and robotic surgical platforms is a primary growth engine.
- The United States remains the leading national market, while China and India emerge as critical manufacturing and consumption hubs.
- Hospitals remain the primary end-users, though Ambulatory Surgical Centers (ASCs) are the fastest-growing end-user segment.
Cutter Stapler Market Drivers Analysis
The primary catalyst for the Cutter Stapler market is the global surge in minimally invasive surgeries (MIS). Compared to traditional methods, MIS offers patients shorter recovery times, less pain, and smaller scars. As healthcare systems worldwide prioritize efficient patient turnover and improved clinical outcomes, the demand for sophisticated stapling instruments that can operate effectively within confined spaces has increased dramatically. This trend is particularly evident in gastrointestinal and cardiovascular surgeries, where precision is paramount.
Another critical driver is the rising incidence of obesity and related metabolic disorders, which has led to a significant increase in bariatric surgical procedures globally. Bariatric surgeries, such as gastric bypass and sleeve gastrectomy, rely heavily on reliable cutter staplers for tissue resection and anastomosis. As more countries include these surgeries under insurance coverage and public health initiatives, the volume of stapler units consumed per year continues to climb, providing a consistent revenue stream for manufacturers.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shift toward Minimally Invasive Surgery (MIS) | +2.8% | Global | 2025 - 2034 |
| Rising Prevalence of Bariatric Surgeries | +1.5% | North America & Europe | 2025 - 2030 |
| Technological Integration with Robotics | +1.2% | United States, Germany, Japan | 2027 - 2034 |
| Aging Population and Chronic Disease Volume | +0.9% | Global (APAC focus) | 2025 - 2034 |
Cutter Stapler Market Restraints Analysis
One of the most significant barriers to market expansion is the high cost associated with advanced cutter staplers, particularly powered and robotic-compatible models. In price-sensitive markets within the APAC and MEA regions, healthcare providers often opt for traditional manual suturing or lower-cost manual staplers, which can limit the adoption of premium technologies. This financial pressure is compounded by tightening healthcare budgets and the implementation of stringent reimbursement policies in developed nations.
Furthermore, the market faces challenges related to product recalls and safety concerns. Occasional mechanical failures, such as staples failing to form correctly or the cutting blade malfunctioning, can lead to severe clinical complications like internal bleeding or sepsis. These incidents not only result in legal liabilities for manufacturers but also necessitate rigorous and expensive regulatory compliance measures that can slow down the time-to-market for new innovations.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Advanced Powered Staplers | -1.1% | Emerging Economies | 2025 - 2034 |
| Strict Regulatory Approval Processes | -0.7% | USA (FDA), Europe (MDR) | 2025 - 2028 |
| Risk of Post-operative Complications | -0.5% | Global | 2025 - 2034 |
Cutter Stapler Market Opportunities Analysis
The expansion of healthcare infrastructure in emerging economies presents a massive opportunity for cutter stapler manufacturers. As governments in countries like China, India, and Brazil invest in modernizing hospital facilities and training surgical staff, the baseline demand for modern surgical tools is rising. Companies that can offer "mid-tier" products—balancing advanced features with affordable pricing—are likely to capture significant market share in these developing regions.
Additionally, there is a burgeoning opportunity in the development of smart staplers equipped with Artificial Intelligence (AI) and the Internet of Things (IoT). These devices can collect intraoperative data, providing surgeons with insights into tissue compression and vascularity. By converting a mechanical tool into a data-driven surgical assistant, manufacturers can differentiate their products and move toward a service-oriented business model that includes data analytics and surgical training platforms.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Untapped Markets in BRIC Nations | +2.1% | China, India, Brazil | 2026 - 2034 |
| AI-Driven Intraoperative Feedback Systems | +1.4% | North America & Japan | 2028 - 2034 |
| Growth of Ambulatory Surgical Centers (ASCs) | +1.0% | United States | 2025 - 2032 |
Cutter Stapler Market Challenges Impact Analysis
The global supply chain remains a point of vulnerability for the cutter stapler industry. Dependence on specific raw materials and precision electronic components for powered staplers means that geopolitical tensions or logistics disruptions can significantly impact production schedules. Maintaining a resilient and diversified supply chain is a critical challenge that requires substantial investment in local manufacturing and inventory management.
Moreover, the intense competitive landscape and the presence of established giants make it difficult for new entrants to gain a foothold. Large medical device companies benefit from extensive distribution networks and bundled contracts with hospital groups. Small-scale innovators must navigate these high barriers to entry by focusing on hyper-specialized applications or by seeking partnerships with established leaders to bring their technology to the mass market.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Instability | -0.6% | Global | 2025 - 2027 |
| Market Consolidation and High Entry Barriers | -0.4% | Global | 2025 - 2034 |
| Shortage of Skilled Surgeons in Rural Areas | -0.3% | Africa & Parts of Asia | 2025 - 2030 |
Cutter Stapler Market - Updated Report Scope
The scope of this report covers the comprehensive ecosystem of the Cutter Stapler market, including technical specifications, competitive landscapes, and long-term financial forecasts. It analyzes the interplay between technological innovation and clinical requirements across various surgical specialties. The report provides a granular look at the shift from manual to powered technologies and the burgeoning role of robotic integration in the surgical suite.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 5.42 Billion |
| Market Forecast in 2034 | USD 10.45 Billion |
| Growth Rate | 7.4% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Medtronic plc, Ethicon (Johnson & Johnson), B. Braun Melsungen AG, Intuitive Surgical, Inc., Baxter International, Frankenman International, Smith & Nephew, Meril Life Sciences, Purple Surgical, Reach Surgical, Victor Medical Instruments, Grena Ltd., Welfare Medical Ltd., Touchstone Medical, Changzhou Lookmed Medical Instrument Co., Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The cutter stapler market is segmented based on product design, operating technology, surgical application, and end-user environment. This multi-dimensional segmentation allows for a detailed understanding of where growth is most concentrated and which technologies are becoming obsolete. The shift toward Endoscopic and Powered segments is the most notable trend across all geographic markets.
- By Product Type: Includes Endoscopic staplers for MIS, Circular staplers for end-to-end anastomosis, and Linear staplers for tissue transection. Endoscopic variants represent the highest value segment.
- By Technology: Divided into Manual and Powered staplers. Powered staplers are rapidly gaining share due to improved ergonomics and consistency.
- By Application: Covers diverse fields like Abdominal (highest volume), Thoracic (highest precision), and Bariatric (highest growth).
- By End-User: Hospitals remain the primary volume drivers, while ASCs are increasingly adopting these tools for outpatient procedures.
Regional Highlights
- North America: The largest market due to high healthcare expenditure, a sophisticated reimbursement framework, and the presence of industry leaders like Medtronic and Ethicon. The U.S. is the primary driver of robotic-compatible stapler sales.
- Europe: A mature market focused on clinical outcomes and cost-efficiency. Countries like Germany and France are leading in the adoption of powered endoscopic staplers within public health systems.
- Asia-Pacific: The fastest-growing region. Rapid urbanization and the expansion of private hospital chains in China and India are creating significant demand for surgical staples.
- Latin America & MEA: Developing markets where growth is tied to healthcare infrastructure improvements and the rising volume of elective surgeries.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Cutter Stapler Market.- Medtronic plc
- Ethicon (Johnson & Johnson)
- B. Braun Melsungen AG
- Intuitive Surgical, Inc.
- Baxter International
- Frankenman International
- Smith & Nephew
- Meril Life Sciences
- Purple Surgical
- Reach Surgical
- Victor Medical Instruments
- Grena Ltd.
- Welfare Medical Ltd.
- Touchstone Medical
- Changzhou Lookmed Medical Instrument Co., Ltd.
Frequently Asked Questions
What is the current size of the global Cutter Stapler market?
The market is estimated at approximately USD 5.42 Billion in 2025 and is expected to reach over USD 10 Billion by 2034.
Who are the leading manufacturers in the Cutter Stapler industry?
The industry is dominated by major medical device companies including Medtronic, Ethicon (a subsidiary of Johnson & Johnson), and Intuitive Surgical.
Why is the market moving from manual to powered staplers?
Powered staplers offer greater precision, reduced hand fatigue for surgeons, and consistent staple formation, which helps in reducing tissue damage and post-operative complications.
Which region offers the most growth potential for investors?
The Asia-Pacific region offers the highest growth potential due to its rapidly expanding healthcare infrastructure and increasing volume of surgical procedures.
What are the main applications for cutter staplers?
Cutter staplers are primarily used in abdominal, thoracic, bariatric, and gynecological surgeries for tissue resection and the creation of anastomoses.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
