Empty Iv Bags Market
Empty Iv Bags Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711077 | Published On : October 04, 2026 |
Format : 


 | Author : Erika Grotto
Empty Iv Bags Market Size
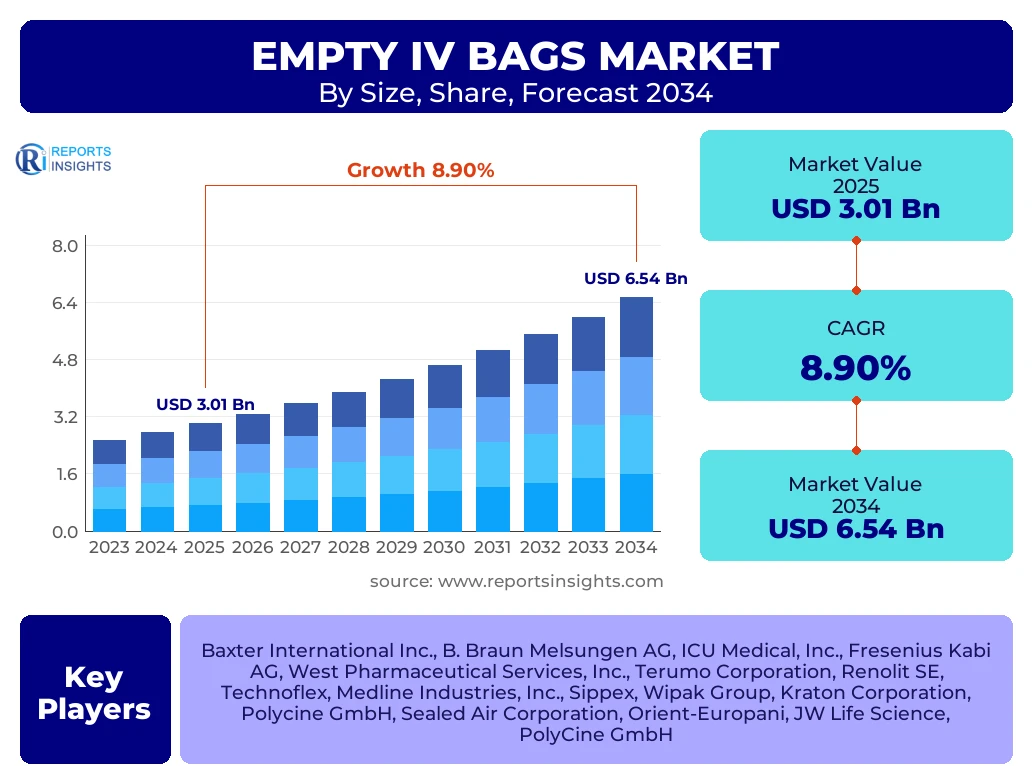
According to Reports Insights Consulting Pvt Ltd, The Empty Iv Bags Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.9% between 2025 and 2034. The market is estimated at USD 3.28 Billion in 2026 and is projected to reach USD 6.54 Billion by the end of the forecast period in 2034.
Key Empty Iv Bags Market Trends & Insights
The empty IV bags market is undergoing a significant transformation driven by the global transition from traditional PVC-based containers to advanced non-PVC materials. This shift is primarily motivated by safety concerns regarding the leaching of phthalates such as DEHP into intravenous solutions. Furthermore, the rising volume of surgical procedures and the increasing prevalence of chronic diseases requiring long-term infusion therapy are bolstering market demand. Competitive benchmarking indicates that leading manufacturers are prioritizing sustainable manufacturing processes and the development of multi-chamber bags to minimize medication errors during parenteral nutrition administration. Regional insights suggest that while North America maintains the largest market share due to its advanced healthcare infrastructure, the Asia-Pacific region is emerging as the fastest-growing market due to rapid healthcare modernization and expanding hospital networks.
- Largest Region: North America remains the dominant revenue contributor, holding over 35% of the total market share as of 2024.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR during the forecast period, driven by increasing healthcare expenditure in China and India.
- Leading Segment by Material: The Non-PVC material segment is currently the largest and fastest-growing segment due to stringent regulatory standards against toxic additives.
- Leading Segment by End-User: Hospitals represent the largest end-user segment, accounting for the majority of the market volume.
- Emerging Trend: Increased adoption of self-administration and home-based infusion therapy is fueling the demand for smaller-capacity, user-friendly empty IV bags.
Key Takeaways Empty Iv Bags Market Size & Forecast
The global empty IV bags market is characterized by high demand for sterile, reliable, and chemically inert fluid containers. Stakeholders are focusing on enhancing the shelf life of these products and ensuring compatibility with a wide range of pharmaceutical formulations. The market forecast indicates a robust upward trajectory as healthcare providers move toward more efficient fluid management systems and as personalized medicine drives the need for customizable IV solutions. The integration of barcode technology on IV bags for better traceability and patient safety is also a major takeaway from recent market developments.
- Market Valuation: The total market is expected to nearly double in size by 2034, reflecting the critical nature of IV therapy in modern medicine.
- Material Evolution: Non-PVC materials, including Ethylene-vinyl acetate (EVA) and Polypropylene, are becoming the industry standard to meet environmental and clinical safety protocols.
- Regional Leadership: The United States leads the market in terms of technological adoption and high-volume consumption per capita.
- Strategic Consolidation: Major players are engaging in mergers and acquisitions to expand their production capacities and geographic footprint in emerging economies.
- Sustainability Focus: There is a growing emphasis on recyclable medical plastics to reduce the carbon footprint of healthcare facilities.
Empty Iv Bags Market Drivers Analysis
The growth of the empty IV bags market is underpinned by several macro-economic and clinical factors. The increasing geriatric population worldwide, who are more susceptible to chronic illnesses requiring intravenous treatment, serves as a primary driver. Additionally, the rise in the number of outpatient surgeries and the expansion of the pharmaceutical industry, particularly in the biologics sector, necessitate advanced fluid delivery systems. The move toward standardized concentration and premixed solutions also encourages the procurement of high-quality empty IV bags for compounding pharmacy operations.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Prevalence of Chronic Diseases | +2.4% | Global | 2025 - 2034 |
| Shift from PVC to Non-PVC Materials | +1.8% | Europe and North America | 2025 - 2030 |
| Growth in Ambulatory Surgical Centers (ASCs) | +1.5% | United States and Germany | 2026 - 2034 |
| Advancements in Home Healthcare | +1.2% | Japan and United Kingdom | 2027 - 2034 |
Empty Iv Bags Market Restraints Analysis
Despite the positive growth outlook, the market faces certain constraints that could impede its progress. Stringent regulatory requirements for the approval of medical-grade plastics and the high cost associated with the transition to non-PVC manufacturing lines are significant barriers. Furthermore, the volatility in raw material prices, particularly specialized resins, can impact the profit margins of manufacturers. Environmental concerns regarding the disposal of medical plastic waste also pose a challenge for long-term sustainability initiatives in the healthcare sector.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Regulatory Compliance Standards | -1.1% | European Union and United States | 2025 - 2034 |
| High Production Costs for Multi-Chamber Bags | -0.8% | Global | 2025 - 2028 |
| Environmental Regulations on Plastic Waste | -0.6% | China and European Union | 2026 - 2034 |
Empty Iv Bags Market Opportunities Analysis
The market presents lucrative opportunities for innovation, particularly in the development of "smart" IV bags equipped with integrated sensors and RFID tags for real-time monitoring of fluid levels and medication administration. There is also significant potential in emerging markets in Southeast Asia and Latin America, where healthcare infrastructure is receiving massive government investment. The expansion of compounding pharmacies and the increasing demand for specialized bags for chemotherapy and parenteral nutrition represent high-growth niches for existing and new market entrants.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Compounding Pharmacy Services | +1.9% | North America and BRIC Nations | 2025 - 2034 |
| Development of Eco-friendly Bio-based Plastics | +1.3% | Scandinavia and Western Europe | 2028 - 2034 |
| Telehealth and Connected IV Delivery Systems | +1.1% | United States and South Korea | 2027 - 2034 |
Empty Iv Bags Market Challenges Impact Analysis
One of the primary challenges in the empty IV bags market is the intense competition among global players, which leads to pricing pressures and the need for constant product differentiation. Maintaining the sterility of bags throughout the supply chain, especially in regions with underdeveloped logistics infrastructure, remains a critical hurdle. Additionally, the risk of chemical interactions between the bag material and complex pharmaceutical formulations requires extensive compatibility testing, which can delay product launches and increase development costs.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Fluctuating Raw Material Prices (Resins) | -0.7% | Global | 2025 - 2034 |
| Supply Chain Disruptions in Emerging Markets | -0.5% | India and Southeast Asia | 2025 - 2030 |
| Product Recalls and Quality Control Issues | -0.4% | Global | 2025 - 2034 |
Empty Iv Bags Market - Updated Report Scope
This comprehensive market research report provides an in-depth analysis of the global empty IV bags industry, covering historical trends, current market dynamics, and future projections. The scope encompasses various material types, capacity ranges, and end-user segments across major geographical regions. The report evaluates the competitive landscape by profiling key players and analyzing their strategic initiatives, such as product launches, partnerships, and technological advancements, to provide a 360-degree view of the market environment.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 3.01 Billion |
| Market Forecast in 2034 | USD 6.54 Billion |
| Growth Rate | 8.9% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Baxter International Inc., B. Braun Melsungen AG, ICU Medical, Inc., Fresenius Kabi AG, West Pharmaceutical Services, Inc., Terumo Corporation, Renolit SE, Technoflex, Medline Industries, Inc., Sippex, Wipak Group, Kraton Corporation, Polycine GmbH, Sealed Air Corporation, Orient-Europani, JW Life Science, PolyCine GmbH |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The empty IV bags market is segmented based on material, product type, capacity, and end-user. The material segment is particularly crucial, as the shift from traditional PVC to Non-PVC materials like Ethylene-vinyl acetate (EVA) and Polypropylene is the defining trend of the decade. Capacity-wise, the 250-500 ml bags are the most commonly used across clinical settings, though larger bags are gaining traction in intensive care units. End-user analysis reveals that while hospitals remain the primary consumers, the growth of ambulatory surgery centers and home healthcare providers is creating new demand patterns that manufacturers are eager to exploit.
- By Product Type:
- Single Chamber Bags: Widely used for standard fluid resuscitation and medication delivery.
- Multi-Chamber Bags: Increasing adoption for Total Parenteral Nutrition (TPN) to ensure sterile mixing of components at the point of care.
- By Material:
- PVC (Polyvinyl Chloride): Traditional material, seeing declining share due to toxicity concerns.
- Non-PVC: Includes Polypropylene and EVA, favored for chemical stability and environmental safety.
- By Capacity:
- 0-250 ml: Used for pediatric care and concentrated medication delivery.
- 250-500 ml: Standard size for most intravenous therapies.
- 500-1000 ml: Common for hydration and electrolyte replacement.
- Above 1000 ml: Primarily used for large-volume infusions and specialized treatments.
- By End-User:
- Hospitals: The largest segment due to high surgical volumes and emergency care needs.
- Clinics and ASCs: Growing segment focused on outpatient procedures.
- Home Care Settings: Rising demand for chronic disease management outside clinical environments.
Regional Highlights
- North America: Currently the largest market globally, characterized by advanced healthcare systems and a high rate of non-PVC adoption. The United States is the primary revenue driver in this region.
- Europe: A mature market with stringent regulations regarding medical plastic safety. Germany, France, and the UK are leading contributors to the European market share.
- Asia-Pacific: The fastest-growing region. Rapid urbanization, increasing healthcare insurance coverage, and the expansion of the pharmaceutical manufacturing sector in China and India are significant factors.
- Latin America: Showing steady growth due to the modernization of public health facilities in Brazil and Mexico.
- Middle East and Africa: Growth is driven by increasing investments in medical infrastructure and the rising prevalence of metabolic diseases requiring hospitalization.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Empty Iv Bags Market.- Baxter International Inc.
- B. Braun Melsungen AG
- ICU Medical, Inc.
- Fresenius Kabi AG
- West Pharmaceutical Services, Inc.
- Terumo Corporation
- Renolit SE
- Technoflex
- Medline Industries, Inc.
- Sippex
- Wipak Group
- Kraton Corporation
- Polycine GmbH
- Sealed Air Corporation
- Orient-Europani
- JW Life Science
- Vifor Pharma
- Smit-Medical
- GVS S.p.A.
- Macopharma
Frequently Asked Questions
What is the current market size of the Empty IV Bags industry?
The market is estimated to be valued at approximately USD 3.01 Billion in 2025 and is expected to reach USD 6.54 Billion by 2034, growing at a CAGR of 8.9%.
Why is the market shifting from PVC to Non-PVC materials?
The shift is primarily driven by safety concerns regarding DEHP leaching from PVC bags into the IV fluids, as well as environmental regulations favoring more recyclable and less toxic plastic alternatives.
Which region is expected to grow the fastest during the forecast period?
Asia-Pacific is projected to be the fastest-growing region due to expanding healthcare access, rising surgical procedures, and significant investments in medical device manufacturing.
What are the primary applications of multi-chamber IV bags?
Multi-chamber bags are mainly used for parenteral nutrition and complex drug delivery, where multiple components need to be stored separately and mixed just before administration to maintain stability and sterility.
Who are the leading manufacturers in the global empty IV bags market?
Major players include Baxter International, B. Braun Melsungen, ICU Medical, and Fresenius Kabi, who dominate through extensive distribution networks and advanced product portfolios.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted