Mercury Market
Mercury Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711392 | Published On : October 30, 2026 |
Format : 


 | Author : Erika Grotto
Mercury Market Size
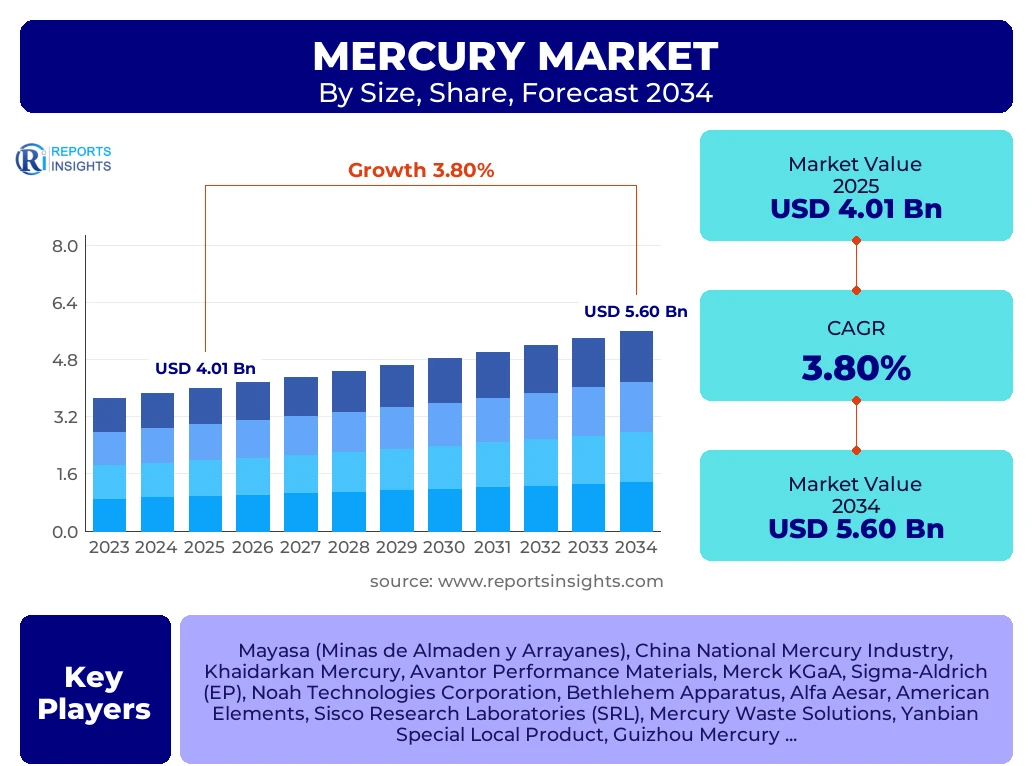
According to Reports Insights Consulting Pvt Ltd, The Mercury Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 3.8 percent between 2025 and 2034. The market is estimated at USD 4.15 Billion in 2026 and is projected to reach USD 5.60 Billion by the end of the forecast period in 2034.
Key Mercury Market Trends & Insights
The global mercury market is currently navigating a complex landscape defined by stringent international environmental regulations and the persistent demand from specific industrial and artisanal sectors. While the Minamata Convention on Mercury has significantly curtailed the use of mercury in many traditional applications, such as medical thermometers and certain types of lighting, the market remains sustained by its critical role in the chlor-alkali industry and artisanal small-scale gold mining (ASGM) in emerging economies. Strategic shifts toward mercury recovery and recycling technologies are becoming more prevalent as primary mining faces increasing scrutiny. Competitive benchmarking reveals that companies are pivoting toward high-purity mercury for specialized chemical synthesis and high-tech electronics, where alternatives are not yet commercially viable.
- Largest Region: Asia Pacific remains the dominant market shareholder, driven by extensive industrial manufacturing activities in China and India.
- Fastest Growing Region: Africa and parts of Latin America are exhibiting the highest growth rates due to the continued expansion of artisanal gold mining activities.
- Largest Segment: The Chlor-alkali production segment continues to hold the largest market share in terms of industrial consumption.
- Emerging Trend: Increased investment in closed-loop mercury recycling systems to mitigate environmental discharge and comply with global safety standards.
Key Takeaways Mercury Market Size & Forecast
The mercury market forecast is characterized by a steady but cautious growth trajectory. Stakeholders are increasingly focusing on vertical integration to secure supply chains while navigating the phasing out of mercury-added products. The forecast suggests that while volume growth in developed nations will stagnate or decline, the overall market valuation will be buoyed by rising prices and the cost of specialized handling and regulatory compliance. The demand for high-grade mercury in specialized laboratory reagents and technical applications provides a stable floor for market valuation throughout the forecast period.
- Leading Country: China is the primary producer and consumer, influencing global price indices significantly.
- Supply Chain Stability: Mercury recovered from byproduct streams in non-ferrous metal smelting is becoming a primary source of supply.
- Technology Integration: Advanced sensor technologies and mercury-free alternatives are challenging the market, yet mercury remains indispensable in high-pressure sodium lamps used in specific industrial lighting.
- Regulatory Influence: Compliance with the Minamata Convention is the single most influential factor shaping regional market dynamics and trade flows.
Mercury Market Drivers Analysis
The growth of the mercury market is primarily propelled by its unique chemical properties that are difficult to replicate in high-stress industrial environments. Despite environmental pressures, the expansion of the chemical industry in developing nations and the lack of cost-effective alternatives in specific mining sectors act as the main engines of market demand.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Artisanal gold mining | +1.2% | Sub-Saharan Africa and Brazil | 2025 - 2034 |
| Demand in Chlor-Alkali manufacturing | +0.9% | China and Southeast Asia | 2025 - 2030 |
| Specialized Electronic Components | +0.7% | Global High-Tech Hubs | 2026 - 2034 |
| Replacement Cycles in Industrial Lighting | +0.5% | North America and Europe | 2025 - 2028 |
Mercury Market Restraints Analysis
Restraints in the mercury market are predominantly regulatory and health-related. The transition toward mercury-free technologies in the medical and consumer goods sectors, coupled with strict export bans in various jurisdictions, significantly limits the potential for volume expansion.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Minamata Convention Phase-outs | -1.5% | Global (140+ countries) | 2025 - 2034 |
| Adoption of LED Lighting | -0.8% | Developed Economies | 2025 - 2030 |
| High Costs of Hazardous Disposal | -0.4% | Europe and North America | 2026 - 2034 |
Mercury Market Opportunities Analysis
Opportunities within the mercury sector are increasingly found in the circular economy and the development of ultra-high purity mercury for scientific research. As primary mining decreases, the secondary market for recycled and stabilized mercury presents significant profit margins for specialized players.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Mercury Recovery Systems | +1.1% | EU and Japan | 2026 - 2034 |
| Niche Medical Research Applications | +0.4% | United States and Germany | 2027 - 2034 |
| Modernization of Mining Equipment | +0.6% | Peru and Ghana | 2025 - 2032 |
Mercury Market Challenges Impact Analysis
The primary challenge for the mercury market is the social and political pressure to achieve a mercury-free future. This necessitates massive investments in research and development to find viable substitutes and the high cost associated with international logistics for hazardous materials.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Illicit International Trade | -0.5% | Cross-border Emerging Markets | 2025 - 2034 |
| Substitution by Digital Measuring Tools | -0.7% | Global Healthcare Sector | 2025 - 2030 |
Mercury Market - Updated Report Scope
The scope of this report encompasses a comprehensive analysis of the global mercury value chain, from extraction and primary production to secondary recycling and end-use applications. It evaluates the impact of international environmental protocols on market supply and demand dynamics across six key geographic regions.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 4.01 Billion |
| Market Forecast in 2034 | USD 5.60 Billion |
| Growth Rate | 3.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Mayasa (Minas de Almaden y Arrayanes), China National Mercury Industry, Khaidarkan Mercury, Avantor Performance Materials, Merck KGaA, Sigma-Aldrich (EP), Noah Technologies Corporation, Bethlehem Apparatus, Alfa Aesar, American Elements, Sisco Research Laboratories (SRL), Mercury Waste Solutions, Yanbian Special Local Product, Guizhou Mercury, ACT (Advanced Chemical Transport) |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The mercury market is segmented by type, application, and grade to provide a granular view of the consumption patterns and growth drivers. The industrial segment remains the primary consumer, while the high-purity grade mercury is seeing increased demand in research and development sectors.
- By Type: Silver Mercury represents the largest segment by volume, used extensively in industrial processes. Red Mercury and other specialized variants remain niche segments with specific technical applications.
- By Application: The Chlor-alkali industry is the dominant application segment, followed closely by artisanal mining. The healthcare segment is experiencing a decline as digital alternatives replace mercury-based devices.
- By Grade: Industrial Grade mercury accounts for the majority of the market share, while High Purity Grade mercury (99.999% and above) is gaining traction in the semiconductor and chemical synthesis markets.
Regional Highlights
- Asia Pacific: Currently the largest market due to the concentration of chemical manufacturing in China and India. It is expected to maintain its lead despite growing environmental regulations.
- North America and Europe: These regions are the most regulated, with market growth driven primarily by secondary recovery, recycling, and specialized laboratory use.
- Africa: Recognized as the fastest-growing region due to the prevalence of artisanal gold mining activities in countries like Ghana and Sudan.
- Latin America: Significant market presence in countries like Peru and Brazil, largely tied to the mining sector and industrial chemical production.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Mercury Market.- Mayasa (Minas de Almaden y Arrayanes)
- China National Mercury Industry
- Khaidarkan Mercury
- Avantor Performance Materials
- Merck KGaA
- Sigma-Aldrich
- Noah Technologies Corporation
- Bethlehem Apparatus
- Alfa Aesar
- American Elements
- Sisco Research Laboratories (SRL)
- Mercury Waste Solutions
- Yanbian Special Local Product
- Guizhou Mercury
- ACT (Advanced Chemical Transport)
Frequently Asked Questions
What is the primary driver for the Mercury market growth between 2025 and 2034?
The primary driver is the sustained demand for mercury in artisanal small-scale gold mining and specific industrial processes like chlor-alkali production in emerging economies, where cost-effective alternatives are not yet fully implemented.
How does the Minamata Convention affect the global Mercury market?
The Minamata Convention acts as a major market restraint by mandating the phase-out of mercury-added products and placing strict controls on mercury emissions and trade, forcing the market toward recycling and substitution.
Which region currently holds the largest share of the Mercury market?
The Asia Pacific region, led by China, holds the largest share of the mercury market due to its extensive chemical manufacturing infrastructure and significant industrial usage.
Is there a growing demand for recycled mercury?
Yes, the demand for recycled mercury is growing as primary mining becomes more regulated and companies seek sustainable, closed-loop supply chains to reduce environmental impact and comply with safety standards.
What are the niche applications for high-purity mercury?
High-purity mercury is increasingly used in specialized laboratory reagents, semiconductor manufacturing, and high-tech electrical components where precise chemical properties are required.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
