Cooling Tower Market
Cooling Tower Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_702623 | Published On : October 05, 2026 |
Format : 


 | Author : Jonathan Sikka
Cooling Tower Market Size
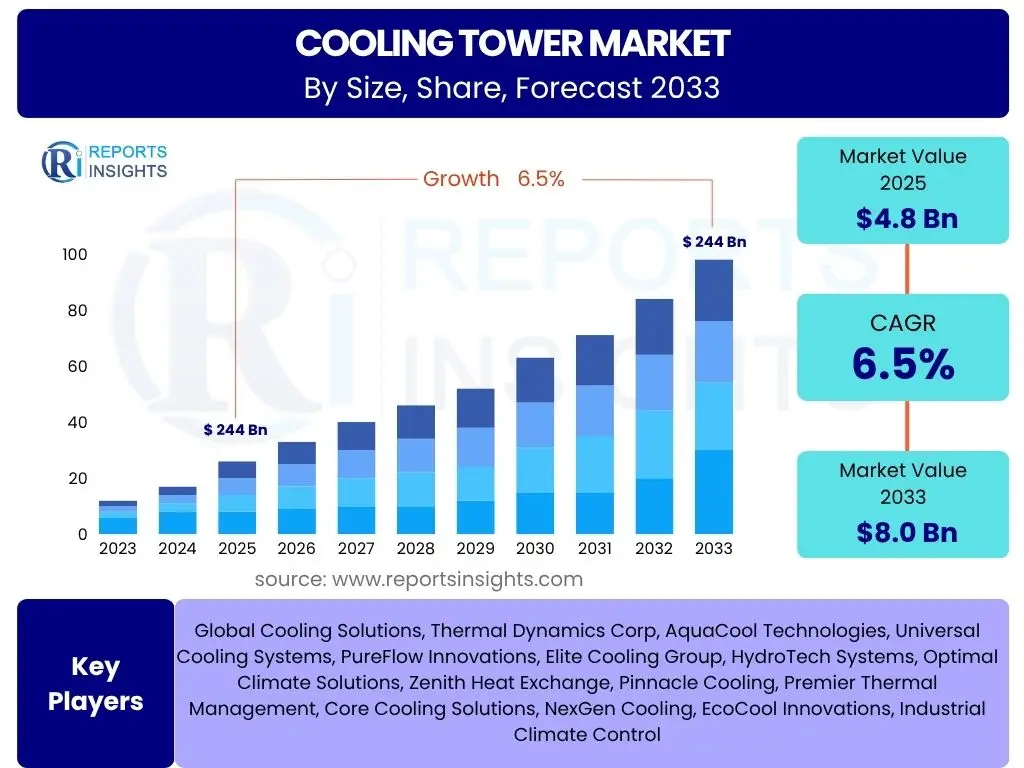
According to Reports Insights Consulting Pvt Ltd, The Cooling Tower Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.1% between 2025 and 2034. The market is estimated at USD 4.39 Billion in 2026 and is projected to reach USD 6.57 Billion by the end of the forecast period in 2034.
Key Cooling Tower Market Trends & Insights
The cooling tower market is undergoing a significant transformation driven by the dual imperatives of industrial efficiency and environmental sustainability. Stakeholders are increasingly focusing on the integration of smart technologies, such as Internet of Things (IoT) sensors and automated control systems, to optimize water usage and energy consumption. Regional demand is shifting heavily toward the Asia-Pacific region due to rapid industrialization and the expansion of the power generation sector. Furthermore, the market is seeing a pivot toward fiberglass reinforced plastic (FRP) and modular designs, which offer superior corrosion resistance and ease of installation compared to traditional wood or concrete structures. Competitive benchmarking indicates that leading companies are investing heavily in hybrid cooling systems that combine the benefits of dry and wet cooling to mitigate water scarcity challenges in arid regions.
- Largest Region: Asia-Pacific remains the largest regional market, accounting for over 35% of the global market share, driven by massive infrastructure projects in China and India.
- Fastest Growing Region: Southeast Asia and parts of the Middle East are expected to witness the highest CAGR due to increasing investments in oil and gas and district cooling applications.
- Largest Segment by Type: Open-circuit cooling towers currently hold the largest market share owing to their high thermal performance and cost-effectiveness in large-scale industrial applications.
- Largest Segment by Application: The Power Generation sector remains the primary consumer of cooling tower technologies, followed closely by the HVAC (Heating, Ventilation, and Air Conditioning) industry.
Key Takeaways Cooling Tower Market Size & Forecast
The cooling tower market is poised for steady growth as global energy demand rises and industrial processes become more complex. The forecast indicates that while traditional heavy industries like chemicals and power remain the bedrock of the market, emerging sectors like data centers and pharmaceutical manufacturing are providing new avenues for high-performance cooling solutions. Market participants are increasingly adopting a lifecycle-cost approach, emphasizing durability and reduced maintenance over low initial capital expenditure. This shift is particularly evident in developed markets where environmental regulations concerning plume abatement and water treatment are becoming more stringent.
- Leading Country: China is the dominant player in both production and consumption, supported by its vast manufacturing base and energy infrastructure.
- Technological Shift: There is a clear trend toward closed-loop systems to prevent process fluid contamination and reduce water treatment costs.
- Material Innovation: FRP is rapidly replacing galvanized steel in mid-sized applications due to its longevity and resistance to harsh chemical environments.
- Environmental Focus: Regulatory pressures such as the Clean Water Act and similar international standards are driving the adoption of drift eliminators and high-efficiency fill media.
Cooling Tower Market Drivers Analysis
The primary driver for the cooling tower market is the escalating global demand for electricity, which necessitates the construction of new thermal and nuclear power plants. Additionally, the rapid expansion of the commercial construction sector, particularly in emerging economies, is fueling the demand for large-scale HVAC systems. Industrial modernization in the chemical and petrochemical sectors also plays a crucial role as facilities upgrade to more efficient cooling technologies to comply with tightening environmental mandates and improve operational margins.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Power Generation Capacity | +1.8% | India, China, Southeast Asia | 2025 - 2034 |
| Growth in Data Center Infrastructure | +1.2% | North America, Northern Europe | 2026 - 2034 |
| Rising Demand for High-Efficiency HVAC Systems | +1.1% | United States, GCC Countries | 2025 - 2030 |
| Industrialization in Emerging Markets | +1.0% | Brazil, Vietnam, Indonesia | 2025 - 2034 |
Cooling Tower Market Restraints Analysis
Market growth is hindered by the high initial investment required for sophisticated cooling systems and the ongoing maintenance costs associated with water treatment and scale prevention. Environmental concerns regarding water consumption and the discharge of thermal effluents also pose significant challenges, leading some industries to explore air-cooled alternatives which may have lower efficiency in high-ambient temperature regions.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Environmental Regulations on Water Usage | -0.7% | European Union, California (USA) | 2025 - 2034 |
| High Operational and Maintenance Costs | -0.5% | Global | 2025 - 2034 |
| Competition from Air-Cooled Heat Exchangers | -0.4% | Middle East, Arid Regions | 2026 - 2034 |
Cooling Tower Market Opportunities Analysis
Significant opportunities lie in the development of hybrid and dry cooling technologies that address water scarcity issues. The integration of AI-driven predictive maintenance and remote monitoring services offers a lucrative service-based revenue stream for manufacturers. Furthermore, the retrofit market is expanding as older industrial facilities seek to upgrade their existing cooling infrastructure to improve energy efficiency and comply with modern environmental standards.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Hybrid Cooling Systems | +1.5% | Middle East, Africa, SW USA | 2027 - 2034 |
| Retrofitting of Aging Industrial Infrastructure | +1.3% | Western Europe, North America | 2025 - 2032 |
| Smart Cooling & IoT Integration | +0.9% | Global | 2026 - 2034 |
Cooling Tower Market Challenges Impact Analysis
One of the foremost challenges is the volatility of raw material prices, particularly steel and specialized resins, which can affect profit margins for manufacturers. Additionally, the risk of Legionella outbreaks and other biological contaminants requires rigorous and costly water management protocols. Balancing the trade-off between water conservation and energy efficiency remains a technical hurdle for engineers designing the next generation of cooling towers.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Fluctuating Raw Material Costs | -0.6% | Global | 2025 - 2028 |
| Health and Safety Concerns (Legionella) | -0.4% | Developed Urban Areas | Ongoing |
| Technological Complexity in Small-Scale Systems | -0.3% | Global | 2025 - 2034 |
Cooling Tower Market - Updated Report Scope
This report provides a comprehensive analysis of the global cooling tower market, covering various technologies, materials, and end-use industries. It evaluates the impact of technological advancements, regulatory shifts, and economic trends across major geographic regions. The scope includes a detailed breakdown of the supply chain, competitive landscape, and future growth prospects through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 4.18 Billion |
| Market Forecast in 2034 | USD 6.57 Billion |
| Growth Rate | 5.1% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Baltimore Aircoil Company, SPX Corporation, GEA Group Aktiengesellschaft, Evapco Inc., Hamon & Cie (International) SA, Enexio Management GmbH, Babcock & Wilcox Enterprises, Bell Cooling Towers, Brentwood Industries Inc., Delta Cooling Towers Inc., Mesan Cooling Tower Ltd., Paharpur Cooling Towers Ltd., Star Cooling Towers, REYMSA Cooling Towers Inc., Kelvion Holding GmbH, Liang Chi Industry Co. Ltd., Thermal Care Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The cooling tower market is segmented based on technology, design, material, and end-use application. Each segment is influenced by different operational requirements and regional environmental conditions. For instance, the transition from wet to dry or hybrid cooling is most pronounced in regions where water rights are expensive or limited. Material choices are largely dictated by the chemical composition of the process water and the environmental conditions of the installation site.
- By Type: Evaporative cooling towers dominate the market due to their thermal efficiency, but dry cooling is gaining traction in water-stressed areas. Hybrid systems are emerging as a premium solution for plume abatement and water conservation.
- By Design: Mechanical draft towers, specifically induced draft configurations, are the most common due to their versatility and smaller footprint compared to natural draft towers, which are primarily used in massive power plants.
- By Material: While concrete remains the standard for very large natural draft towers, FRP is the fastest-growing segment for industrial and HVAC applications due to its corrosion resistance and lightweight properties.
- By Application: Power generation is the largest consumer, while the HVAC segment is seeing rapid growth due to urbanization and the construction of smart buildings and data centers.
Regional Highlights
- Asia-Pacific: The undisputed leader in market share, driven by rapid industrialization in China, India, and Vietnam. It is both the largest and fastest-growing market globally.
- North America: A mature market focused on replacement, retrofitting, and the expansion of data centers. Efficiency and environmental compliance are the primary market drivers here.
- Europe: Characterized by stringent environmental regulations and a focus on sustainable industrial practices. Germany and France are key hubs for technological innovation in cooling systems.
- Middle East and Africa: Growing demand for district cooling and oil and gas processing. Water scarcity is a significant driver for dry and hybrid cooling technologies in this region.
- Latin America: Steady growth driven by mining and food processing industries, particularly in Brazil and Chile.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Cooling Tower Market.- Baltimore Aircoil Company
- SPX Corporation
- GEA Group Aktiengesellschaft
- Evapco Inc.
- Hamon & Cie (International) SA
- Enexio Management GmbH
- Babcock & Wilcox Enterprises
- Bell Cooling Towers
- Brentwood Industries Inc.
- Delta Cooling Towers Inc.
- Mesan Cooling Tower Ltd.
- Paharpur Cooling Towers Ltd.
- Star Cooling Towers
- REYMSA Cooling Towers Inc.
- Kelvion Holding GmbH
- Liang Chi Industry Co. Ltd.
- Thermal Care Inc.
Frequently Asked Questions
What is the current size of the global cooling tower market?
The global cooling tower market is estimated to be worth approximately USD 4.18 Billion in 2025 and is projected to grow to USD 6.57 Billion by 2034.
Which industry is the largest user of cooling towers?
The Power Generation industry is the largest consumer of cooling towers, followed by the HVAC and Chemical/Petrochemical sectors.
What are the main factors driving the growth of the cooling tower market?
Growth is primarily driven by increasing electricity demand, the rise of hyperscale data centers, and the expansion of the commercial HVAC sector globally.
Why is Fiberglass Reinforced Plastic (FRP) becoming popular for cooling towers?
FRP is gaining popularity because it offers superior resistance to corrosion and chemicals, is lightweight for easier installation, and has a longer lifespan than wood or galvanized steel.
Which region is expected to grow the fastest during the forecast period?
The Asia-Pacific region, led by China and India, is expected to be the fastest-growing market due to massive investments in industrial infrastructure and power utilities.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
