Composite Materials Aluminum Alloys Aerospace Market
Composite Materials Aluminum Alloys Aerospace Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711391 | Published On : October 30, 2026 |
Format : 


 | Author : Ashraf Shehata
Composite Materials Aluminum Alloys Aerospace Market Size
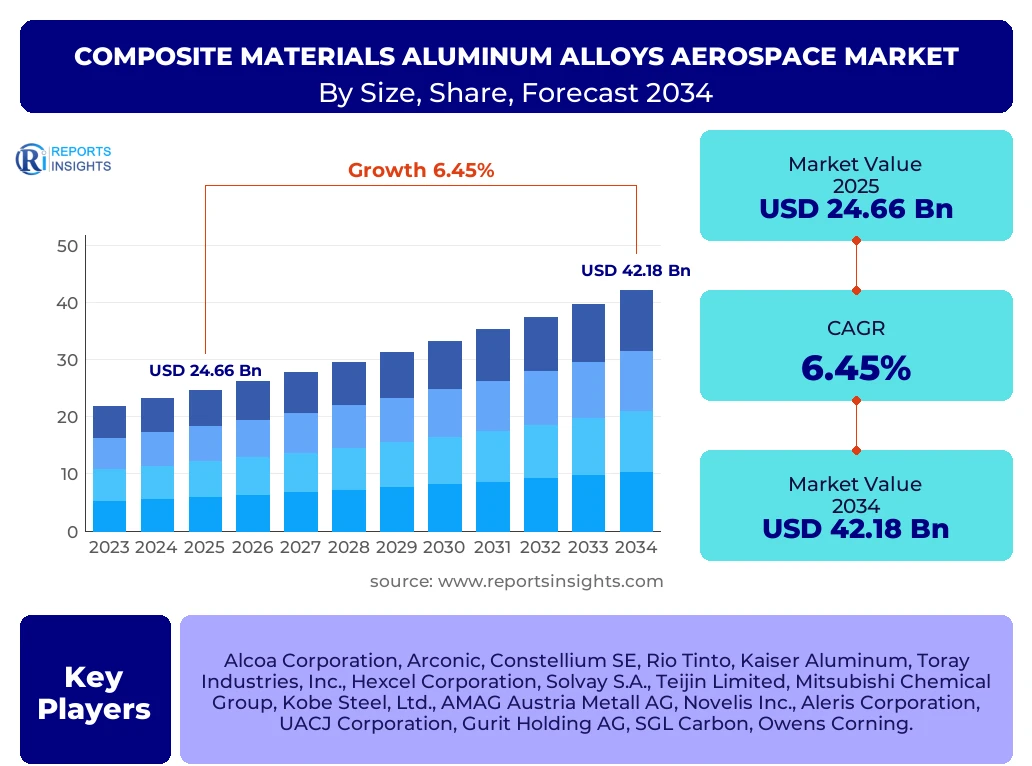
According to Reports Insights Consulting Pvt Ltd, The Composite Materials Aluminum Alloys Aerospace Market is projected to grow at a Compound Growth Rate (CAGR) of 6.45% between 2025 and 2034. The market is estimated at USD 26.25 Billion in 2026 and is projected to reach USD 42.18 Billion by the end of the forecast period in 2034. This growth is underpinned by the aggressive transition within the aerospace sector toward next-generation aircraft that demand an optimal balance of structural integrity, weight reduction, and fuel efficiency.
The convergence of advanced metallurgical engineering and polymer science has led to the proliferation of hybrid material solutions. Aluminum alloys, particularly the 2XXX and 7XXX series, remain the cornerstone of aerospace structural components due to their proven reliability and cost-effectiveness. However, the integration of composite materials such as Carbon Fiber Reinforced Polymers (CFRP) alongside advanced Aluminum-Lithium (Al-Li) alloys is redefining the architecture of modern airframes. The market is characterized by intense research and development focused on improving the fatigue resistance and corrosion protection of these material systems to meet the rigorous safety standards of global aviation authorities.
Key Composite Materials Aluminum Alloys Aerospace Market Trends & Insights
Current market dynamics are heavily influenced by the aerospace industry’s commitment to decarbonization and the subsequent demand for lightweighting. Industry stakeholders are increasingly looking toward Aluminum-Lithium alloys as a viable alternative to traditional aluminum, offering up to 10% weight reduction and improved stiffness. Furthermore, the rise of additive manufacturing is allowing for the production of complex geometries in aluminum alloys that were previously impossible, reducing part count and assembly time. Regional insights indicate a significant shift in production capacity toward the Asia-Pacific region, driven by the expansion of local aircraft manufacturing programs in China and India.
- Largest Region: North America remains the dominant market shareholder due to the presence of major aerospace OEMs and a mature supply chain for advanced materials.
- Fastest Growing Region: Asia-Pacific is expected to exhibit the highest CAGR, propelled by increasing defense expenditures and the rapid expansion of the commercial aviation sector in emerging economies.
- Largest Segment by Material: Aluminum-Lithium (Al-Li) alloys are capturing significant market share as a preferred alternative to standard composites for specific fuselage and wing applications.
- Leading Application: Commercial aviation continues to be the largest end-use segment, driven by the massive backlog of narrow-body and wide-body aircraft orders globally.
Key Takeaways Composite Materials Aluminum Alloys Aerospace Market Size & Forecast
The market trajectory for aerospace composite materials and aluminum alloys is shaped by the dual pressures of economic efficiency and environmental sustainability. The forecast period anticipates a move toward circularity, where the recyclability of aluminum alloys offers a competitive edge over thermoset composites that are traditionally difficult to reclaim. Key takeaways suggest that the integration of high-performance alloys with localized composite reinforcement—often referred to as Fiber Metal Laminates (FML)—will provide the necessary structural gains for the next generation of ultra-efficient aircraft. Strategic partnerships between material science firms and aerospace manufacturers are becoming the norm to de-risk the adoption of these advanced material systems.
- Leading Country: The United States leads in both consumption and technological innovation, supported by a robust defense sector and the headquarters of global aviation giants.
- Material Substitution: While composites have seen massive adoption in wide-body aircraft like the 787 and A350, advanced aluminum alloys are making a comeback in narrow-body configurations due to better production scalability.
- Defense Influence: Military modernization programs in Europe and the Middle East are serving as primary catalysts for high-strength aluminum alloy demand.
- Supply Chain Resilience: Diversification of raw material sources, particularly for alloying elements like Scandium and Lithium, is a critical strategic priority for market leaders.
Composite Materials Aluminum Alloys Aerospace Market Drivers Analysis
The primary driver for the Composite Materials Aluminum Alloys Aerospace market is the unrelenting pursuit of fuel efficiency. As jet fuel costs fluctuate and carbon taxes become more prevalent, airlines are prioritizing aircraft that offer the lowest possible operational cost per seat-mile. Lightweighting remains the most effective method to achieve these goals, pushing OEMs to replace heavier traditional steel and standard aluminum components with advanced composites and high-strength alloys. Additionally, the recovery of global air travel to pre-pandemic levels has led to a surge in new aircraft orders, creating a consistent demand for raw material inputs and processed components across the global supply chain.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Demand for Fuel-Efficient Aircraft | +2.4% | Global | 2025-2034 |
| Increased Defense Spending and Modernization | +1.8% | USA, China, India, Russia | 2025-2030 |
| Growth of Additive Manufacturing (3D Printing) | +1.1% | Europe and North America | 2026-2034 |
Composite Materials Aluminum Alloys Aerospace Market Restraints Analysis
Despite the growth prospects, the market faces significant restraints, primarily revolving around the high cost of advanced materials and the complexity of manufacturing. Aluminum-Lithium alloys, for instance, require specialized processing environments to prevent oxidation, which increases capital expenditure for manufacturers. Furthermore, the certification process for new materials in the aerospace sector is notoriously slow and expensive, often taking a decade or more to move from the lab to a commercial airframe. Fluctuating prices of raw materials, such as carbon fiber precursors and alloying metals, also introduce volatility into the profit margins of Tier 1 and Tier 2 suppliers.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Production and Processing Costs | -1.5% | Global | 2025-2034 |
| Strict Regulatory and Certification Standards | -0.9% | Europe and North America | 2025-2030 |
Composite Materials Aluminum Alloys Aerospace Market Opportunities Analysis
The emergence of Advanced Air Mobility (AAM), including electric Vertical Take-off and Landing (eVTOL) aircraft, represents a massive opportunity for the material sector. These platforms require exceptionally lightweight materials to maximize battery life and payload capacity, creating a new niche for high-performance aluminum alloys and thermoplastic composites. Furthermore, the trend toward sustainable aviation fuel (SAF) and hydrogen propulsion is prompting a redesign of fuel storage systems, where specialized composite-alloy cryogenic tanks are expected to see high demand. Expansion into space exploration also offers a frontier for radiation-hardened composite materials and ultra-high-temperature aluminum alloys.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of eVTOL and Urban Air Mobility | +1.9% | Global (Urban Hubs) | 2027-2034 |
| Advancements in Hydrogen Propulsion Storage | +1.3% | Europe (EU Hydrogen Strategy) | 2028-2034 |
Composite Materials Aluminum Alloys Aerospace Market Challenges Impact Analysis
One of the most pressing challenges is the environmental impact of composite manufacturing and the lack of efficient recycling infrastructure for carbon fiber materials. Unlike aluminum, which has a well-established secondary market and high recyclability, end-of-life composites often end up in landfills, creating a sustainability gap for OEMs. Additionally, the global supply chain remains vulnerable to geopolitical tensions, which can disrupt the supply of critical minerals like lithium and scandium. The shortage of a specialized workforce capable of handling advanced composite layups and high-precision alloy machining also presents a bottleneck for production scaling.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Recyclability of Composite Materials | -0.7% | Europe and Japan | 2025-2034 |
| Geopolitical Disruptions in Raw Material Supply | -1.2% | Global | 2025-2028 |
Composite Materials Aluminum Alloys Aerospace Market - Updated Report Scope
The scope of this market research report encompasses a deep-dive analysis of the various material types, application areas, and geographic regions defining the aerospace material landscape. It provides a detailed breakdown of the interplay between traditional aluminum alloys and the rising adoption of advanced composites. The report analyzes the strategic positioning of key market players and the technological shifts driving the transition from 2025 toward 2034. It includes historical data from 2020 to 2024 to provide context on the market's recovery and future trajectory.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 24.66 Billion |
| Market Forecast in 2034 | USD 42.18 Billion |
| Growth Rate | 6.45% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Alcoa Corporation, Arconic, Constellium SE, Rio Tinto, Kaiser Aluminum, Toray Industries, Inc., Hexcel Corporation, Solvay S.A., Teijin Limited, Mitsubishi Chemical Group, Kobe Steel, Ltd., AMAG Austria Metall AG, Novelis Inc., Aleris Corporation, UACJ Corporation, Gurit Holding AG, SGL Carbon, Owens Corning. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Composite Materials Aluminum Alloys Aerospace Market reflects the diverse engineering requirements across different aircraft platforms. The material type remains the primary differentiator, where the choice between alloys and composites depends on the specific performance requirements of the component, such as tension-dominated wing skins or compression-loaded fuselage panels. Application-based segmentation highlights the increasing use of advanced materials in the engine housing to handle high thermal and mechanical stresses.
- By Material Type:
- Aluminum Alloys: 2XXX Series, 6XXX Series, 7XXX Series, Aluminum-Lithium Alloys
- Composites: Carbon Fiber Reinforced Polymer (CFRP), Glass Fiber Reinforced Polymer (GFRP), Aramid Fiber Reinforced Polymer (AFRP)
- By Application:
- Airframe: Fuselage, Wings, Empennage
- Interior: Floor Panels, Overhead Bins, Seating Structures
- Propulsion Systems: Engine Casings, Fan Blades
- By Platform:
- Commercial Aviation
- Military Aviation
- Business and General Aviation
- Unmanned Aerial Vehicles (UAVs)
Regional Highlights
- North America: Currently the largest market by value, driven by high demand for fleet renewal and the heavy presence of the Boeing supply chain. The United States is the primary hub for technological innovation in advanced alloys.
- Europe: The second-largest market, characterized by strong regulatory support for sustainable materials and the presence of Airbus and its extensive partner network. Countries like France, Germany, and the UK are leaders in composite R&D.
- Asia-Pacific: The fastest-growing region, with China and India investing heavily in domestic aerospace programs (e.g., COMAC). The region is becoming a manufacturing powerhouse for aerospace aluminum.
- Middle East: A significant market for wide-body aircraft components due to the dominance of long-haul carriers, driving demand for advanced materials in engine and fuselage applications.
- Latin America & MEA: These regions are emerging as important markets for maintenance, repair, and overhaul (MRO) activities, increasing the demand for replacement material components.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Composite Materials Aluminum Alloys Aerospace Market.- Alcoa Corporation
- Arconic
- Constellium SE
- Rio Tinto
- Kaiser Aluminum
- Toray Industries, Inc.
- Hexcel Corporation
- Solvay S.A.
- Teijin Limited
- Mitsubishi Chemical Group
- Kobe Steel, Ltd.
- AMAG Austria Metall AG
- Novelis Inc.
- Aleris Corporation
- UACJ Corporation
- Gurit Holding AG
- SGL Carbon
- Owens Corning
- Spirit AeroSystems
- Park Aerospace Corp.
Frequently Asked Questions
What is the main advantage of using Aluminum-Lithium alloys over traditional aerospace aluminum?
Aluminum-Lithium (Al-Li) alloys offer a lower density (approximately 2-5% lower) and a higher elastic modulus (up to 5-6% higher) compared to traditional 2XXX or 7XXX series alloys. This provides a significant weight reduction (up to 10%) while maintaining or improving the structural stiffness and fatigue resistance of the aircraft component.
Why is the aerospace industry shifting toward composite materials despite their higher cost?
The shift is primarily driven by the superior strength-to-weight ratio of composites like CFRP, which enables significant fuel savings and reduced CO2 emissions. Composites also offer excellent corrosion and fatigue resistance, which translates to lower maintenance costs and longer service lives for airframes.
Which region is expected to lead the growth of the aerospace materials market through 2034?
The Asia-Pacific region is projected to be the fastest-growing market. This growth is fueled by increasing air passenger traffic, the expansion of low-cost carriers, and the development of indigenous aircraft manufacturing capabilities in countries like China and India.
What role does 3D printing play in the Composite Materials Aluminum Alloys Aerospace market?
Additive manufacturing or 3D printing allows for the production of lightweight, complex aluminum alloy parts that reduce waste (buy-to-fly ratio) and enable the consolidation of multiple parts into a single component. This reduces assembly time and overall weight while optimizing material distribution for stress loads.
How are sustainability goals affecting the choice of materials in aircraft design?
Sustainability is forcing a focus on "cradle-to-cradle" lifecycles. This favors aluminum alloys due to their high recyclability compared to thermoset composites. However, researchers are developing recyclable thermoplastic composites and bio-based resins to address the environmental impact of traditional composite materials.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
