Communications Test And Measurement Market
Communications Test And Measurement Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711916 | Published On : November 21, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Communications Test And Measurement Market Size
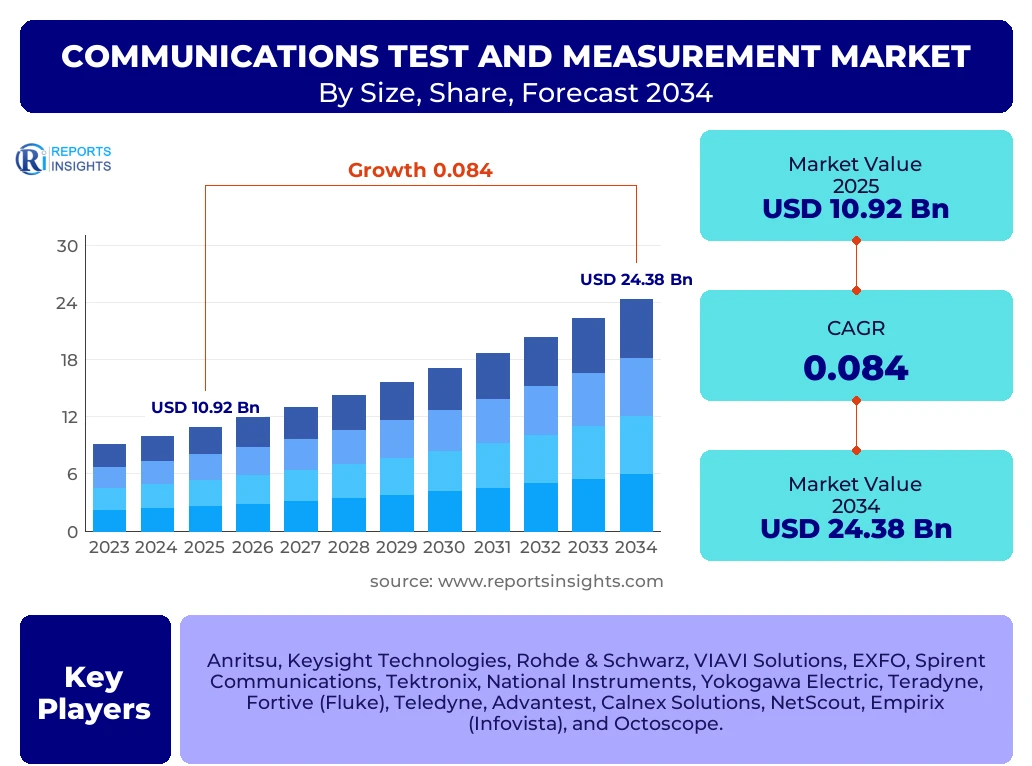
According to Reports Insights Consulting Pvt Ltd, The Communications Test And Measurement Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.4% between 2025 and 2034. The market is estimated at USD 11.82 Billion in 2026 and is projected to reach USD 24.38 Billion by the end of the forecast period in 2034.
Key Communications Test And Measurement Market Trends & Insights
The global communications test and measurement landscape is undergoing a radical transformation, primarily catalyzed by the global transition from legacy network infrastructures to high-capacity 5G and fiber-to-the-home (FTTH) architectures. As network complexity intensifies with the introduction of Open Radio Access Networks (O-RAN) and software-defined networking (SDN), the demand for sophisticated diagnostic tools that can validate performance across heterogeneous environments has reached an all-time high. Stakeholders are increasingly prioritizing real-time analytics and automated testing protocols to manage the surge in data traffic and the proliferation of Internet of Things (IoT) devices. Regional analysis suggests that while North America remains a stronghold for R&D-led testing, the Asia-Pacific region is emerging as the primary engine for volume-driven growth due to massive state-backed infrastructure projects.
- Largest Region: North America remains the dominant revenue contributor, accounting for approximately 35% of the total market share, driven by early 5G adoption and a robust presence of tier-1 network equipment manufacturers.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR during the forecast period, fueled by rapid industrialization in China, India, and Southeast Asia.
- Largest Segment by Share: The wireless test and measurement segment leads the market, necessitated by the global rollout of 5G NR (New Radio) and the subsequent need for rigorous spectral efficiency testing.
- Shift toward Software-as-a-Service (SaaS): There is a marked trend toward virtualized testing solutions that reduce the reliance on expensive, localized hardware in favor of scalable cloud-based diagnostic platforms.
Key Takeaways Communications Test And Measurement Market Size & Forecast
The forecast period for the communications test and measurement market is defined by a strategic shift from standard connectivity validation to holistic service assurance. Enterprise-level stakeholders are moving beyond basic signal testing toward comprehensive end-to-end performance monitoring that encompasses latency, throughput, and security. The integration of Artificial Intelligence (AI) and Machine Learning (ML) into testing equipment is no longer an outlier but a standard requirement for managing the predictive maintenance of complex 5G ecosystems. Furthermore, the convergence of telecommunications and satellite communications (Non-Terrestrial Networks) is creating a new frontier for test and measurement protocols, requiring hardware that can operate across wider frequency bands and harsher environments.
- 5G Dominance: The 5G segment is expected to be the primary revenue driver, as operators transition from Non-Standalone (NSA) to Standalone (SA) architectures.
- Automation and AI: AI-driven automated testing is significantly reducing operational expenditures (OPEX) for service providers by accelerating the identification of network bottlenecks.
- Strategic Lead: The United States and China are the primary centers for innovation, collectively holding a majority of the intellectual property in high-frequency testing equipment.
- Rise of O-RAN: The adoption of Open RAN is increasing the demand for multi-vendor interoperability testing, a niche segment seeing rapid expansion.
Communications Test And Measurement Market Drivers Analysis
The primary catalysts for the communications test and measurement market revolve around the exponential increase in data consumption and the critical need for ultra-reliable low-latency communication (URLLC). As industries such as autonomous driving, healthcare, and smart manufacturing integrate 5G, the margin for error in network performance becomes virtually non-existent, necessitating advanced testing solutions.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Global 5G Standalone (SA) Deployment | +3.2% | Global (Strongest in US, South Korea, China) | 2025 - 2030 |
| Proliferation of IoT and Connected Devices | +2.1% | Europe and Asia Pacific | 2025 - 2034 |
| Transition to 400G/800G Optical Networks | +1.8% | North America and Western Europe | 2026 - 2032 |
| Government Initiatives for Smart Cities | +1.3% | India, Saudi Arabia, UAE | 2027 - 2034 |
Communications Test And Measurement Market Restraints Analysis
Despite robust growth, the market faces significant headwinds, primarily related to the high capital intensity of modern testing equipment. The rapid evolution of standards means that hardware can become obsolete quickly, leading to cautious spending among smaller service providers and regional operators in emerging economies.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Procurement and Maintenance Costs | -1.5% | Emerging Markets (Latin America, Africa) | 2025 - 2034 |
| Complexity in Testing Multi-vendor Environments | -1.1% | Global | 2025 - 2029 |
| Short Lifecycles of Technology Standards | -0.8% | Technologically Advanced Nations | 2026 - 2030 |
Communications Test And Measurement Market Opportunities Analysis
The transition toward 6G research and the integration of satellite-based internet services present massive untapped potential for the industry. Companies that can provide seamless testing transitions between terrestrial and non-terrestrial networks are positioned for significant competitive advantage in the coming decade.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Early 6G Research and Prototyping | +2.5% | Japan, South Korea, USA | 2029 - 2034 |
| Expansion of Satellite Broadband (LEO Constellations) | +1.9% | Global (Led by North America) | 2025 - 2034 |
| Adoption of Private 5G for Industrial IoT | +1.4% | Germany, China, Japan | 2025 - 2032 |
Communications Test And Measurement Market Challenges Impact Analysis
The primary challenge lies in the talent gap and the integration of legacy systems with modern virtualized architectures. As the industry moves toward software-defined everything, the traditional mechanical skills of technicians must evolve into data science and network programming proficiencies.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Lack of Skilled Professionals for Advanced Diagnostics | -1.2% | Global (Severe in Developing Regions) | 2025 - 2034 |
| Geopolitical Trade Restrictions on Semi-conductors | -1.4% | USA, China, Taiwan | 2025 - 2028 |
| Interoperability issues in Heterogeneous Networks | -0.9% | Europe and Asia | 2025 - 2030 |
Communications Test And Measurement Market - Updated Report Scope
This report provides a granular examination of the communications test and measurement market, encompassing the entire ecosystem from hardware components and specialized software to consulting and managed services. It evaluates the impact of technological transitions across multiple end-user verticals, including telecommunications providers, aerospace and defense, and large-scale enterprises. The scope includes an in-depth analysis of regulatory frameworks, spectral allocation trends, and the competitive landscape of the top tier-1 and tier-2 players globally.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 10.92 Billion |
| Market Forecast in 2034 | USD 24.38 Billion |
| Growth Rate | 8.4% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Anritsu, Keysight Technologies, Rohde & Schwarz, VIAVI Solutions, EXFO, Spirent Communications, Tektronix, National Instruments, Yokogawa Electric, Teradyne, Fortive (Fluke), Teledyne, Advantest, Calnex Solutions, NetScout, Empirix (Infovista), and Octoscope. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented to reflect the diverse technological requirements across different communication mediums. The hardware segment continues to hold the largest value share due to the high cost of spectrum analyzers and signal generators, while the software and services segments are growing at a faster rate due to the industry’s shift toward virtualization. Service providers represent the largest end-user group as they constantly upgrade infrastructure to maintain Quality of Service (QoS) and Quality of Experience (QoE) for end consumers.
- By Component:
- Hardware (Spectrum Analyzers, Oscilloscopes, Signal Generators, Network Analyzers)
- Software (Network Performance Monitoring, Automated Test Tools)
- Services (Managed Services, Professional Services, Repair/Calibration)
- By Test Type:
- Wireless (5G NR, LTE, Wi-Fi 6/7, Bluetooth)
- Wireline (Fiber Optics, Ethernet, Broadband)
- By Network Type:
- Legacy Networks (2G/3G)
- 4G/LTE
- 5G (Standalone and Non-Standalone)
- By End-User:
- Network Equipment Manufacturers (NEMs)
- Telecommunication Service Providers
- Enterprises (Healthcare, Automotive, Manufacturing, Aerospace & Defense)
Regional Highlights
The regional distribution of the communications test and measurement market is highly correlated with the maturity of digital infrastructure and national spectrum policies. North America and Europe are focusing heavily on enhancing security and reliability in 5G and fiber networks, while Asia-Pacific is experiencing a surge in demand due to the sheer volume of mobile subscribers and the expansion of the regional manufacturing base for telecommunications hardware.
- North America: The largest market globally, characterized by high investment in 5G SA and private 5G networks for the industrial sector. The U.S. remains the primary hub for leading test and measurement vendors.
- Asia-Pacific: The fastest-growing region, with China, Japan, and South Korea leading in 5G infrastructure. India is emerging as a critical growth node due to the massive rollout of 5G services and government-led connectivity programs.
- Europe: Driven by strict regulatory standards for network quality and the transition to high-speed optical fiber in countries like Germany, France, and the UK.
- Middle East & Africa: Rapidly growing interest in smart city projects and high-speed mobile connectivity in the GCC countries is driving the demand for advanced testing protocols.
- Latin America: Gradual growth as countries like Brazil and Mexico begin to auction 5G spectrum and modernize their legacy wireline infrastructures.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Communications Test And Measurement Market.- Anritsu Corporation
- Keysight Technologies, Inc.
- Rohde & Schwarz GmbH & Co KG
- VIAVI Solutions Inc.
- EXFO Inc.
- Spirent Communications plc
- Tektronix, Inc. (Fortive)
- National Instruments Corporation (Emerson)
- Yokogawa Electric Corporation
- Teradyne Inc.
- Fluke Corporation
- Teledyne Technologies Incorporated
- Advantest Corporation
- Calnex Solutions plc
- NetScout Systems, Inc.
- Infovista
- Adantest Corporation
- Spirent Communications
- Octoscope (Spirent)
- GL Communications Inc.
Frequently Asked Questions
What is driving the growth of the Communications Test And Measurement Market?
The market is primarily driven by the global rollout of 5G infrastructure, the expansion of IoT ecosystems, and the increasing demand for high-speed fiber-optic networks. Additionally, the move toward automated and AI-driven network diagnostics to reduce operational costs is a significant growth factor.
Which region holds the largest share of the Communications Test And Measurement Market?
North America currently holds the largest share due to early technological adoption and the presence of major telecommunications companies. However, Asia-Pacific is the fastest-growing region owing to massive infrastructure projects in China and India.
What are the key challenges in the Communications Test And Measurement Market?
High equipment costs, the complexity of testing multi-vendor environments in Open RAN architectures, and a global shortage of skilled professionals capable of operating advanced diagnostic software are the primary challenges facing the market.
How is AI impacting the Communications Test And Measurement sector?
AI is being integrated into testing tools to enable predictive maintenance, automated anomaly detection, and real-time network optimization. This helps service providers identify and resolve issues before they impact the end-user experience, thereby increasing efficiency.
What is the future outlook for 6G testing?
While 5G remains the current focus, major players are already investing in R&D for 6G testing equipment. This includes exploring higher frequency bands (sub-terahertz) and developing testing protocols for non-terrestrial and satellite-integrated communication systems.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
