Tail Spend Management Solutions Market
Tail Spend Management Solutions Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711884 | Published On : November 20, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Tail Spend Management Solutions Market Size
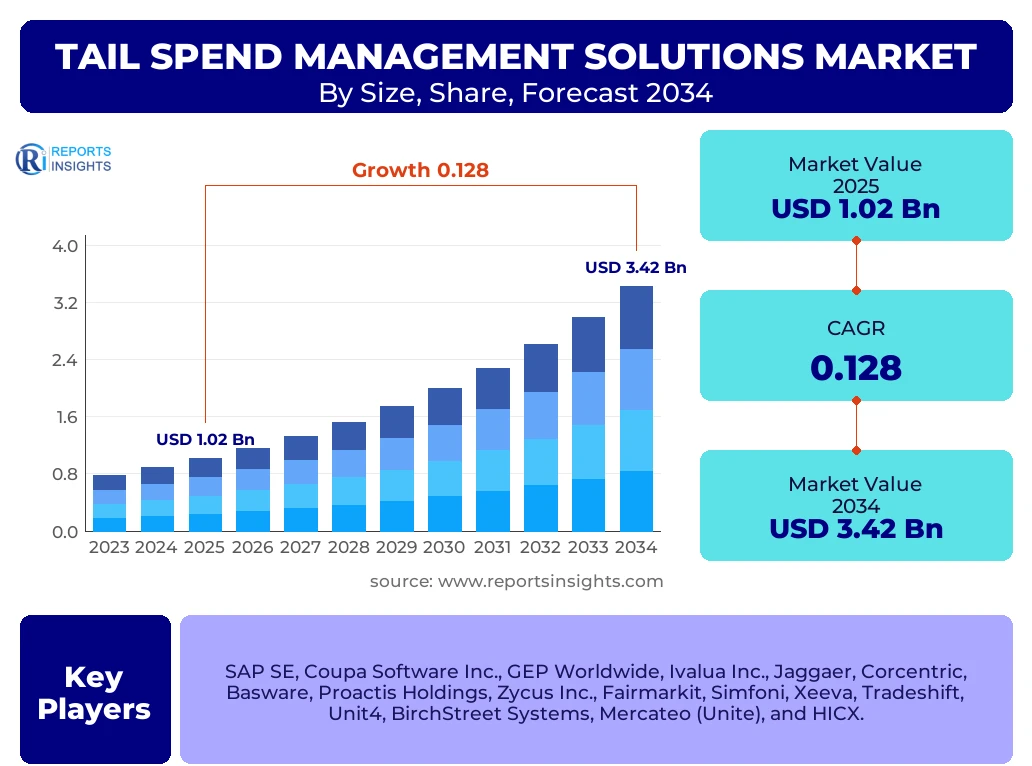
According to Reports Insights Consulting Pvt Ltd, The Tail Spend Management Solutions Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 12.8% between 2025 and 2034. The market is estimated at USD 1.15 Billion in 2026 and is projected to reach USD 3.42 Billion by the end of the forecast period in 2034.
The global Tail Spend Management Solutions Market is undergoing a significant structural transformation as organizations pivot from traditional procurement frameworks to high-velocity, data-centric models. Tail spend, typically defined as the bottom 20% of a company’s spend that accounts for nearly 80% of its supplier base, has historically been neglected due to its fragmented nature and low individual transaction value. However, the emergence of sophisticated SaaS platforms and AI-driven analytics has enabled procurement officers to capture substantial cost savings and operational efficiencies that were previously considered unreachable.
In the current fiscal landscape, enterprise-level stakeholders are increasingly viewing tail spend management not merely as a cost-reduction exercise but as a strategic imperative for risk mitigation and supplier diversification. The integration of Natural Language Processing (NLP) and Machine Learning (ML) into procurement suites allows for the automated categorization of disparate spend data, providing visibility into Maverick spending and unauthorized vendor engagement. As businesses strive for leaner operations in a post-pandemic economy, the demand for end-to-end solutions that offer "Amazon-like" guided buying experiences is accelerating, driving the market toward a multi-billion dollar valuation by the end of the decade.
Key Tail Spend Management Solutions Market Trends & Insights
The market is currently being reshaped by the convergence of cloud computing, predictive analytics, and a heightened focus on Environmental, Social, and Governance (ESG) compliance. Users are increasingly inquiring about the role of automated "spot-buy" platforms and the ability of these solutions to integrate with legacy ERP systems. Market intelligence suggests a strong shift toward "Procure-to-Pay" (P2P) ecosystems that incorporate built-in tail spend modules, reducing the need for standalone third-party interventions. Competitive benchmarking reveals that leading players are differentiating themselves through superior UI/UX and mobile-first accessibility to cater to a decentralized workforce.
- North America is currently the largest regional market, driven by high digital maturity and early adoption of cloud-based procurement technologies across Fortune 500 companies.
- The Asia-Pacific region is the fastest-growing market, fueled by rapid industrialization in India and China and the digitization of Small and Medium Enterprises (SMEs).
- The Software-as-a-Service (SaaS) segment holds the largest market share in terms of solution type, as enterprises favor subscription-based models for lower upfront capital expenditure and seamless updates.
- The Manufacturing sector represents the largest industry segment, necessitated by the high volume of indirect spending and the complexity of maintenance, repair, and operations (MRO) supplies.
- Integration of Generative AI for contract analysis and supplier negotiation is emerging as a critical trend that is expected to redefine the competitive landscape within the next 24 months.
Key Takeaways Tail Spend Management Solutions Market Size & Forecast
Comprehensive analysis of user queries and market dynamics indicates that the forecast for tail spend management is heavily influenced by the global push for procurement transparency and the reduction of invisible spend. Organizations are shifting away from manual spreadsheets toward real-time dashboards that provide actionable insights into vendor performance and pricing anomalies. The forecast period 2025–2034 is expected to witness a consolidation phase where larger procurement suites acquire niche tail spend startups to offer holistic spend management capabilities. Stakeholders are particularly focused on the ROI of these solutions, with many reporting a 5% to 15% reduction in total indirect spend within the first year of implementation.
- United States and Germany lead in terms of technological infrastructure, providing a robust foundation for advanced spend analytics deployment.
- The SME segment is anticipated to witness the highest growth rate as user-friendly, affordable cloud solutions lower the barrier to entry for smaller firms.
- Data enrichment and cleansing are identified as the most critical prerequisites for successful tail spend management, leading to increased investment in data services.
- Managed Services models are gaining traction among organizations that prefer to outsource the tactical handling of the long-tail supplier base to specialized consultants.
- The forecast highlights a significant uptick in the use of e-marketplaces as a primary vehicle for managing tail spend transactions, ensuring pre-negotiated rates and compliant purchasing.
Tail Spend Management Solutions Market Drivers Analysis
The primary catalysts for the Tail Spend Management Solutions market include the urgent need for organizational cost optimization and the digital transformation of procurement departments. As global supply chains face volatility, the ability to manage small-scale, tactical purchases with the same rigor as strategic spend has become a major differentiator for profitable enterprises.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Advancements in AI and ML Analytics | +3.2% | Global (Strongest in North America) | 2025 - 2034 |
| Demand for Procurement Transparency and ESG Compliance | +2.5% | European Union and United Kingdom | 2025 - 2030 |
| Rise of Remote and Decentralized Workforces | +2.1% | Global | 2025 - 2034 |
| Pressure to Reduce Indirect Spend Leakage | +1.8% | Asia Pacific (China, India) | 2026 - 2032 |
Tail Spend Management Solutions Market Restraints Analysis
Despite the positive growth trajectory, the market faces hurdles such as high initial implementation costs and deep-seated cultural resistance within procurement teams. The complexity of integrating these solutions with fragmented, legacy IT architectures often results in prolonged deployment timelines, which can deter potential adopters.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration Challenges with Legacy ERP Systems | -1.5% | Global | 2025 - 2028 |
| Data Security and Privacy Concerns | -1.2% | North America and Europe | 2025 - 2034 |
| High Initial Cost for Premium Solutions | -0.8% | MEA and Latin America | 2025 - 2030 |
Tail Spend Management Solutions Market Opportunities Analysis
The evolution of B2B e-commerce and the increasing accessibility of predictive analytics present substantial growth opportunities. By leveraging big data, solution providers can offer forward-looking insights that help procurement managers anticipate supply disruptions and negotiate better terms with high-volume tail suppliers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of B2B E-Marketplaces | +2.8% | Global | 2026 - 2034 |
| Tailored Solutions for SMEs | +2.2% | Emerging Economies (SE Asia, India) | 2027 - 2034 |
| Blockchain for Supplier Verification | +1.4% | Global | 2028 - 2034 |
Tail Spend Management Solutions Market Challenges Impact Analysis
Maintaining data quality across thousands of unmanaged suppliers remains a primary challenge. Furthermore, the rapid pace of technological change requires continuous upskilling of the workforce, which can be a significant burden for organizations with limited training budgets.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Data Silos and Fragmented Information | -1.1% | Global | 2025 - 2034 |
| Resistance to Change in Procurement Culture | -0.9% | Japan and parts of Europe | 2025 - 2030 |
| Rapid Technological Obsolescence | -0.6% | Global | 2026 - 2034 |
Tail Spend Management Solutions Market - Updated Report Scope
This report provides an exhaustive analysis of the global Tail Spend Management Solutions market, covering technological advancements, competitive dynamics, and regional economic factors. The scope includes a detailed breakdown of software vs. services, deployment modes, and end-user verticals, ensuring stakeholders have a 360-degree view of the industry.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.02 Billion |
| Market Forecast in 2034 | USD 3.42 Billion |
| Growth Rate | 12.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | SAP SE, Coupa Software Inc., GEP Worldwide, Ivalua Inc., Jaggaer, Corcentric, Basware, Proactis Holdings, Zycus Inc., Fairmarkit, Simfoni, Xeeva, Tradeshift, Unit4, BirchStreet Systems, Mercateo (Unite), and HICX. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Tail Spend Management Solutions market highlights the diverse needs of modern enterprises. The market is primarily split between software solutions that offer automated tools for spend visibility and services that provide expert-led management of supplier relationships. Large enterprises currently dominate the market share due to their complex procurement needs, but the SME segment is gaining rapid momentum through the adoption of scalable, modular cloud solutions.
- By Solution Type:
- Software: Includes spend analytics, e-sourcing tools, and contract management modules. This segment is the primary engine of market growth.
- Services: Encompasses procurement outsourcing and strategic consulting to optimize the "long tail" of suppliers.
- By Deployment Mode:
- Cloud-Based: Dominates the market due to its scalability, remote access capabilities, and integration ease.
- On-Premise: Preferred by a niche group of high-security sectors like Defense or Government, though its share is declining.
- By Organization Size:
- Large Enterprises: Organizations with over 1,000 employees that require enterprise-wide spend governance.
- SMEs: Rapidly adopting "Tail-Spend-as-a-Service" to compete with larger players without heavy infrastructure investment.
- By End-User Industry:
- Manufacturing: High reliance on diverse MRO suppliers makes this the largest user segment.
- Healthcare: Increasing focus on supply chain transparency and regulatory compliance is driving adoption.
- Retail: Needs fast, efficient procurement of indirect goods to maintain operational agility.
Regional Highlights
- North America: This region accounts for the largest market share (approx. 38%) in 2025. The presence of major technology providers like SAP and Coupa, combined with a high corporate emphasis on digital transformation, maintains its market dominance.
- Europe: The second-largest market, characterized by strict regulatory frameworks regarding supplier transparency and environmental sustainability, particularly in Germany, France, and the UK.
- Asia-Pacific: The fastest-growing region with an anticipated CAGR of 14.5%. Massive investments in smart manufacturing in China and the digital India initiative are major propellers.
- Latin America: Showing steady growth as multinational corporations in Brazil and Mexico adopt global procurement standards to optimize local supply chains.
- Middle East and Africa: A developing market where government-led diversification programs (like Saudi Vision 2030) are encouraging the adoption of advanced procurement technologies.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Tail Spend Management Solutions Market.- SAP SE
- Coupa Software Inc.
- GEP Worldwide
- Ivalua Inc.
- Jaggaer
- Corcentric
- Basware
- Proactis Holdings
- Zycus Inc.
- Fairmarkit
- Simfoni
- Xeeva Inc.
- Tradeshift
- Unit4
- BirchStreet Systems
- Mercateo (Unite)
- HICX Solutions
- Determine (a Corcentric company)
- Synertrade
- Scanmarket
Frequently Asked Questions
What is Tail Spend Management and why is it important?
Tail spend management refers to the process of optimizing the "unmanaged" 20% of an organization's total spend that typically involves a high volume of low-value transactions. It is important because managing this spend can lead to cost savings of 5-15%, improved compliance, and better risk management by reducing invisible or "maverick" spending.
How does AI improve Tail Spend Management Solutions?
AI improves these solutions by automating the categorization of millions of disparate spend data points. Machine learning algorithms identify patterns, flag pricing anomalies, and recommend preferred suppliers through "guided buying" portals, significantly reducing the manual labor involved in tactical procurement.
Which industry vertical is the largest adopter of these solutions?
The manufacturing industry is currently the largest adopter. This is due to the sector's complex requirements for Maintenance, Repair, and Operations (MRO) supplies, which involve thousands of small-scale suppliers that contribute to a massive tail spend volume if left unmanaged.
What are the key differences between Software and Managed Services in this market?
Software solutions provide the tools (SaaS platforms) for internal teams to manage their own spend, while Managed Services involve outsourcing the tactical procurement operations to a third-party expert who handles supplier negotiations and transaction management on the company's behalf.
What is the projected growth rate of the Tail Spend Management market through 2034?
The market is projected to grow at a Compound Annual Growth Rate (CAGR) of 12.8% from 2025 to 2034, driven by the increasing need for procurement efficiency, cloud adoption, and the global push for data-driven decision-making in the enterprise space.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
