CNG Powertrain Market
CNG Powertrain Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711893 | Published On : November 20, 2026 |
Format : 


 | Author : Ashraf Shehata
CNG Powertrain Market Size
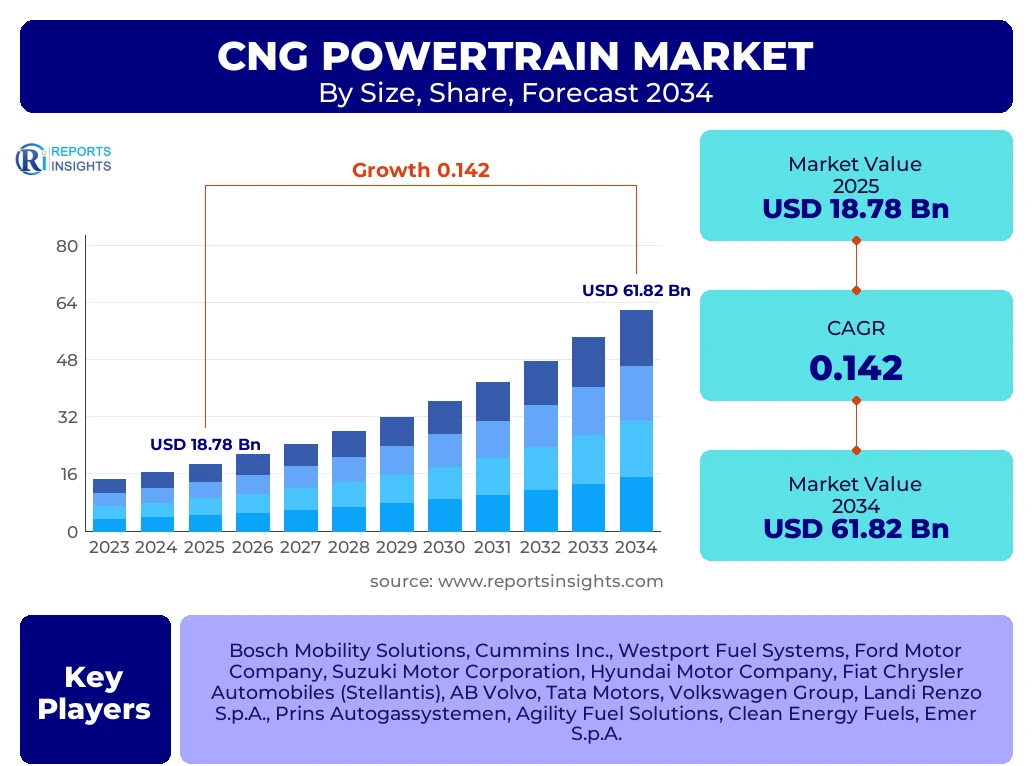
According to Reports Insights Consulting Pvt Ltd, The CNG Powertrain Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 14.2% between 2025 and 2034. The market is estimated at USD 21.45 Billion in 2026 and is projected to reach USD 61.82 Billion by the end of the forecast period in 2034.
The global transition toward sustainable mobility and the urgent need to reduce carbon footprints in the transportation sector have positioned Compressed Natural Gas (CNG) as a pivotal bridge fuel. Unlike traditional internal combustion engines relying solely on petroleum distillates, CNG powertrains offer a significant reduction in nitrogen oxides (NOx) and particulate matter. The market's valuation is driven by the widening price gap between natural gas and crude oil derivatives, making CNG an economically viable alternative for both individual consumers and commercial fleet operators. As municipal governments implement stricter emission zones, the demand for factory-fitted CNG kits and dedicated natural gas engines is experiencing an unprecedented surge.
Technological advancements in fuel injection systems and high-pressure storage tanks have mitigated earlier concerns regarding performance lag and vehicle range. Modern CNG powertrains now feature sequential injection technology that optimizes fuel-air ratios, ensuring that power delivery is comparable to gasoline counterparts. Furthermore, the integration of lightweight Type 4 composite cylinders has improved vehicle payload capacity, a critical factor for the logistics and freight industry. These engineering breakthroughs, coupled with aggressive infrastructure development in emerging economies, provide a robust foundation for the projected market growth through 2034.
Key CNG Powertrain Market Trends & Insights
The CNG powertrain landscape is currently defined by a strategic shift from aftermarket conversions to Original Equipment Manufacturer (OEM) integrated solutions. Stakeholders are increasingly prioritizing factory-fitted systems due to superior safety standards, optimized engine calibration, and comprehensive warranty coverage. In regions like Asia-Pacific, particularly India and China, the expansion of city gas distribution networks is acts as a primary catalyst for market penetration. Competitive benchmarking reveals that players focusing on bi-fuel technologies—capable of switching between gasoline and CNG—are capturing the largest consumer share, as these systems alleviate range anxiety in areas with sparse refueling infrastructure.
- Largest Region: Asia-Pacific currently holds the dominant market share, accounting for over 45% of global revenue, driven by massive infrastructure investments and government subsidies in India and China.
- Fastest Growing Region: Latin America is projected to witness the highest CAGR during the forecast period, fueled by the adoption of CNG in public transit and ride-hailing fleets in Brazil and Argentina.
- Largest Segment by Vehicle Type: Passenger cars remain the largest segment in terms of volume, though the light commercial vehicle (LCV) segment is growing rapidly due to the e-commerce delivery boom.
- Dominant Technology: Bi-fuel powertrain systems lead the market share as they provide a safety net for long-distance travel where CNG stations may be limited.
- Emerging Trend: The development of H-CNG (Hydrogen-enriched CNG) is gaining traction as a method to further reduce emissions without requiring complete engine overhauls.
Key Takeaways CNG Powertrain Market Size & Forecast
The market forecast indicates a steady upward trajectory, supported by the decentralization of energy sources and the volatility of global oil prices. Analysts observe that the commercial sector, specifically short-haul logistics and urban transit, is the most aggressive adopter of CNG technology due to the favorable Total Cost of Ownership (TCO). While electric vehicles (EVs) present long-term competition, the current lack of charging infrastructure and high initial costs for heavy-duty EVs ensure that CNG remains the preferred intermediate solution for at least the next decade.
- Infrastructure Correlation: Market growth is directly proportional to the density of CNG refueling stations; countries with over 2,000 stations show 3x higher adoption rates.
- Leading Country: India is anticipated to be the single largest market for CNG powertrains by 2030, supported by the government Green Mobility initiatives.
- Component Evolution: The shift toward electronic control units (ECU) specifically mapped for gas combustion is enhancing fuel efficiency by up to 15%.
- Cost Efficiency: On average, CNG vehicles offer a 25 to 40 percent reduction in running costs per kilometer compared to diesel engines in the current economic climate.
- Regulatory Impact: The implementation of Euro 6 and BS-VI equivalent standards globally is forcing manufacturers to move away from diesel, directly benefiting the CNG sector.
CNG Powertrain Market Drivers Analysis
The primary growth engine for the CNG Powertrain Market is the substantial operational cost savings realized by end-users. As global energy markets remain volatile, the relative stability of natural gas prices provides a predictable financial environment for logistics companies. Additionally, aggressive government mandates aimed at reducing urban air pollution are acting as a significant push factor for OEM production shifts.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Favorable Total Cost of Ownership (TCO) | +4.5% | Global | 2025 - 2034 |
| Expansion of City Gas Distribution (CGD) | +3.8% | India, China, Thailand | 2025 - 2030 |
| Stringent Tailpipe Emission Regulations | +3.2% | European Union, India | 2025 - 2028 |
| Subsidies for Natural Gas Vehicles (NGVs) | +2.7% | Latin America, Italy | 2026 - 2032 |
CNG Powertrain Market Restraints Analysis
Despite the positive outlook, the market faces significant headwinds from the rapid maturation of the electric vehicle ecosystem. The high cost of specialized high-pressure storage tanks and the weight penalty associated with steel cylinders remain deterrents for performance-oriented segments. Furthermore, the limited availability of high-speed CNG dispensers leads to long queuing times, negatively impacting the user experience.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rapid Adoption of Battery Electric Vehicles | -2.5% | North America, Western Europe | 2028 - 2034 |
| High Initial Procurement Cost | -1.8% | Developing Nations | 2025 - 2030 |
| Limited Refueling Infrastructure in Rural Areas | -2.2% | Africa, Southeast Asia | 2025 - 2034 |
CNG Powertrain Market Opportunities Analysis
The integration of Bio-CNG (biomethane) into existing powertrain systems represents a massive opportunity for achieving carbon neutrality. Since Bio-CNG is chemically identical to fossil-based CNG, it requires no modifications to the powertrain, allowing for a seamless transition to a circular economy. Additionally, the heavy-duty long-haul trucking segment remains largely untapped, offering significant growth potential for high-capacity CNG engines.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adoption of Bio-CNG (Biomethane) | +5.1% | Europe, Brazil | 2026 - 2034 |
| Technological Shift to Type 4 Composite Tanks | +2.9% | Global | 2027 - 2034 |
| Development of Dedicated CNG Engines | +3.5% | North America, APAC | 2025 - 2031 |
CNG Powertrain Market Challenges Impact Analysis
The most pressing challenge is the loss of cargo space in passenger vehicles due to bulky fuel cylinders. Engineering teams are struggling to balance fuel capacity with vehicle aesthetics and utility. Moreover, the lack of standardized global regulations for CNG tank testing and certification creates barriers for cross-border vehicle trade and increases manufacturing complexity for global OEMs.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Weight and Packaging Constraints | -1.5% | Passenger Car Segment | 2025 - 2030 |
| Fluctuating Natural Gas Global Prices | -2.1% | Import-dependent Nations | 2025 - 2034 |
CNG Powertrain Market - Updated Report Scope
This report provides a comprehensive analysis of the global CNG powertrain ecosystem, covering the entire value chain from component manufacturers to vehicle integrators. The scope includes a detailed breakdown of fuel systems, engine modifications, and storage technologies across various vehicle categories. The analysis leverages historical data from 2020 to 2024 to provide a high-fidelity forecast through 2034, considering macroeconomic factors, energy policies, and technological disruptions.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 18.78 Billion |
| Market Forecast in 2034 | USD 61.82 Billion |
| Growth Rate | 14.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Bosch Mobility Solutions, Cummins Inc., Westport Fuel Systems, Ford Motor Company, Suzuki Motor Corporation, Hyundai Motor Company, Fiat Chrysler Automobiles (Stellantis), AB Volvo, Tata Motors, Volkswagen Group, Landi Renzo S.p.A., Prins Autogassystemen, Agility Fuel Solutions, Clean Energy Fuels, Emer S.p.A. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented primarily by fuel configuration and vehicle application. Bi-fuel systems dominate the consumer landscape as they provide the flexibility of gasoline for long-distance travel while utilizing CNG for cost-effective urban commuting. In contrast, the dedicated mono-fuel segment is seeing growth in the public transportation sector, where vehicles operate on fixed routes with dedicated refueling depots. The component segment is witnessing a transition toward digitalized pressure regulators and high-speed injectors that mimic the performance characteristics of high-end gasoline engines.
- By Drive Type:
- Front Wheel Drive (FWD): Dominates the passenger car segment due to fuel efficiency.
- Rear Wheel Drive (RWD): Preferred for light and heavy commercial vehicles.
- All Wheel Drive (AWD): Niche segment for utility vehicles in rugged terrains.
- By Fuel Type:
- Mono-Fuel: Primarily used in transit buses and delivery fleets.
- Bi-Fuel: The most popular choice for retail consumers.
- By Vehicle Type:
- Passenger Cars: Highest volume contributor.
- Light Commercial Vehicles (LCV): Fastest growing due to urban logistics.
- Heavy Commercial Vehicles (HCV): Emerging segment for long-haul transport.
Regional Highlights
- Asia-Pacific: The largest market globally. India’s focus on the Blue Flame revolution and China’s massive natural gas heavy-truck fleet make this region the primary revenue generator.
- Europe: Leading in the adoption of Bio-CNG. Countries like Italy and Germany have established mature refueling networks and are focusing on decarbonizing existing ICE fleets.
- North America: Market growth is concentrated in the refuse truck and transit bus segments, supported by abundant domestic shale gas production.
- Latin America: Argentina and Brazil remain strongholds for CNG powertrains, with high penetration in the taxi and ride-sharing sectors.
- Middle East & Africa: Iran holds one of the world's largest NGV fleets, while Egypt is rapidly converting public transport to CNG to reduce fuel import bills.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the CNG Powertrain Market.- Bosch Mobility Solutions
- Cummins Inc.
- Westport Fuel Systems
- Ford Motor Company
- Suzuki Motor Corporation
- Hyundai Motor Company
- Stellantis (Fiat)
- AB Volvo
- Tata Motors
- Volkswagen Group
- Landi Renzo S.p.A.
- Prins Autogassystemen
- Agility Fuel Solutions
- Clean Energy Fuels
- Emer S.p.A.
- Nikola Corporation (Natural Gas Division)
- Iveco Group
- Renault Group
Frequently Asked Questions
What is the primary advantage of a CNG powertrain over a traditional diesel engine?
The primary advantage is the significant reduction in operational costs, often between 30% to 50%, and lower emissions of Nitrogen Oxides (NOx) and Particulate Matter, which helps in meeting strict urban air quality standards.
How does bi-fuel technology work in modern CNG vehicles?
Bi-fuel systems allow the vehicle to run on both CNG and gasoline. The engine typically starts on gasoline to reach optimal temperature and then automatically switches to CNG. The driver can also manually switch between fuels based on availability and driving conditions.
Is the CNG Powertrain Market threatened by the rise of Electric Vehicles (EVs)?
While EVs are a long-term competitor, CNG powertrains serve as a vital transitional technology, especially in regions where the electrical grid is unstable or where charging infrastructure for heavy-duty commercial vehicles is not yet feasible.
What are Type 4 cylinders and why are they important?
Type 4 cylinders are made of non-metallic liners (usually plastic) reinforced with carbon fiber. They are significantly lighter than traditional steel (Type 1) tanks, which increases the vehicle's fuel efficiency and allows for a higher payload capacity.
Which region is expected to lead the CNG Powertrain Market by 2034?
Asia-Pacific is expected to maintain its leadership through 2034, driven by massive government-led infrastructure projects in India and the widespread adoption of natural gas in China's commercial logistics sector.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
