Chemical Distribution Market
Chemical Distribution Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_703153 | Published On : October 08, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Chemical Distribution Market Size
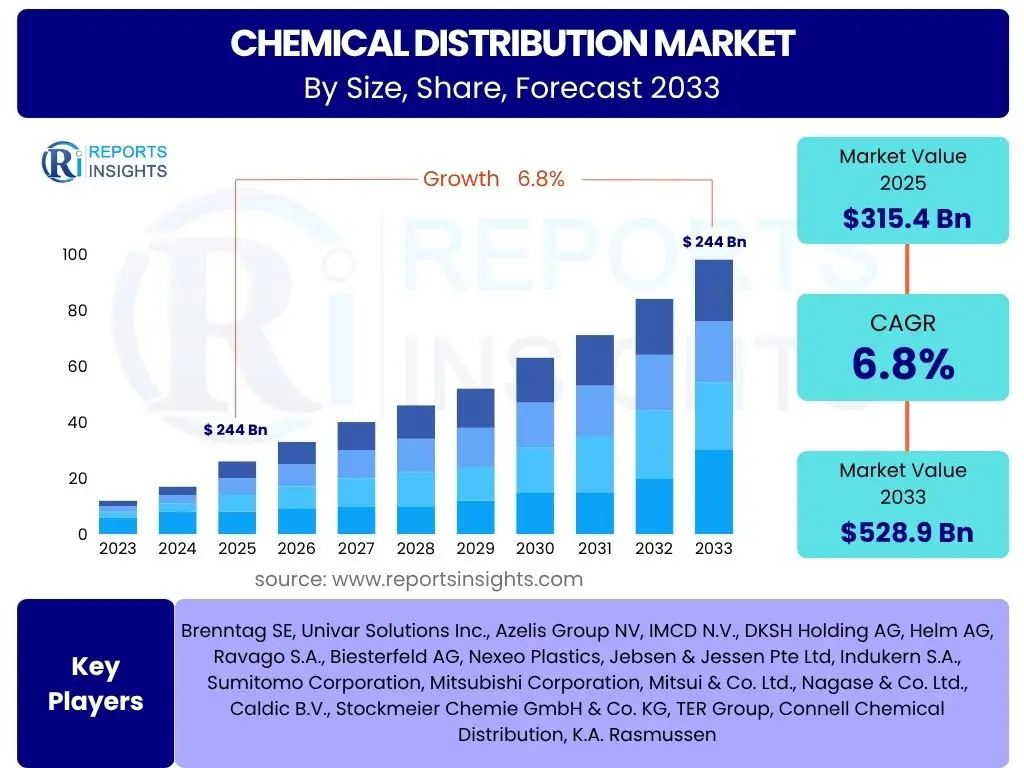
According to Reports Insights Consulting Pvt Ltd, The Chemical Distribution Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.4% between 2025 and 2034. The market is estimated at USD 298.4 Billion in 2026 and is projected to reach USD 454.2 Billion by the end of the forecast period in 2034.
Key Chemical Distribution Market Trends & Insights
The global chemical distribution market is currently undergoing a structural transformation driven by the integration of digital technologies and a heightened focus on sustainability. Manufacturers are increasingly outsourcing their logistics and distribution operations to third-party specialists to mitigate operational complexities and focus on core R&D activities. Regional insights indicate that the Asia-Pacific region continues to dominate the landscape due to rapid industrialization and a burgeoning manufacturing sector in China and India. Competitive benchmarking reveals that top-tier distributors are expanding their portfolios to include specialty chemicals, which offer higher margins compared to bulk commodities. Furthermore, the industry is witnessing a trend toward consolidation, with large players acquiring local distributors to enhance their geographic footprint and technical service capabilities.
- Largest Region: Asia-Pacific currently holds the largest market share, accounting for over 45% of global revenue, driven by massive demand from the construction and automotive sectors.
- Fastest-Growing Region: Asia-Pacific is also anticipated to be the fastest-growing region, with emerging economies expanding their chemical consumption at a rate exceeding global averages.
- Largest Segment by Share: Commodity chemicals remain the largest segment in terms of volume, though specialty chemicals are gaining significant ground in terms of value-added services.
- Digitalization Trend: Adoption of e-commerce platforms and blockchain for supply chain transparency is becoming a critical differentiator for leading distributors.
- Sustainability Focus: Increasing demand for green chemistry and bio-based solvents is reshaping product distribution portfolios across North America and Europe.
Key Takeaways Chemical Distribution Market Size & Forecast
The chemical distribution market is poised for steady growth as industrial end-users demand more sophisticated supply chain solutions and technical support. The shift from a simple logistics model to a value-added service model is a primary takeaway for stakeholders. This evolution allows distributors to act as strategic partners rather than mere intermediaries. Forecasts indicate that the market will see a significant uptick in the specialty chemicals segment, particularly in high-growth industries like pharmaceuticals and electronics. Investors and market participants are focusing on high-growth corridors in Southeast Asia and Latin America to capitalize on favorable regulatory shifts and expanding middle-class populations that drive consumer-end chemical demand.
- Leading Country: China stands as the global leader in both production and consumption of chemicals, making it the most critical hub for international distributors.
- Growth Catalysts: Rapid urbanization and infrastructure development in emerging economies are primary drivers for bulk chemical distribution.
- Strategic M&A: Mergers and acquisitions are expected to remain a dominant strategy for market leaders seeking to enter niche specialty markets.
- Regulatory Influence: Stringent environmental regulations in the European Union (REACH) are compelling distributors to adopt more rigorous safety and compliance standards.
- Resilient End-Uses: The pharmaceutical and personal care segments are identified as the most resilient end-use industries, maintaining steady demand even during economic downturns.
Chemical Distribution Market Drivers Analysis
The expansion of the chemical distribution market is fundamentally supported by the increasing complexity of global supply chains and the rising demand for specialty chemicals across various high-tech industries. As chemical manufacturers seek to reduce overhead costs, they are transferring the risks associated with logistics, storage, and regulatory compliance to professional distributors. This trend is complemented by the rapid industrialization of developing nations, where the need for industrial cleaners, polymers, and pigments is surging. Additionally, the rise of custom blending and technical formulation services provided by distributors is creating new revenue streams and deepening the relationship between distributors and end-users.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Increased Outsourcing by Manufacturers | +1.8% | Global / North America | 2025 - 2034 |
| Industrial Growth in Emerging Markets | +2.1% | Asia-Pacific / India, China | 2025 - 2034 |
| Demand for Specialty & Fine Chemicals | +1.2% | Europe / Germany, France | 2026 - 2034 |
| Expansion of Value-Added Services | +0.9% | Global / Developed Markets | 2025 - 2030 |
Chemical Distribution Market Restraints Analysis
Despite robust growth prospects, the market faces significant hurdles, primarily centered around volatile raw material prices and increasingly stringent environmental and safety regulations. The high cost of maintaining specialized storage facilities for hazardous materials and the complexities of cross-border chemical trade are substantial barriers for smaller players. Furthermore, the volatility of crude oil prices directly impacts the cost structure of petrochemical derivatives, leading to margin compression for distributors who cannot easily pass on costs to the end-consumer. Geopolitical tensions also pose a threat to established trade routes, leading to increased freight costs and supply delays.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Environmental Regulations | -1.1% | European Union / REACH | 2025 - 2034 |
| Volatile Logistics & Freight Costs | -0.8% | Global / Maritime Trade | 2025 - 2028 |
| Raw Material Price Fluctuation | -0.6% | Global / Petrochemicals | Continuous |
| Geopolitical Instability | -0.5% | Middle East / Eastern Europe | 2025 - 2030 |
Chemical Distribution Market Opportunities Analysis
The shift toward circular economies and green chemistry presents a transformative opportunity for the chemical distribution sector. Distributors that can provide eco-friendly alternatives, such as bio-based solvents and recyclable polymers, are expected to capture a larger share of the market in sustainability-conscious regions like Europe and North America. Additionally, the integration of Advanced Analytics and Artificial Intelligence into supply chain management allows for better demand forecasting and inventory optimization, significantly reducing waste and operational costs. The rise of e-commerce platforms specifically designed for B2B chemical sales is also opening new doors for reaching small and medium-sized enterprises (SMEs) that were previously underserved.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Growth in Green Chemistry | +1.5% | North America & Europe | 2026 - 2034 |
| Digital Transformation & E-commerce | +1.3% | Global / Tech-driven Hubs | 2025 - 2032 |
| Emerging Markets Infrastructure | +1.1% | Southeast Asia / Vietnam, Indonesia | 2027 - 2034 |
| Strategic M&A Activity | +0.7% | Global / Fragmented Markets | 2025 - 2034 |
Chemical Distribution Market Challenges Impact Analysis
One of the primary challenges facing the industry is the shortage of skilled labor capable of handling specialized chemical products and navigating complex regulatory environments. As products become more specialized, the level of technical expertise required for sales and support increases, putting pressure on HR departments. Additionally, the decarbonization of logistics fleets remains a capital-intensive challenge for distributors aiming to meet net-zero targets. Cybersecurity also emerges as a critical concern as companies digitize their order management and customer data systems, making them targets for sophisticated cyber-attacks. Finally, the slow pace of infrastructure development in certain emerging markets can hinder the efficient distribution of temperature-sensitive or hazardous chemicals.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Decarbonization of Supply Chains | -0.9% | Global / Logistics Sector | 2025 - 2034 |
| Technical Labor Shortages | -0.5% | North America / Europe | 2025 - 2030 |
| Cybersecurity Risks | -0.4% | Global / Digital Platforms | Continuous |
| Infrastructure Bottlenecks | -0.6% | Africa / Parts of Latin America | 2025 - 2034 |
Chemical Distribution Market - Updated Report Scope
This report provides a comprehensive analysis of the global chemical distribution market, covering various product types, end-use industries, and geographic regions. The scope includes a detailed evaluation of both commodity and specialty chemicals, with a specific focus on the shifting dynamics of supply chain management and value-added services. The research methodology combines primary data from industry experts with secondary data from reputable financial and regulatory databases to ensure the highest level of accuracy and logical consistency. The forecast period extends from 2026 to 2034, providing stakeholders with a long-term strategic perspective on market trends, competitive intensity, and investment opportunities.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 283.1 Billion |
| Market Forecast in 2034 | USD 454.2 Billion |
| Growth Rate | 5.4% CAGR |
| Number of Pages | 245 Pages |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Brenntag SE, Univar Solutions Inc., Helm AG, Tricon Energy Inc., IMCD N.V., Azelis Group NV, Biesterfeld AG, Omya AG, DKSH Holding Ltd., Mitsui & Co., Ltd., Itochu Corporation, Sinochem Group, REDA Chemicals, Stockmeier Group, Quimidroga, GTM Chemicals, Manuchar, Solvadis, Jebsen & Jessen, Caldic B.V. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The chemical distribution market is intricately segmented to reflect the diverse range of products and the specific needs of various end-use industries. Commodity chemicals dominate the volume of the market, driven by bulk industrial applications in plastics, rubbers, and basic manufacturing. However, the specialty chemicals segment is the primary engine for value growth, characterized by high-performance products that require specialized handling and technical sales support. End-use segmentation shows that the construction and automotive sectors remain major consumers, while the pharmaceutical and food and beverage sectors are growing rapidly due to stricter safety standards and the demand for high-purity ingredients. This detailed segmentation allows stakeholders to identify niche opportunities and tailor their strategies to specific market requirements.
- By Product Type:
- Commodity Chemicals: Includes large-volume chemicals like plastics, basic inorganics, and synthetic fibers.
- Specialty Chemicals: High-value chemicals such as catalysts, enzymes, specialty pigments, and electronic grade chemicals.
- By Distribution Channel:
- Direct Sales: Direct interaction between manufacturers and large-scale end-users.
- Third-Party Distribution: Use of specialized distributors to reach fragmented small and medium-sized markets.
- By End-Use Industry:
- Construction: Use of resins, coatings, and adhesives in infrastructure.
- Agriculture: Distribution of fertilizers, pesticides, and soil conditioners.
- Automotive: Chemicals for lightweight plastics, paints, and lubricants.
- Life Sciences: High-purity chemicals for pharmaceuticals and biotechnology.
- Consumer Goods: Ingredients for personal care, detergents, and household cleaners.
Regional Highlights
The Asia-Pacific region stands as the titan of the chemical distribution market, fueled by the industrial might of China, India, and Southeast Asian nations. The region benefits from a massive manufacturing base and a growing middle class that drives consumption across all end-use sectors. In North America, the market is highly mature and focused on efficiency and regulatory compliance, with the United States being a significant player due to its robust shale gas industry. Europe follows a similar trend but is distinguished by its strict environmental policies, such as the Green Deal, which is forcing a pivot toward sustainable and bio-based chemical distribution. Latin America and the Middle East & Africa regions are emerging as significant hubs for chemical trade, supported by increasing investments in local manufacturing and the development of major logistics corridors.
- Asia-Pacific (APAC): The largest and fastest-growing region, dominated by China. It accounts for the highest demand for commodity chemicals used in manufacturing.
- North America: A highly consolidated market with a focus on specialty chemicals for the pharmaceutical and aerospace sectors.
- Europe: Leading the world in sustainable distribution practices and high-compliance logistics, with Germany being the regional powerhouse.
- Latin America: Growing demand from the agricultural and mining sectors, particularly in Brazil and Chile.
- Middle East & Africa (MEA): Increasing its role in the global supply chain as an export hub for petrochemicals, while domestic industrialization drives local distribution growth.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Chemical Distribution Market.- Brenntag SE
- Univar Solutions Inc.
- Helm AG
- Tricon Energy Inc.
- IMCD N.V.
- Azelis Group NV
- Biesterfeld AG
- Omya AG
- DKSH Holding Ltd.
- Mitsui & Co., Ltd.
- Itochu Corporation
- Sinochem Group
- REDA Chemicals
- Stockmeier Group
- Quimidroga
- GTM Chemicals
- Manuchar
- Solvadis
- Jebsen & Jessen
- Caldic B.V.
Frequently Asked Questions
What is the current size of the global chemical distribution market?
As of 2025, the market is valued at approximately USD 283.1 Billion. It is expected to grow steadily, reaching USD 454.2 Billion by 2034, driven by industrial expansion and the outsourcing of logistics by major chemical manufacturers.
Which region is expected to lead the market growth during the forecast period?
The Asia-Pacific (APAC) region is projected to lead the market in both size and growth rate. Rapid industrialization in countries like India and China, along with expanding manufacturing sectors, makes it the primary driver for global chemical demand.
What are the key differences between commodity and specialty chemical distribution?
Commodity chemical distribution focuses on high-volume, low-margin bulk chemicals where logistics and price efficiency are paramount. Specialty chemical distribution involves lower volumes but higher margins, requiring significant technical expertise, custom blending, and value-added services.
How is digitalization impacting the chemical distribution industry?
Digitalization is streamlining supply chains through AI-driven demand forecasting, blockchain for better transparency, and the rise of e-commerce platforms. These technologies help distributors reduce operational costs and provide a better customer experience for small and medium-sized enterprises.
What role does sustainability play in the future of chemical distribution?
Sustainability is becoming a core business strategy. Increasing regulations and consumer demand for green products are pushing distributors to expand their portfolios with bio-based chemicals and adopt carbon-neutral logistics practices to remain competitive, especially in Europe and North America.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
