Calcined Shale Market
Calcined Shale Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711864 | Published On : November 19, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Calcined Shale Market Size
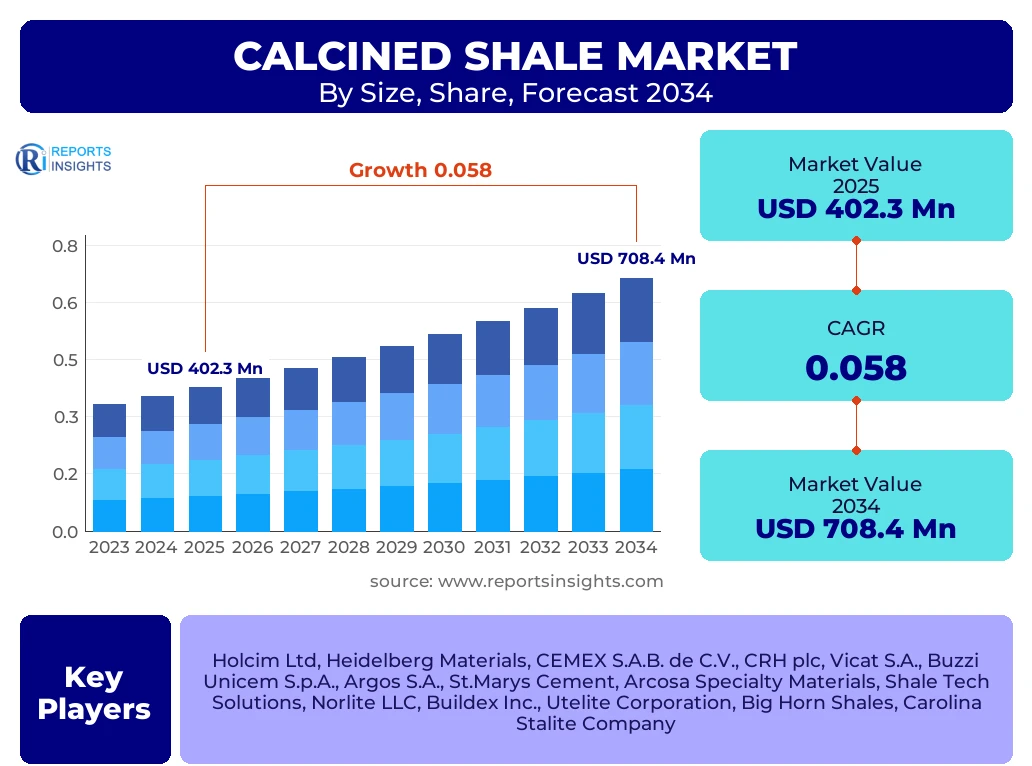
According to Reports Insights Consulting Pvt Ltd, The Calcined Shale Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.8% between 2025 and 2034. The market is estimated at USD 425.6 Million in 2026 and is projected to reach USD 708.4 Million by the end of the forecast period in 2034.
Key Calcined Shale Market Trends & Insights
The global construction landscape is undergoing a fundamental transformation as stakeholders pivot toward sustainable, high-performance materials. Calcined shale, a manufactured pozzolan produced by heating oil shale or argillaceous materials to high temperatures, is emerging as a critical alternative to traditional supplementary cementitious materials (SCMs). As the availability of high-quality fly ash fluctuates due to the global transition away from coal-fired power plants, calcined shale provides a reliable, consistent, and chemically reactive substitute. The market is increasingly influenced by the development of LC3 (Limestone Calcined Clay Cement) technologies, which utilize calcined materials to reduce the clinker factor in cement production, thereby significantly lowering carbon emissions.
Technological advancements in rotary kiln efficiency and the integration of carbon capture technologies at calcination sites represent a significant trend in the industrial processing of shale. Manufacturers are investing in modular calcination units that allow for localized production, reducing transportation costs and the overall carbon footprint of the supply chain. Furthermore, the market is seeing a surge in research focused on the specialized use of calcined shale in high-strength concrete and refractory applications, where its thermal stability and chemical resistance offer superior performance over conventional aggregates. Digitalization in the form of real-time mineralogical analysis during the heating process is also becoming a standard for top-tier producers to ensure the quality of the amorphous silica and alumina content.
- Asia Pacific remains the largest and fastest-growing region, driven by massive infrastructure projects in China and India.
- The Cement & Concrete segment holds the largest market share, accounting for over 65% of total consumption.
- The Fine Grade segment is witnessing the fastest growth due to its high reactivity in blended cement formulations.
- Western Europe is leading in the adoption of calcined shale for green building certifications and LEED-compliant projects.
- Rising demand for Oil and Gas Well Cementing in the Middle East is providing a secondary growth vertical for high-grade calcined shale.
Key Takeaways Calcined Shale Market Size & Forecast
The calcined shale market is positioned for steady expansion as the global cement industry faces tightening environmental regulations. Market forecasts indicate that the depletion of natural pozzolans in certain geographies will force a shift toward manufactured alternatives, with calcined shale being the primary beneficiary. The forecast period 2026-2034 will likely see a CAGR of nearly 6%, bolstered by the replacement of ordinary Portland cement (OPC) with ternary blends. Analysts anticipate that the integration of calcined shale in the production of precast concrete elements will be a major revenue driver, as it accelerates early-strength development and improves the surface finish of architectural components.
Strategic partnerships between shale mining companies and global cement giants are expected to consolidate the market. These collaborations focus on securing long-term raw material supplies and establishing dedicated calcination facilities near major urban construction hubs. Furthermore, the rise of "Green Concrete" initiatives globally is expected to create a premium pricing tier for certified low-carbon calcined shale products. Investors and stakeholders should focus on regions where legislative mandates for lower clinker-to-cement ratios are being implemented, as these areas will exhibit the highest demand density for pozzolanic materials.
- China and India will account for nearly 45% of the global volume demand by 2034.
- Sustainability mandates like the EU Green Deal are making calcined shale a non-negotiable component in European construction.
- The Refractory Industry in North America is increasingly utilizing calcined shale for specialized heat-resistant linings.
- Advancements in Vertical Roller Mill (VRM) technology are allowing for more energy-efficient grinding of calcined shale.
- Market resilience is supported by the diversified application base, spanning from road construction to specialized chemical-resistant flooring.
Calcined Shale Market Drivers Analysis
The primary driver for the calcined shale market is the urgent global requirement for low-carbon construction materials. As the cement industry contributes approximately 8% of global CO2 emissions, the shift toward supplementary cementitious materials is no longer optional. Calcined shale offers a high degree of pozzolanic reactivity, which allows for the replacement of up to 30% of cement clinker without compromising structural integrity. Additionally, the diminishing supply of traditional fly ash is creating a supply vacuum that calcined shale is ideally suited to fill.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shift toward Low-Carbon Cement (LC3) | +1.8% | Global (Strong in Europe/APAC) | 2025 - 2034 |
| Fly Ash Supply Deficit | +1.5% | North America and India | 2026 - 2030 |
| Infrastructure Expansion in Emerging Economies | +1.2% | Southeast Asia and Africa | 2025 - 2034 |
| Demand for High-Durability Marine Concrete | +0.7% | Coastal Regions (China, GCC) | 2027 - 2034 |
Calcined Shale Market Restraints Analysis
Despite strong growth drivers, the market faces significant restraints related to the energy intensity of the calcination process. The high temperatures required (700°C to 900°C) necessitate significant energy input, which can offset the carbon savings if not powered by renewable sources or efficient kilns. Furthermore, the geographical concentration of suitable shale deposits can lead to high logistical costs for regions lacking local resources, making it less competitive against local natural pozzolans or imported slag.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Thermal Energy Requirements | -0.9% | Europe and North America | 2025 - 2034 |
| Stringent Mining and Environmental Regulations | -0.6% | European Union | 2025 - 2028 |
| Fluctuating Raw Material Quality | -0.4% | Latin America and Africa | 2026 - 2034 |
Calcined Shale Market Opportunities Analysis
Significant opportunities lie in the integration of calcined shale into 3D concrete printing technologies, where the material's ability to control rheology and set times is highly valued. Additionally, the development of "Activated Calcined Shale" through chemical modifiers can further enhance its reactivity, opening markets in high-performance aerospace and military infrastructure. The rehabilitation of aging infrastructure in developed nations also provides a massive opportunity for calcined shale-based mortars and grouts.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| 3D Concrete Printing Integration | +1.1% | United States and UAE | 2028 - 2034 |
| Chemical Activation for Ultra-High Performance Concrete | +0.8% | Germany and Japan | 2027 - 2034 |
| Expansion in Soil Stabilization Applications | +0.6% | India and Brazil | 2026 - 2034 |
Calcined Shale Market Challenges Impact Analysis
A major challenge is the lack of standardized global codes for the use of calcined shale in structural concrete. While many regions have adopted ASTM or EN standards, inconsistencies remain in emerging markets, which slows down large-scale adoption. Additionally, competition from other SCMs such as ground granulated blast furnace slag (GGBFS) and silica fume remains intense, especially in regions where these materials are readily available as industrial byproducts.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Lack of Harmonized International Standards | -0.7% | Developing Nations | 2025 - 2030 |
| Competition from Alternative SCMs | -0.5% | Global | 2025 - 2034 |
| Technical Complexity in Mix Designs | -0.3% | General Contractors | 2026 - 2029 |
Calcined Shale Market - Updated Report Scope
The report provides a deep-dive analysis into the global calcined shale ecosystem, covering the entire value chain from raw shale extraction to final application in construction, refractories, and industrial processes. It evaluates the impact of macroeconomic factors, energy prices, and environmental policies on market dynamics. The scope includes a detailed assessment of production technologies, specifically comparing rotary kilns versus flash calcination methods, and their respective impacts on product quality and energy efficiency.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 402.3 Million |
| Market Forecast in 2034 | USD 708.4 Million |
| Growth Rate | 5.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Holcim Ltd, Heidelberg Materials, CEMEX S.A.B. de C.V., CRH plc, Vicat S.A., Buzzi Unicem S.p.A., Argos S.A., St.Marys Cement, Arcosa Specialty Materials, Shale Tech Solutions, Norlite LLC, Buildex Inc., Utelite Corporation, Big Horn Shales, Carolina Stalite Company |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The calcined shale market is segmented based on the alumina content, particle size (grade), and the primary end-use application. Each segment displays unique growth trajectories based on industrial requirements. The Fine Grade segment is currently the most dynamic due to its high surface area and reactivity in chemical processes. High Alumina calcined shale is the preferred choice for the refractory industry, where thermal stability is paramount. The Cement Industry remains the dominant end-user, but rapid growth is also noted in specialized applications like oil well cementing and wastewater treatment filtration media.
- By Type:
- Low Alumina
- High Alumina
- By Grade:
- Fine Grade (High Reactivity)
- Coarse Grade (Aggregate Use)
- By Application:
- Cement Industry: Clinker replacement and blended cements.
- Concrete Admixtures: Precast, ready-mix, and high-performance concrete.
- Refractories: Lining for kilns and furnaces.
- Soil Stabilization: Road construction and heavy engineering.
- Oil & Gas: Lightweight cement slurries for well casing.
Regional Highlights
Asia Pacific is the dominant force in the global calcined shale market, accounting for nearly 40% of the total market share. This dominance is driven by the rapid pace of urbanization in China, India, and Vietnam. China, in particular, has integrated calcined materials into its national infrastructure standards to meet aggressive carbon neutrality targets. India's burgeoning construction sector is increasingly looking toward calcined shale as a viable alternative to fly ash, which is seeing supply volatility due to the decommissioning of older coal plants.
In Europe, the market is characterized by high-value, specialized applications. The region is a leader in "Green Cement" innovation, with numerous pilot projects utilizing calcined shale in ternary blends. Strict carbon taxes and the Carbon Border Adjustment Mechanism (CBAM) are incentivizing cement producers to reduce their clinker-to-cement ratio. North America follows closely, with the United States showing strong demand in the bridge and highway construction sector, where the high durability and chemical resistance of calcined shale-modified concrete provide long-term maintenance savings.
- Largest Region: Asia Pacific (Led by China and India).
- Fastest Growing Region: Southeast Asia (CAGR of 6.4%).
- Mature Market: Western Europe (Focus on sustainability and high-grade specialty products).
- Emerging Hub: Middle East (Driven by mega-city projects in Saudi Arabia and Qatar).

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Calcined Shale Market.- Holcim Ltd
- Heidelberg Materials
- CEMEX S.A.B. de C.V.
- CRH plc
- Vicat S.A.
- Buzzi Unicem S.p.A.
- Argos S.A.
- St. Marys Cement (Votorantim Cimentos)
- Arcosa Specialty Materials
- Shale Tech Solutions
- Norlite LLC
- Buildex Inc.
- Utelite Corporation
- Big Horn Shales
- Carolina Stalite Company
- Hydraulit
- Trinity Lightweight
- Siam Cement Group (SCG)
- UltraTech Cement Ltd.
- Shree Cement
Frequently Asked Questions
What is the main advantage of using calcined shale in cement?
Calcined shale acts as a powerful pozzolan, reacting with calcium hydroxide produced during cement hydration to form additional cementitious compounds. This improves the strength, durability, and chemical resistance of concrete while reducing its carbon footprint by allowing for lower clinker content.
How does calcined shale compare to fly ash?
While both are supplementary cementitious materials, calcined shale is a manufactured product with more consistent chemical properties compared to fly ash, which is a byproduct of coal combustion. As coal-fired plants close, calcined shale provides a more reliable and sustainable long-term supply for the construction industry.
Which region is expected to lead the Calcined Shale market growth?
The Asia Pacific region, specifically China and India, is expected to lead the market growth. This is due to massive investments in infrastructure, the need for sustainable building materials in rapidly growing cities, and government mandates to reduce industrial CO2 emissions.
What are the primary applications of high-alumina calcined shale?
High-alumina calcined shale is primarily used in the refractories industry. Its ability to withstand extreme temperatures without losing structural integrity makes it ideal for lining industrial furnaces, kilns, and reactors used in steel, glass, and chemical manufacturing.
Does calcined shale help in achieving LEED certification?
Yes, because calcined shale significantly reduces the embodied carbon of concrete by replacing energy-intensive Portland cement clinker, its use can contribute to LEED credits in categories related to Materials and Resources as well as Innovation in Design.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
