Buy Now Pay Later Market
Buy Now Pay Later Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711427 | Published On : November 01, 2026 |
Format : 


 | Author : Ram Krishnan
Buy Now Pay Later Market Size
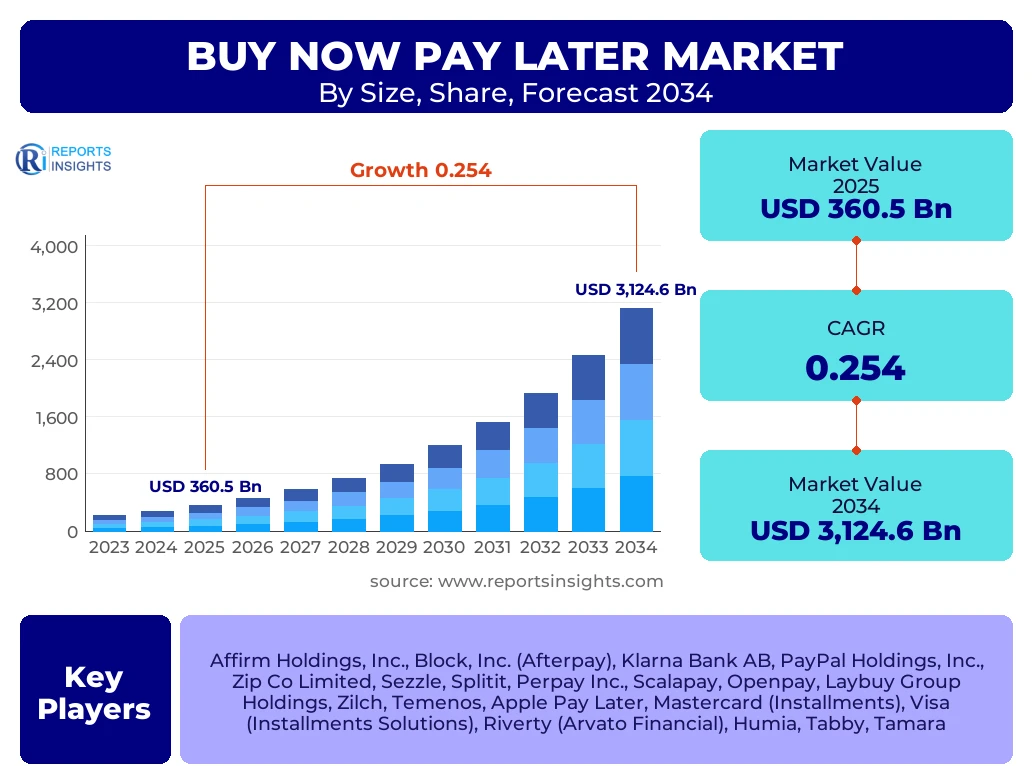
According to Reports Insights Consulting Pvt Ltd, The Buy Now Pay Later Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 25.4% between 2025 and 2034. The market is estimated at USD 452.1 Billion in 2026 and is projected to reach USD 3,124.6 Billion by the end of the forecast period in 2034.
Key Buy Now Pay Later Market Trends & Insights
The global Buy Now Pay Later (BNPL) landscape is undergoing a significant transformation as consumer credit preferences shift from traditional revolving interest models toward transparent, installment-based financing. Market maturity varies significantly by geography; while Australia and parts of Western Europe have reached high penetration levels, the Asia-Pacific region and Latin America represent the next frontier for hyper-growth. Key inquiries from stakeholders frequently center on the sustainability of zero-interest models and the impact of rising interest rates on BNPL provider margins. Analysis indicates that the market is moving toward a Super-App ecosystem where credit, commerce, and personal finance management converge into a single interface. Furthermore, the integration of BNPL into the Business-to-Business (B2B) sector is emerging as a critical trend, providing small and medium-sized enterprises (SMEs) with much-needed working capital flexibility without the friction of traditional bank loans.
- North America remains the largest regional market by value, driven by high e-commerce spending and the presence of major industry incumbents.
- The Asia-Pacific region is the fastest-growing market, fueled by increasing smartphone penetration and the rapid digitization of retail in India and Southeast Asia.
- Millennials and Generation Z represent the largest consumer segments, accounting for over 60% of total BNPL transaction volume globally.
- Retail and Fashion continue to be the dominant industry segments, although Travel and Healthcare are witnessing the most rapid adoption rates in recent years.
- Mobile applications are the preferred channel for BNPL transactions, surpassing desktop-based checkouts by a significant margin.
Key Takeaways Buy Now Pay Later Market Size & Forecast
The forecast for the Buy Now Pay Later market suggests a robust decade of expansion, characterized by a transition from niche alternative payment to a standard checkout requirement. Users frequently inquire about the long-term viability of BNPL in a higher interest rate environment and the impending regulatory changes. The insights suggest that while regulatory oversight will increase—treating BNPL more like traditional credit—this will actually benefit the market by weeding out unsustainable players and building consumer trust. The growth is not merely organic but is being propelled by strategic partnerships between BNPL providers and traditional financial institutions, creating a hybrid model that combines fintech agility with the security of legacy banking infrastructure.
- The global market value is expected to exceed the USD 3 trillion mark by 2034, reflecting a fundamental shift in global consumer spending habits.
- The United States, Germany, and Australia are the leading countries in terms of market maturity and credit volume.
- B2B BNPL is anticipated to grow at a higher CAGR than B2C during the forecast period as supply chain finance modernizes.
- AI-driven credit scoring is replacing traditional credit bureau checks for many BNPL providers, allowing for faster approvals and lower default rates.
- Integration with physical Point-of-Sale (POS) systems through NFC and virtual cards is closing the gap between online and offline BNPL adoption.
Buy Now Pay Later Market Drivers Analysis
The primary catalysts for the BNPL market include the exponential growth of global e-commerce and a growing consumer aversion to traditional credit card debt, particularly among younger demographics. Additionally, the low-friction nature of BNPL applications compared to traditional personal loans provides a competitive edge in capturing immediate consumer intent at the point of sale.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Surge in Global E-commerce Penetration | +6.5% | Global / Southeast Asia | 2025 - 2034 |
| Gen Z and Millennial Preference for Debt-Free Credit | +5.2% | North America / Europe | 2025 - 2030 |
| AI-Based Instant Credit Approval Systems | +4.8% | Global | 2026 - 2034 |
| Merchant Demand for Higher Conversion Rates | +3.9% | China / USA | 2025 - 2034 |
Buy Now Pay Later Market Restraints Analysis
Market growth is tempered by increasing regulatory scrutiny aimed at preventing consumer over-indebtedness and ensuring fair lending practices. Additionally, the tightening of monetary policy globally has increased the cost of capital for BNPL providers, putting pressure on the profitability of interest-free business models.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Regulatory and Compliance Frameworks | -3.2% | UK / Australia / EU | 2025 - 2028 |
| Rising Interest Rates Affecting Funding Costs | -2.8% | USA / Europe | 2025 - 2027 |
| High Risk of Consumer Default in Economic Downturns | -1.5% | Global | 2025 - 2034 |
Buy Now Pay Later Market Opportunities Analysis
There are significant opportunities in the expansion of BNPL into high-ticket sectors such as healthcare, education, and home improvement. Furthermore, the integration of BNPL into the B2B supply chain offers a massive untapped market for trade finance optimization and cash flow management for small businesses.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into B2B Supply Chain Financing | +5.5% | Global | 2026 - 2034 |
| Integration with Healthcare and Elective Medical Services | +3.4% | USA / Brazil | 2025 - 2034 |
| Adoption in Emerging Markets with Low Credit Card Density | +4.1% | India / Nigeria / Indonesia | 2025 - 2034 |
Buy Now Pay Later Market Challenges Impact Analysis
The primary challenge remains the threat of cyber-attacks and identity theft, which can erode consumer trust in digital payment platforms. Moreover, intense competition from traditional banks launching their own BNPL-style products is forcing fintech players to drastically reduce merchant fees, threatening their long-term revenue streams.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Cybersecurity Threats and Synthetic Identity Fraud | -1.2% | Global | 2025 - 2034 |
| Market Saturation and Margin Compression | -2.1% | Western Europe / Australia | 2027 - 2034 |
| Data Privacy and Consumer Information Regulations | -0.8% | European Union (GDPR) | 2025 - 2034 |
Buy Now Pay Later Market - Updated Report Scope
The updated report provides a 360-degree view of the BNPL ecosystem, encompassing technological shifts, regulatory updates, and evolving consumer behavior across six major geographic regions. This edition focuses specifically on the convergence of fintech and traditional banking, analyzing how current macroeconomic pressures are reshaping the competitive landscape and driving consolidation within the industry.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 360.5 Billion |
| Market Forecast in 2034 | USD 3,124.6 Billion |
| Growth Rate | 25.4% CAGR |
| Number of Pages | 265 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Affirm Holdings, Inc., Block, Inc. (Afterpay), Klarna Bank AB, PayPal Holdings, Inc., Zip Co Limited, Sezzle, Splitit, Perpay Inc., Scalapay, Openpay, Laybuy Group Holdings, Zilch, Temenos, Apple Pay Later, Mastercard (Installments), Visa (Installments Solutions), Riverty (Arvato Financial), Humia, Tabby, Tamara |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The BNPL market is intricately segmented to reflect the diverse applications and consumer behaviors driving its expansion. Channel-based segmentation highlights the dominance of online platforms, though physical POS integration is the fastest-growing sub-segment as retailers look to bridge the gap between digital and brick-and-mortar experiences. End-use segmentation reveals that while fashion and electronics remain the bedrock of BNPL volume, essential services like healthcare and educational fees are gaining traction as consumers seek manageable ways to handle high-cost obligations.
- By Channel: The online segment dominates due to the seamless integration of BNPL APIs into e-commerce checkout flows, while POS (Point of Sale) is expanding via virtual cards and QR codes.
- By Category: Split-pay (4-installments) is the most popular model globally for small to mid-ticket items, whereas long-term interest-bearing installments are gaining ground for high-value purchases like furniture and travel.
- By End-use: Retail remains the largest segment; however, the healthcare sector is showing a high CAGR as patients use BNPL for elective procedures not covered by traditional insurance.
- By Demographics: Millennials currently hold the highest market share, but Gen Z is the fastest-growing demographic, increasingly viewing BNPL as a financial budgeting tool rather than a debt instrument.
- By Business Model: The B2C model is mature, whereas B2B is in the early stages of adoption, projected to revolutionize trade credit and corporate procurement.
Regional Highlights
The regional distribution of the BNPL market reveals a landscape of varying maturity levels and regulatory environments. North America and Europe currently account for the majority of market value, supported by high per-capita spending and a robust digital infrastructure. In contrast, the Asia-Pacific region is characterized by high-volume, low-value transactions, where BNPL serves as a critical financial inclusion tool for populations with limited access to traditional banking services.
- North America: The largest market by revenue, driven by the aggressive expansion of Affirm and PayPal, and a highly competitive retail environment in the United States and Canada.
- Europe: A highly mature market with Germany and the UK leading in adoption. Regulatory frameworks here are the most advanced, setting a global standard for consumer protection in the BNPL space.
- Asia-Pacific: The fastest-growing region, with China, India, and Australia being the primary engines of growth. In India, BNPL is bypassing traditional credit cards as the first form of credit for millions of young professionals.
- Latin America: Showing significant promise, particularly in Brazil and Mexico, as fintech companies leverage BNPL to address the needs of the unbanked and underbanked populations.
- Middle East & Africa: Rapidly growing, with players like Tabby and Tamara capitalizing on the surge in e-commerce and a young, tech-savvy population in the GCC countries.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Buy Now Pay Later Market.
- Affirm Holdings, Inc.
- Block, Inc. (Afterpay)
- Klarna Bank AB
- PayPal Holdings, Inc.
- Zip Co Limited
- Sezzle
- Splitit
- Perpay Inc.
- Scalapay
- Openpay
- Laybuy Group Holdings
- Zilch
- Temenos
- Apple Pay Later
- Mastercard (Installments)
- Visa (Installments Solutions)
- Riverty (Arvato Financial)
- Humia
- Tabby
- Tamara
Frequently Asked Questions
What is the current and projected size of the Buy Now Pay Later market?
The global Buy Now Pay Later market is valued at approximately USD 360.5 billion in 2025 and is projected to reach USD 3,124.6 billion by 2034, growing at a CAGR of 25.4%. This growth is driven by the digital transformation of retail and shifting consumer preferences away from traditional credit cards.
Which region is expected to witness the fastest growth in the BNPL sector?
The Asia-Pacific region is anticipated to be the fastest-growing market between 2025 and 2034. Factors such as increasing smartphone penetration, a massive population of unbanked individuals, and a burgeoning e-commerce sector in countries like India, Indonesia, and Vietnam are the primary drivers of this growth.
How is regulation affecting the Buy Now Pay Later market?
Regulatory bodies in markets like the UK, Australia, and the US are increasingly viewing BNPL as a form of credit, leading to new requirements for credit checks and transparency. While this adds a layer of compliance cost, it is expected to stabilize the market, protect consumers from over-extension, and legitimize BNPL as a mainstream financial product.
Who are the target demographics for BNPL services?
Millennials and Generation Z are the primary users of BNPL, drawn to the interest-free installment models and the transparency of the payment terms. However, there is an increasing adoption rate among Generation X as BNPL expands into high-ticket categories like travel, healthcare, and home improvement.
What are the main risks associated with the BNPL business model?
The primary risks include rising credit default rates during economic downturns, high customer acquisition costs, and the impact of rising interest rates on funding liquidity. Additionally, intense competition is leading to margin compression, forcing providers to seek alternative revenue streams such as marketing fees and data insights.
Author
R
Ram Krishnan is a Manger Industry Services Research with 7+ years of experience in the Industry Services Industry. He specializes in industrial services market intelligence, service demand forecasting, competitive benchmarking, outsourcing and managed services analysis, operational performance assessment, market sizing, customer behavior analysis, pricing strategy evaluation, and industry trend forecasting across diverse service sectors. His analytical expertise transforms complex market data into actionable insights, enabling organizations to make strategic business decisions, identify growth opportunities, optimize operations, understand evolving market dynamics, and strengthen their competitive positioning in global industry services markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
