Burial Insurance Market
Burial Insurance Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711193 | Published On : October 16, 2026 |
Format : 


 | Author : Ram Krishnan
Burial Insurance Market Size
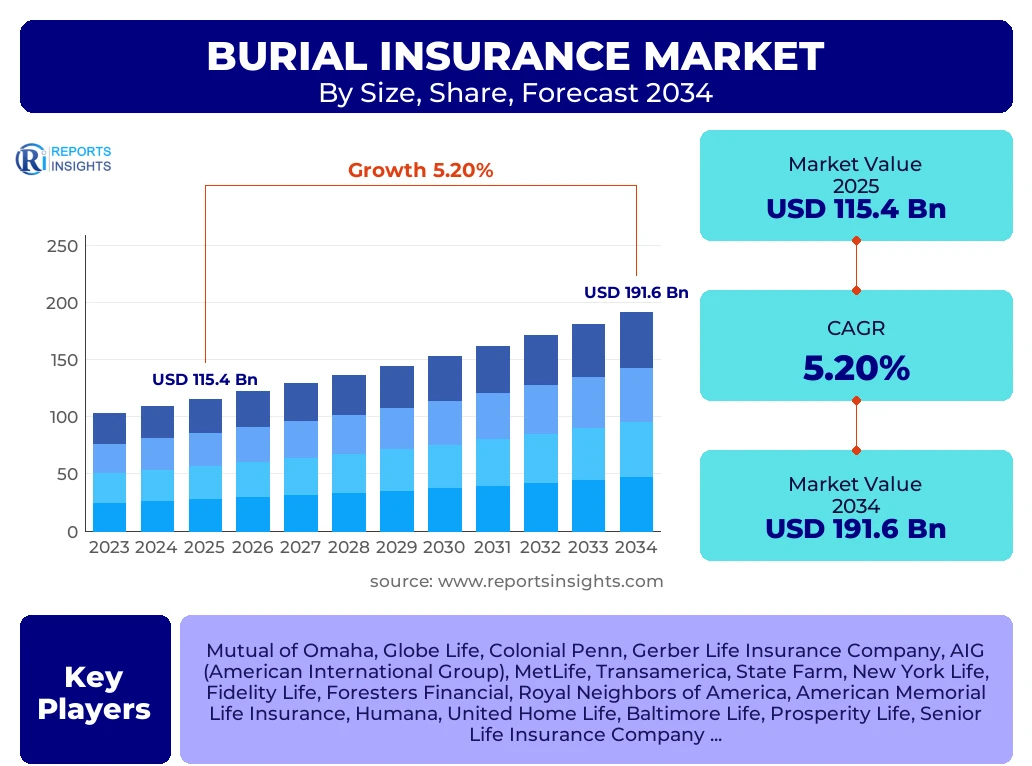
According to Reports Insights Consulting Pvt Ltd, The Burial Insurance Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.2% between 2025 and 2034. The market is estimated at USD 121.4 Billion in 2026 and is projected to reach USD 191.6 Billion by the end of the forecast period in 2034.
Key Burial Insurance Market Trends & Insights
The burial insurance market, often referred to as final expense insurance, is undergoing a significant transformation driven by demographic shifts and technological integration. As the global population ages, particularly in developed regions like North America and Europe, the demand for simplified issue and guaranteed issue life insurance products has surged. Consumers are increasingly seeking financial products that provide peace of mind without the rigors of traditional medical examinations. Furthermore, the integration of digital sales channels and AI-driven underwriting is streamlining the application process, making these products more accessible to a broader demographic. Market benchmarking reveals that companies focusing on transparent pricing and rapid claims processing are gaining a competitive edge, as beneficiaries prioritize ease of use during sensitive times.
- North America remains the largest regional market due to high funeral costs and a mature insurance infrastructure.
- Asia Pacific is identified as the fastest-growing region, fueled by an aging population in Japan and China and rising middle-class disposable income.
- The simplified issue segment holds the largest market share as it balances affordable premiums with relatively easy qualification standards.
- The direct-to-consumer digital segment is the fastest-growing distribution channel, reflecting a shift in how seniors interact with financial services.
Key Takeaways Burial Insurance Market Size & Forecast
The burial insurance market is characterized by steady, recession-resistant growth as end-of-life expenses remain a non-discretionary concern for most households. Analysts observe that the market is shifting from traditional agent-based models to hybrid digital platforms. The forecast period (2025–2034) suggests that while the United States will lead in terms of total market value, emerging economies in Southeast Asia and Latin America will present the most significant untapped opportunities for multi-national insurance carriers. Innovation in product bundling, such as combining burial coverage with legal or estate planning services, is expected to drive higher policy retention rates and attract a younger demographic of planners.
- The United States is the leading country in the global burial insurance market, driven by a cultural emphasis on independent financial planning for end-of-life costs.
- Rising funeral and cremation costs globally are the primary catalysts for market expansion, with costs in some urban centers increasing by over 20% in the last decade.
- Guaranteed acceptance policies are seeing high volume growth among the 70+ age demographic despite higher premium-to-payout ratios.
- Strategic partnerships between insurance providers and funeral home associations are becoming a dominant market strategy to capture customers at the point of need.
Burial Insurance Market Drivers Analysis
The primary driver for the burial insurance market is the consistent escalation of funeral-related expenses, which often exceed the immediate liquid assets of average households. In many developed nations, the cost of a traditional burial now rivals the cost of a mid-sized vehicle, necessitating dedicated financial planning. Additionally, the global demographic "silver tsunami" ensures a growing pool of potential customers who are increasingly aware of the financial burden their passing may place on surviving family members. This psychological shift toward proactive legacy planning is bolstered by more aggressive marketing from insurance providers who have rebranded burial insurance as a compassionate final gift to one's family.
Furthermore, the simplification of the underwriting process has removed significant barriers to entry. Traditional life insurance often requires invasive medical exams that discourage older or less healthy individuals. Burial insurance, specifically guaranteed issue products, provides a path to coverage regardless of health status, which has expanded the addressable market to include millions of individuals who were previously considered uninsurable. The rise of digital platforms has also lowered the cost of acquisition for insurers, allowing them to offer more competitive rates and reach rural populations that were previously underserved by local agents.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Escalating Funeral and Cremation Costs | +1.8% | Global (High in North America) | 2025 - 2034 |
| Rapidly Aging Global Population | +1.5% | Europe, Japan, China | 2025 - 2034 |
| Simplified/Guaranteed Issue Underwriting | +1.2% | United States, United Kingdom | 2025 - 2030 |
| Digital Transformation in Distribution | +0.7% | Emerging Markets | 2026 - 2034 |
Burial Insurance Market Restraints Analysis
Despite the positive growth trajectory, the burial insurance market faces challenges related to high premium costs relative to the actual death benefit. For many low-income individuals, the monthly premiums required for a guaranteed issue policy can be prohibitive, especially when compared to the total payout which often ranges from $5,000 to $25,000. This perceived lack of value can lead to high lapse rates if economic conditions tighten, as policyholders may prioritize immediate needs like food or medication over long-term insurance premiums. Additionally, the market is frequently subject to scrutiny regarding "predatory" marketing practices, which can lead to stricter regulations and increased compliance costs for providers.
Another significant restraint is the increasing popularity of lower-cost alternatives, such as pre-paid funeral plans directly with funeral homes or the shift toward direct cremation, which is significantly cheaper than traditional burial. As cultural preferences evolve away from elaborate ceremonies, the perceived need for high-value burial insurance policies may diminish in certain segments. Regulatory hurdles in various jurisdictions also limit the ability of insurers to offer certain types of modified death benefits, potentially stifling product innovation and cross-border expansion.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Premiums vs. Benefit Value | -0.9% | Low-income demographics globally | Ongoing |
| Rise of Direct Cremation Alternatives | -0.6% | Western Europe, North America | 2025 - 2034 |
| Increased Regulatory Scrutiny | -0.4% | United States, Australia | 2025 - 2028 |
Burial Insurance Market Opportunities Analysis
The convergence of InsurTech and traditional burial insurance presents a massive opportunity for market expansion. By leveraging big data and predictive analytics, insurers can more accurately price risk for older demographics, potentially lowering premiums for a subset of the population and increasing market penetration. There is also a significant opportunity in the "Middle Market" segment—individuals who have some savings but not enough to cover all final expenses. Products tailored to this group that offer flexible payment terms or increasing benefits to combat inflation could see substantial uptake.
Geographic expansion into emerging markets remains a high-potential opportunity. In regions like Latin America and parts of Southeast Asia, traditional family-funded burial customs are being replaced by formal financial products as urbanization and nuclear family structures become more common. Partnering with local banks and telecommunications companies to offer micro-insurance burial products could unlock access to millions of new customers. Furthermore, the integration of "living benefits," such as access to terminal illness riders, can make burial insurance policies more attractive to consumers who are concerned about late-life care costs as well as funeral expenses.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| InsurTech and AI-driven Risk Assessment | +1.1% | Global | 2026 - 2034 |
| Expansion into Emerging Markets (APAC/LATAM) | +1.4% | Brazil, India, Indonesia | 2027 - 2034 |
| Product Bundling with Living Benefits | +0.8% | North America, Europe | 2025 - 2030 |
Burial Insurance Market Challenges Impact Analysis
The burial insurance industry faces an ongoing challenge regarding consumer trust and reputation management. Due to the historical presence of high-pressure sales tactics and complex policy terms, many consumers remain skeptical of the product's value. Maintaining a positive brand image while navigating the sensitive nature of end-of-life planning requires a delicate balance that not all companies manage effectively. Furthermore, the industry is highly fragmented, with numerous small and regional players competing on price, which can lead to margin erosion and limited capital for technological investment.
Operational challenges also arise from the need to manage a high volume of small-value claims. The administrative cost of processing a $10,000 burial claim can be similar to that of a $500,000 life insurance claim, making efficiency paramount. Inflation also poses a dual threat: it increases the cost of funerals, potentially making existing policies inadequate, and it increases the operational costs for insurers. Companies must find ways to offer inflation-protected policies without pricing themselves out of the market for their core demographic.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Consumer Skepticism and Brand Trust | -0.5% | Global | 2025 - 2034 |
| High Administrative Costs for Small Claims | -0.4% | All Insurance Carriers | Ongoing |
| Inflationary Pressures on Operational Margins | -0.3% | Global Economy | 2025 - 2027 |
Burial Insurance Market - Updated Report Scope
This report provides a comprehensive analysis of the global burial insurance landscape, covering historical data from 2020 to 2024 and providing detailed forecasts through 2034. The scope includes an in-depth evaluation of policy types, distribution channels, and demographic trends across six major geographic regions. Our methodology integrates primary interviews with industry executives and secondary data from national census bureaus and funeral industry associations to ensure a robust and accurate market outlook.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 115.4 Billion |
| Market Forecast in 2034 | USD 191.6 Billion |
| Growth Rate | 5.2% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Mutual of Omaha, Globe Life, Colonial Penn, Gerber Life Insurance Company, AIG (American International Group), MetLife, Transamerica, State Farm, New York Life, Fidelity Life, Foresters Financial, Royal Neighbors of America, American Memorial Life Insurance, Humana, United Home Life, Baltimore Life, Prosperity Life, Senior Life Insurance Company, Liberty Bankers Life, Sentinel Security Life. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The burial insurance market is segmented primarily by the nature of the death benefit and the underwriting process. Level death benefit policies are the most sought-after as they provide full coverage from day one, typically requiring the applicant to answer a few health questions. In contrast, graded and modified death benefits are designed for higher-risk individuals, where the full benefit is only payable after the policy has been in force for a specific period, usually two years. Segmentation by age is also crucial, with the 60-75 age bracket representing the peak period for policy acquisition as individuals transition into retirement and focus on estate planning.
- By Type: Includes Level Death Benefit (full immediate coverage), Graded Death Benefit (partial coverage in early years), and Guaranteed Issue (no health questions).
- By Distribution Channel: Analyzes the shift from traditional face-to-face agent interactions to sophisticated online portals and tele-sales.
- By Policy Size: Segments coverage amounts ranging from micro-policies (under $5,000) to comprehensive final expense plans (up to $50,000).
- By Demographic: Focuses on age-specific needs and socio-economic factors influencing purchase decisions.
Regional Highlights
- North America: The largest market share holder, dominated by the United States where burial costs are among the highest globally and insurance penetration in the senior segment is very high.
- Asia Pacific: The fastest-growing region, with China, Japan, and India seeing a surge in demand due to aging populations and the gradual erosion of traditional multi-generational support systems.
- Europe: A mature market with steady growth, characterized by strong regulatory frameworks and a high prevalence of pre-paid funeral plans that compete with insurance products.
- Latin America: An emerging market with significant potential in countries like Brazil and Mexico, where a growing middle class is seeking formal financial security products.
- Middle East and Africa: A developing segment where market growth is tied to increasing urbanization and the introduction of Sharia-compliant insurance products (Takaful).

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Burial Insurance Market.- Mutual of Omaha
- Globe Life
- Colonial Penn
- Gerber Life Insurance Company
- AIG (American International Group)
- MetLife
- Transamerica
- State Farm
- New York Life
- Fidelity Life
- Foresters Financial
- Royal Neighbors of America
- American Memorial Life Insurance
- Humana
- United Home Life
- Baltimore Life
- Prosperity Life
- Senior Life Insurance Company
- Liberty Bankers Life
- Sentinel Security Life
Frequently Asked Questions
What is the main difference between burial insurance and standard life insurance?
Burial insurance is a type of whole life insurance with a smaller death benefit, usually between $5,000 and $25,000, designed specifically to cover funeral costs. Unlike standard life insurance, it often features simplified underwriting with no medical exam and is targeted at older demographics who may not qualify for traditional policies.
How has the rise of cremation affected the burial insurance market?
The shift toward cremation, which is generally less expensive than traditional burial, has led to the introduction of lower-value policies. While this could potentially lower the average premium per policy, it has expanded the market to a broader range of income levels who see cremation insurance as a more affordable way to handle final expenses.
Are premiums for burial insurance fixed for life?
Most burial insurance policies are "whole life" products, meaning the premiums are locked in at the time of purchase and do not increase as the policyholder ages, provided the premiums are paid on time. This stability is a key selling point for seniors on fixed incomes.
What is the significance of the "two-year waiting period" in some policies?
This is common in "guaranteed issue" policies. Because the insurer takes on high risk by not asking health questions, they often implement a two-year period where, if the insured dies of natural causes, the beneficiary only receives a return of premiums plus interest rather than the full death benefit.
Which region offers the most significant growth opportunity for insurers?
While North America is currently the largest, the Asia Pacific region offers the highest growth potential due to its massive, aging population and the rapid modernization of its financial services sector, particularly in countries like China and India.
Author
R
Ram Krishnan is a Manger Industry Services Research with 7+ years of experience in the Industry Services Industry. He specializes in industrial services market intelligence, service demand forecasting, competitive benchmarking, outsourcing and managed services analysis, operational performance assessment, market sizing, customer behavior analysis, pricing strategy evaluation, and industry trend forecasting across diverse service sectors. His analytical expertise transforms complex market data into actionable insights, enabling organizations to make strategic business decisions, identify growth opportunities, optimize operations, understand evolving market dynamics, and strengthen their competitive positioning in global industry services markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
