Branded Generics Market
Branded Generics Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711789 | Published On : November 17, 2026 |
Format : 


 | Author : Erika Grotto
Branded Generics Market Size
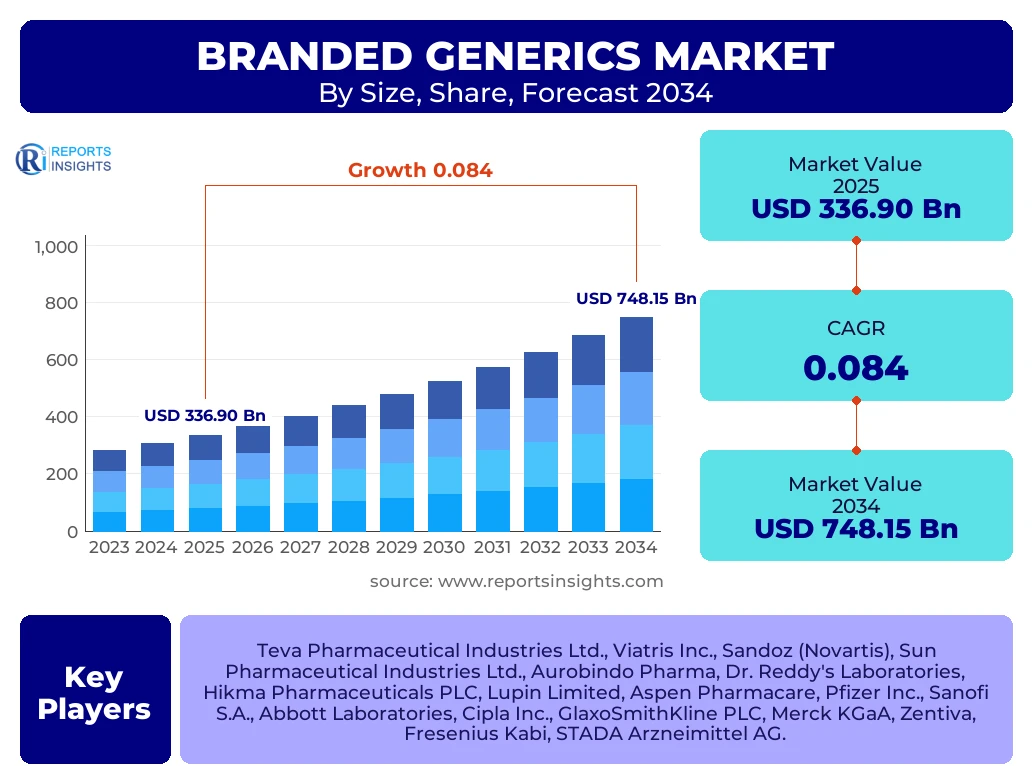
According to Reports Insights Consulting Pvt Ltd, The Branded Generics Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.4% between 2025 and 2034. The market is estimated at USD 365.20 Billion in 2026 and is projected to reach USD 748.15 Billion by the end of the forecast period in 2034.
Key Branded Generics Market Trends & Insights
The global pharmaceutical landscape is witnessing a structural shift as patent cliffs for high-value blockbuster drugs approach, creating a massive vacuum for branded generic alternatives. Market participants are increasingly focusing on therapeutic areas with high unmet needs, such as oncology and autoimmune disorders. In emerging economies, particularly across the Asia-Pacific region, branded generics are gaining traction due to a combination of rising healthcare expenditures and a growing middle-class population that demands quality-assured medication at a lower cost than innovator brands. Furthermore, the integration of digital health technologies and enhanced supply chain transparency is allowing manufacturers to establish stronger brand loyalty even within the generic segment, effectively bridging the gap between high-cost originals and low-cost unbranded commodities.
- Largest Region: North America remains the largest market by value, driven by high healthcare spending and a robust regulatory framework.
- Fastest Growing Region: Asia-Pacific is the fastest-growing region, fueled by massive population bases in India and China and expanding insurance coverage.
- Largest Segment by Therapeutic Area: Cardiovascular diseases and Oncology represent the largest shares due to the chronic nature of these conditions.
- Leading Distribution Channel: Retail Pharmacies currently hold the dominant market share as primary points of drug dispensing for outpatient care.
Key Takeaways Branded Generics Market Size & Forecast
The branded generics market is characterized by a high degree of fragmentation but is gradually consolidating as large-scale players acquire niche regional manufacturers to expand their portfolios. Forecasts indicate that the oncology and metabolic disorder segments will provide the most significant growth opportunities through 2034. Institutional buyers and government-led healthcare programs are shifting their procurement strategies toward branded generics to optimize budgets without compromising clinical outcomes. Strategic alliances between local manufacturers and global pharmaceutical giants are expected to redefine market dynamics, especially in the Latin American and Middle Eastern markets where local production incentives are high.
- Market Valuation: The total market value is set to more than double within the next decade, highlighting the increasing reliance on cost-effective therapeutic solutions.
- Emerging Hubs: India and Brazil are emerging as critical manufacturing hubs for export-quality branded generics.
- Therapeutic Shift: A significant migration from primary care focus to specialty care branded generics is observed in developed economies.
- Regulatory Influence: Harmonization of regulatory standards across borders is facilitating faster approvals for complex branded generics.
Branded Generics Market Drivers Analysis
The primary catalyst for the branded generics market is the escalating cost of healthcare globally, which forces both governments and private payers to seek more affordable alternatives to expensive innovator drugs. As patents for major biologic and chemical entities expire, branded generics provide a reliable middle ground, offering the trust of a brand name with the price advantage of a generic. Additionally, the prevalence of chronic diseases like diabetes and hypertension necessitates long-term medication, where branded generics become the most sustainable option for patients and healthcare systems alike.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Patent Expiration of Blockbuster Drugs | +3.2% | United States, Germany, Japan | 2025 - 2030 |
| Rising Chronic Disease Prevalence | +2.5% | Global | 2025 - 2034 |
| Government Cost-Containment Policies | +1.8% | European Union, China, Brazil | 2026 - 2032 |
| Expansion of Healthcare Access in APAC | +1.2% | India, Indonesia, Vietnam | 2025 - 2034 |
Branded Generics Market Restraints Analysis
Despite robust growth, the market faces significant headwinds from intense price competition and the presence of unbranded generics which often undercut branded options on price. Regulatory hurdles remain a challenge, particularly for complex generics where proving bioequivalence is more difficult and costly. Furthermore, the volatility in raw material costs and supply chain disruptions can impact the profit margins of manufacturers, especially in regions heavily dependent on imported Active Pharmaceutical Ingredients (APIs).
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Bioequivalence Regulations | -1.5% | North America, European Union | 2025 - 2028 |
| Intense Price Erosion | -1.2% | India, United States | Continuous |
Branded Generics Market Opportunities Analysis
The rise of specialty generics and biosimilars represents the most lucrative opportunity for market players. As healthcare providers look for high-efficacy treatments for complex conditions like rheumatoid arthritis and various cancers, branded generics in these specialized fields are seeing higher margins than traditional primary care drugs. Additionally, the digital transformation of pharmacies and the growth of e-commerce platforms provide new avenues for direct-to-consumer engagement, allowing brands to build direct trust and loyalty with patients in emerging markets.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Specialty Generics & Biosimilars | +4.1% | United States, South Korea, EU | 2026 - 2034 |
| Digital Pharmacy Growth | +1.5% | India, Southeast Asia | 2025 - 2030 |
Branded Generics Market Challenges Impact Analysis
Manufacturers are currently grappling with the challenge of differentiating their products in a saturated market where consumer perception often struggles to distinguish between branded and unbranded generics. Maintaining high quality-control standards across global manufacturing sites while keeping costs low is an ongoing struggle. Additionally, intellectual property litigation from innovator companies can delay market entry, resulting in lost revenue opportunities during the most profitable phases of a product’s lifecycle.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| IP Litigation & Legal Barriers | -1.1% | United States, Europe | 2025 - 2034 |
| API Supply Chain Vulnerability | -0.8% | Global | Short to Medium Term |
Branded Generics Market - Updated Report Scope
This report provides a granular analysis of the global branded generics market, covering technological advancements, regulatory shifts, and competitive strategies across five major geographic regions. It evaluates the impact of patent expirations and examines the growth of specialty generics in high-growth therapeutic areas. The scope includes an assessment of various distribution channels and the changing dynamics of patient and provider drug selection processes.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 336.90 Billion |
| Market Forecast in 2034 | USD 748.15 Billion |
| Growth Rate | 8.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Teva Pharmaceutical Industries Ltd., Viatris Inc., Sandoz (Novartis), Sun Pharmaceutical Industries Ltd., Aurobindo Pharma, Dr. Reddy's Laboratories, Hikma Pharmaceuticals PLC, Lupin Limited, Aspen Pharmacare, Pfizer Inc., Sanofi S.A., Abbott Laboratories, Cipla Inc., GlaxoSmithKline PLC, Merck KGaA, Zentiva, Fresenius Kabi, STADA Arzneimittel AG. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The therapeutic area segment is the most significant differentiator in the branded generics market. Oncology is currently witnessing the most rapid expansion as high-cost specialty biologics lose patent protection, allowing branded generic versions to enter the market at a significant discount. Cardiovascular diseases remain a steady and large segment due to the perpetual demand for maintenance medications in aging populations. The infectious disease segment is also seeing renewed interest, particularly in developing regions where affordable access to high-quality antibiotics and antivirals is a public health priority.
In terms of distribution, retail pharmacies continue to hold the majority share as they are the primary point of contact for the largest patient base—those with chronic conditions requiring regular refills. However, online pharmacies are the fastest-growing sub-segment, driven by consumer convenience and the digitalization of prescription management. Hospital pharmacies play a critical role in the parenteral and specialty generic segments, where administration typically occurs within a clinical setting.
The route of administration is dominated by oral medications due to their ease of use and high patient compliance. However, the parenteral segment is growing in value, particularly for oncology and autoimmune therapies that require injection or infusion. Topical branded generics for dermatological conditions are also seeing steady growth as consumers seek trusted brand names for skin-related treatments over-the-counter.
- Therapeutic Area:
- Oncology: Fastest growing due to specialty drug patent expirations.
- Cardiovascular: Largest volume due to high prevalence of heart disease.
- Diabetes: Driven by the global epidemic of metabolic disorders.
- Neurology: Increasing demand for CNS-related generic treatments.
- Infectious Diseases: Critical in emerging markets and for hospital-acquired infections.
- Distribution Channel:
- Hospital Pharmacies: Key for inpatient treatments and specialty medications.
- Retail Pharmacies: The primary outlet for chronic disease management.
- Online Pharmacies: Rapidly expanding through digital health platforms.
- Route of Administration:
- Oral: Most preferred for patient convenience and adherence.
- Parenteral: Essential for biologics and acute care settings.
- Topical: Gaining share in dermatology and pain management.
Regional Highlights
North America currently leads the global market in terms of revenue, primarily due to the high costs of healthcare and the rapid adoption of branded generics by insurance providers to mitigate specialty drug expenses. The United States market is particularly robust, with a sophisticated regulatory environment that facilitates the entry of complex generics. Europe follows closely, with countries like Germany, the UK, and France implementing stringent cost-containment measures that favor the prescription of branded generics over more expensive innovator brands.
The Asia-Pacific region is the most dynamic, projected to exhibit the highest growth rate during the forecast period. China and India are at the forefront of this growth, not only as massive consumer markets but also as the world's primary manufacturers of generic drugs. Economic development, improvements in healthcare infrastructure, and government initiatives to provide affordable medicine to large populations are the primary drivers in this region. Latin America, led by Brazil and Mexico, is also showing significant potential as local manufacturing capabilities improve and regulatory frameworks become more aligned with international standards.
- North America: Largest market share, driven by favorable reimbursement policies and high per-capita healthcare spending.
- Europe: Mature market with strong growth in biosimilars and specialty branded generics.
- Asia-Pacific: Fastest growing region; home to major manufacturing hubs and a rapidly expanding patient base.
- Latin America: Significant growth opportunities in Brazil due to government-sponsored healthcare programs.
- Middle East & Africa: Emerging market with increasing focus on local production and reducing dependency on expensive imports.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Branded Generics Market.- Teva Pharmaceutical Industries Ltd.
- Viatris Inc.
- Sandoz (A Division of Novartis)
- Sun Pharmaceutical Industries Ltd.
- Aurobindo Pharma
- Dr. Reddy's Laboratories
- Hikma Pharmaceuticals PLC
- Lupin Limited
- Aspen Pharmacare
- Pfizer Inc.
- Sanofi S.A.
- Abbott Laboratories
- Cipla Inc.
- GlaxoSmithKline PLC
- Merck KGaA
- Zentiva
- Fresenius Kabi
- STADA Arzneimittel AG
- Apotex Inc.
- Torrent Pharmaceuticals Ltd.
Frequently Asked Questions
What is the primary difference between a branded generic and a standard generic drug?
A branded generic is a generic drug that has been given a proprietary name by the manufacturer, often to build brand equity and trust. While both contain the same active ingredients as the innovator drug, branded generics are marketed with a brand identity, whereas standard generics are usually referred to by their chemical or generic name.
Which therapeutic area is expected to see the highest growth in the branded generics market?
The oncology segment is expected to witness the highest growth rate. This is due to the increasing number of oncology drugs losing patent protection and the subsequent market entry of high-value branded generic and biosimilar alternatives that offer substantial cost savings for complex cancer treatments.
How do regional regulations impact the branded generics market?
Regulations vary significantly; in the US, the FDA requires rigorous bioequivalence studies, while the EU has harmonized procedures through the EMA. Emerging markets often have localized requirements that may favor domestic manufacturers, but international harmonization is increasingly making it easier for global players to enter multiple regions simultaneously.
What role do online pharmacies play in the growth of this market?
Online pharmacies are a major growth driver, particularly in the Asia-Pacific region. They enhance accessibility for patients in remote areas, provide competitive pricing, and offer the convenience of home delivery, which increases the overall penetration and adoption of branded generic medications.
Why is North America the largest market for branded generics despite being a high-cost region?
North America's dominance is attributed to its massive pharmaceutical market size and the proactive shift by private and public insurers toward branded generics to lower overall healthcare costs. The presence of leading global manufacturers and a well-defined pathway for complex generic approvals also support its leading position.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
