3D Printing Medical Devices Market
3D Printing Medical Devices Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711595 | Published On : November 07, 2026 |
Format : 


 | Author : Erika Grotto
3D Printing Medical Devices Market Size
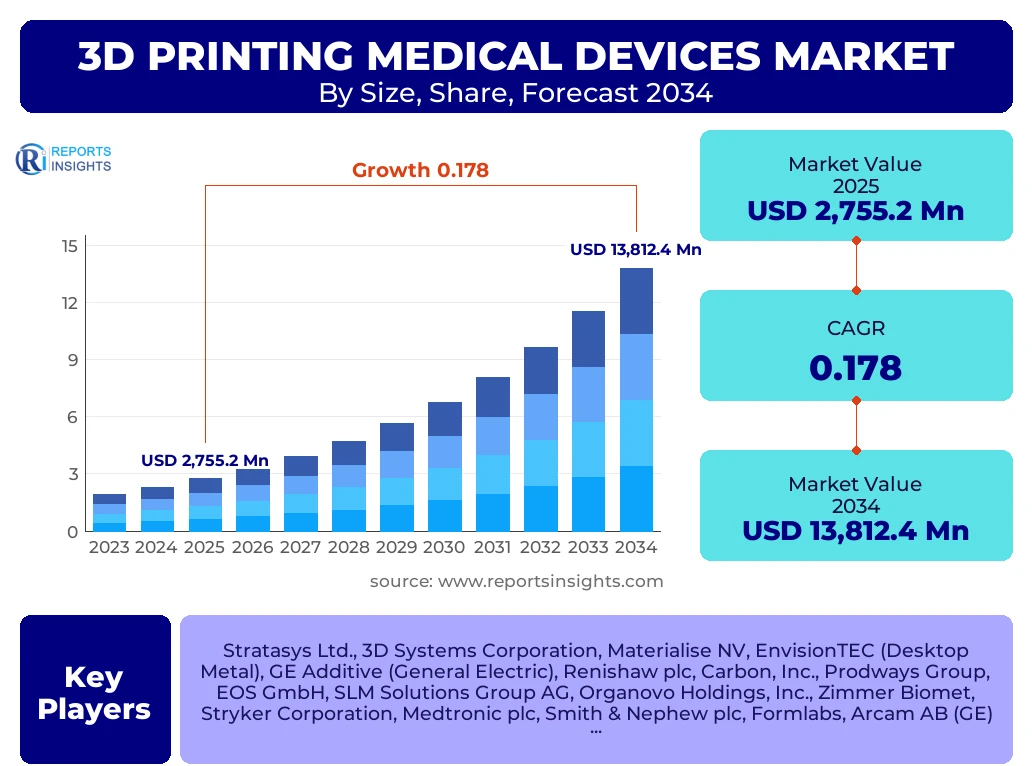
According to Reports Insights Consulting Pvt Ltd, The 3D Printing Medical Devices Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 17.8% between 2025 and 2034. The market is estimated at USD 3,245.6 Million in 2026 and is projected to reach USD 13,812.4 Million by the end of the forecast period in 2034.
Key 3D Printing Medical Devices Market Trends & Insights
The global landscape for medical additive manufacturing is undergoing a paradigm shift, moving from centralized production to decentralized, point-of-care fabrication. This transition is fueled by the integration of artificial intelligence in design software, allowing for the rapid generation of patient-specific anatomical models and implants. Stakeholders are increasingly focusing on biocompatible polymers and advanced metal alloys to enhance the longevity and osseointegration of orthopedic and dental devices. Furthermore, the rise of bioprinting—the layer-by-layer deposition of biological materials—is positioning the market for long-term growth in regenerative medicine and pharmaceutical testing applications. Competitive benchmarking reveals that leading enterprises are prioritizing strategic partnerships with healthcare providers to streamline the digital workflow from clinical imaging to final sterilized product.
- Largest Region: North America remains the dominant revenue contributor, accounting for over 40% of the total market share, driven by high healthcare expenditure and early adoption of advanced surgical techniques.
- Fastest Growing Region: Asia-Pacific is anticipated to exhibit the highest CAGR, propelled by expanding medical tourism in India and Thailand, alongside massive government investments in healthcare infrastructure in China.
- Leading Segment by Technology: Laser Beam Melting and Stereolithography currently hold the largest shares due to their precision and ability to process high-grade medical metals and resins.
- Leading Segment by Application: Orthopedic and dental applications represent the highest market value, utilized extensively for customized joint replacements and crowns.
Key Takeaways 3D Printing Medical Devices Market Size & Forecast
The trajectory of the 3D Printing Medical Devices market is fundamentally tied to the increasing clinical demand for personalized healthcare solutions that improve patient outcomes and reduce surgery times. Analysis of historical data and future projections indicates that the market is entering a phase of industrialization where quality control and standardized regulatory pathways (such as FDA Class II and III clearances) are becoming the primary focus for manufacturers. The forecasted growth is not merely a result of increased hardware sales but is significantly bolstered by recurring revenue from medical-grade materials and specialized clinical services. As hospitals continue to establish in-house 3D printing labs, the demand for user-friendly software and validated material-machine combinations is expected to soar, creating a robust ecosystem for both hardware providers and service bureaus.
- The United States leads the global market in terms of both technological innovation and the total volume of 3D-printed orthopedic implants used in clinical practice.
- The transition from traditional subtractive manufacturing to additive processes is reducing material waste by up to 70% in certain titanium implant production lines.
- Dental clinics are the most rapid adopters of tabletop 3D printing systems, significantly reducing the turnaround time for prosthetics from weeks to hours.
- Strategic focus on bioprinting and tissue engineering is attracting significant venture capital, particularly in Western Europe and the United States.
- Material costs remain a critical factor, with innovations in photopolymers and biocompatible resins expected to drive down the total cost of ownership for healthcare providers.
3D Printing Medical Devices Market Drivers Analysis
The acceleration of the 3D Printing Medical Devices market is primarily driven by the escalating global geriatric population and the subsequent rise in chronic conditions requiring surgical interventions. The ability to create complex, lightweight, and patient-specific geometries that are impossible to manufacture through traditional methods is a critical value proposition. Moreover, the reduction in surgical durations achieved through the use of 3D-printed surgical guides provides a significant economic incentive for hospitals, as it increases operating room throughput and reduces the risk of intraoperative complications.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Demand for Personalized Orthopedic Implants | +4.2% | Global (USA, Germany, Japan) | 2025-2034 |
| Integration of AI and Machine Learning in CAD Software | +3.5% | North America and Europe | 2026-2030 |
| Rising Prevalence of Dental Disorders | +3.1% | Asia-Pacific (China, India) | 2025-2034 |
| Shift Towards Point-of-Care Manufacturing | +2.8% | United Kingdom, USA | 2027-2034 |
3D Printing Medical Devices Market Restraints Analysis
Despite the technological advancements, the market faces significant hurdles related to the high initial capital investment required for industrial-grade printers and the stringent regulatory landscape. The process of certifying new materials for long-term implantation is both time-consuming and expensive, which can delay the commercialization of innovative products. Additionally, the lack of standardized quality assurance protocols across different 3D printing platforms poses a challenge for large-scale clinical adoption, particularly for life-critical Class III medical devices.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Specialized Biocompatible Materials | -2.4% | Emerging Economies | 2025-2029 |
| Stringent FDA/MDR Regulatory Approvals | -1.9% | USA, European Union | 2025-2034 |
| Scarcity of Skilled Additive Manufacturing Engineers | -1.5% | Global | 2025-2030 |
3D Printing Medical Devices Market Opportunities Analysis
The market is ripe with opportunities, particularly in the realm of bioprinting and the development of 4D printing technologies—where printed objects can change shape or function in response to environmental stimuli. Expanding the application of 3D printing into pharmaceutical manufacturing for personalized drug dosing and "polypills" presents a massive untapped market. Furthermore, the integration of 3D printing in pediatric healthcare for the creation of growth-accommodating implants provides a niche but high-value growth avenue for specialized medical device manufacturers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of 3D Printed Pharmacological Solutions | +3.8% | Europe and North America | 2028-2034 |
| Expansion into Veterinary Orthopedics | +1.5% | Australia, USA | 2026-2034 |
| Growth in Medical Tourism in Southeast Asia | +2.2% | Thailand, Malaysia, Singapore | 2025-2034 |
| Advancements in Organ-on-a-Chip Technology | +2.5% | Japan, Germany, USA | 2027-2034 |
3D Printing Medical Devices Market Challenges Impact Analysis
One of the foremost challenges is the protection of intellectual property and data security as digital design files are shared across global networks. Cybersecurity threats targeting medical device designs could lead to unauthorized modifications or counterfeiting. Furthermore, achieving consistent mechanical properties across different printing batches remains a technical hurdle that necessitates rigorous post-processing and validation, which adds to the total cost and complexity of the manufacturing cycle.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Intellectual Property and Digital File Security | -1.2% | Global | 2025-2034 |
| Post-Processing and Surface Finishing Limitations | -1.8% | Germany, USA, South Korea | 2025-2030 |
| Interoperability Between Imaging and CAD Systems | -0.9% | Global | 2025-2028 |
3D Printing Medical Devices Market - Updated Report Scope
The scope of this report encompasses a comprehensive analysis of the global 3D printing medical devices ecosystem, spanning hardware, software, materials, and specialized services. The research details the adoption rates of various additive technologies across orthopedic, dental, and cardiovascular clinical applications. By evaluating the strategic maneuvers of key industry players and the evolving regulatory frameworks in major jurisdictions, the report provides a granular view of the market's transition from prototype development to full-scale clinical manufacturing. This analysis includes value chain mapping, competitive landscape benchmarking, and detailed regional forecasts to assist stakeholders in identifying high-growth investment pockets.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 2,755.2 Million |
| Market Forecast in 2034 | USD 13,812.4 Million |
| Growth Rate | 17.8% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Stratasys Ltd., 3D Systems Corporation, Materialise NV, EnvisionTEC (Desktop Metal), GE Additive (General Electric), Renishaw plc, Carbon, Inc., Prodways Group, EOS GmbH, SLM Solutions Group AG, Organovo Holdings, Inc., Zimmer Biomet, Stryker Corporation, Medtronic plc, Smith & Nephew plc, Formlabs, Arcam AB (GE), Beijing Tiertime Technology Co. Ltd. |
| Regions Covered | North America (USA, Canada), Europe (Germany, UK, France, Italy, Spain), Asia Pacific (China, Japan, India, South Korea, Australia), Latin America (Brazil, Mexico), Middle East, and Africa (Saudi Arabia, UAE, South Africa) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The 3D printing medical devices market is segmented based on component, technology, application, and end-user, reflecting the diverse utility of additive manufacturing in modern medicine. The hardware segment remains a significant revenue driver as healthcare facilities upgrade to industrial-grade systems, while the software segment is witnessing rapid growth due to the need for advanced DICOM-to-STL conversion tools. Within applications, the orthopedic segment dominates due to the high volume of knee and hip replacements globally, whereas the dental segment shows the highest penetration rate of 3D printing technology for daily restorative procedures. Technology-wise, powder bed fusion methods like SLS and EBM are preferred for heavy-duty metal implants, while vat photopolymerization like SLA is the standard for high-detail anatomical models and surgical guides.
- By Component: Hardware, Materials (Plastic, Metal, Ceramic, Bio-inks), Software (Design, Simulation, Planning), Services (Maintenance, Training, Contract Manufacturing).
- By Technology: Stereolithography (SLA), Selective Laser Sintering (SLS), Fused Deposition Modeling (FDM), Electron Beam Melting (EBM), Laser Beam Melting (LBM), PolyJet / Inkjet 3D Printing.
- By Application: Orthopedic Implants, Dental Prosthetics, Cranio-maxillofacial Implants, Surgical Guides, Surgical Instruments, Hearing Aids, Tissue Engineering, Custom Prosthetics.
- By End-User: Hospitals and Surgical Centers, Dental Laboratories, Medical Research Organizations, Pharmaceutical Companies.
Regional Highlights
- North America: The largest market, led by the United States, characterized by high adoption of robotic-assisted surgeries and 3D-printed guides. The presence of major industry players like Stratasys and 3D Systems further solidifies its position.
- Europe: A significant hub for technological innovation, particularly in Germany and the UK. The European market is heavily influenced by strict Medical Device Regulations (MDR) which ensure high safety standards but require substantial compliance investment.
- Asia-Pacific: The fastest-growing region. China and Japan are investing heavily in domestic 3D printing capabilities to reduce reliance on imports. Growing healthcare access in India and Southeast Asia is driving the demand for cost-effective 3D-printed medical solutions.
- Latin America & MEA: These regions are seeing emerging growth, primarily focused on basic dental and prosthetic applications. Investments in specialized medical hubs in Dubai and Brazil are expected to accelerate regional adoption in the coming decade.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the 3D Printing Medical Devices Market.- Stratasys Ltd.
- 3D Systems Corporation
- Materialise NV
- EnvisionTEC (Desktop Metal)
- GE Additive
- Renishaw plc
- Carbon, Inc.
- Prodways Group
- EOS GmbH
- SLM Solutions Group AG
- Organovo Holdings, Inc.
- Zimmer Biomet
- Stryker Corporation
- Medtronic plc
- Smith & Nephew plc
- Formlabs
- Arcam AB
- Cellink AB (BICO Group)
- Desktop Health
- Oxford Performance Materials
Frequently Asked Questions
What is the current market size and growth outlook for 3D printing medical devices?
The market is valued at approximately USD 2,755.2 Million in 2025 and is expected to grow at a CAGR of 17.8%, reaching over USD 13.8 Billion by 2034. This growth is driven by the demand for personalized surgical solutions and technological advancements in materials.
Which technology is most widely used in medical 3D printing?
Laser Beam Melting (LBM) and Stereolithography (SLA) are the most prevalent. LBM is favored for metal implants due to its structural integrity, while SLA is the standard for high-precision anatomical models and dental prosthetics.
What are the primary applications of 3D printing in the healthcare sector?
The primary applications include orthopedic implants (hip, knee, spine), dental restorations (crowns, bridges), surgical guides that improve operative accuracy, and the production of customized hearing aids and prosthetics.
How is the regulatory environment impacting the market?
Regulatory bodies like the FDA and EMA are implementing stricter guidelines for 3D-printed devices to ensure patient safety. While these regulations can slow down the speed to market, they are essential for standardizing quality and fostering long-term clinical trust.
What role does bioprinting play in the future of this market?
Bioprinting is a high-growth segment focused on creating cellular structures and tissues. While largely in the research phase currently, it holds the potential to revolutionize organ transplants and pharmaceutical testing in the 2030-2040 decade.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
