Surgical Equipment Market
Surgical Equipment Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711000 | Published On : September 27, 2026 |
Format : 


 | Author : Erika Grotto
Surgical Equipment Market Size
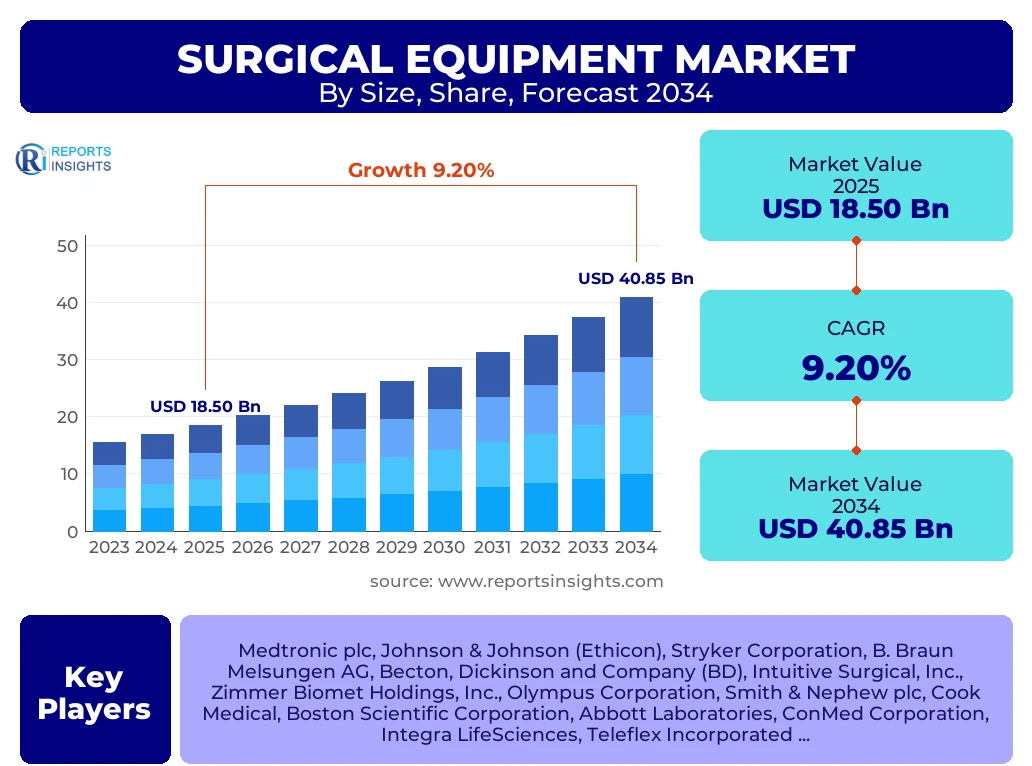
According to Reports Insights Consulting Pvt Ltd, The Surgical Equipment Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 9.2% between 2026 and 2034. The market is estimated at USD 20.21 Billion in 2026 and is projected to reach USD 40.85 Billion by the end of the forecast period in 2034.
Key Surgical Equipment Market Trends & Insights
The global landscape for surgical instruments is undergoing a paradigm shift driven by the convergence of digital technology and traditional mechanical engineering. Users and stakeholders are increasingly inquiring about the integration of artificial intelligence (AI) and robotic-assisted surgery (RAS) systems, which are redefining precision and patient outcomes. Regional insights indicate a heavy focus on the modernization of healthcare infrastructure in emerging economies, while mature markets are prioritizing cost-efficiency and the transition toward minimally invasive procedures. Competitive benchmarking reveals that market leaders are pivoting toward "smart" instruments that provide real-time feedback to surgeons, thereby reducing the margin of error during complex operations. The summary of findings suggests that the market is moving away from basic handheld tools toward sophisticated, energy-based, and automated solutions that cater to a high-volume surgical environment.
- North America remains the largest regional market due to high healthcare expenditure and early adoption of robotic surgical systems.
- The Asia-Pacific region is the fastest-growing market, propelled by expanding medical tourism and government initiatives to upgrade surgical facilities in China and India.
- Surgical sutures and staplers currently represent the largest segment in terms of market share, driven by their essential role in almost every surgical discipline.
- Robotic-assisted surgical instruments are the fastest-growing product sub-segment, reflecting the global trend toward minimally invasive surgery.
Key Takeaways Surgical Equipment Market Size & Forecast
Analysis of common user queries regarding the long-term outlook of the surgical equipment market highlights a strong focus on the sustainability of growth and the impact of outpatient surgical centers. Stakeholders are particularly concerned with how the shift toward ambulatory surgery centers (ASCs) will influence procurement patterns for handheld and electrosurgical instruments. The forecast indicates that while traditional hospitals remain the primary revenue generators, ASCs are becoming critical nodes for specialized orthopedic and ophthalmic surgeries. The market is expected to witness significant consolidation as major players acquire niche technology firms to bolster their portfolios in the digital surgery space. Overall, the market trajectory is steeply upward, supported by a growing geriatric population and a rising global burden of chronic diseases requiring surgical intervention.
- The United States is the leading country in value, supported by a robust reimbursement framework and a high concentration of medical technology innovators.
- The increasing prevalence of lifestyle-related diseases, such as cardiovascular disorders and obesity, is a primary driver for specialized surgical equipment demand.
- Technological convergence, specifically the blending of imaging and surgical tools (hybrid operating rooms), is becoming a standard in high-end medical facilities.
- Disposable surgical equipment is gaining traction over reusable variants due to rising concerns over hospital-acquired infections (HAIs) and the costs associated with sterilization.
Surgical Equipment Market Drivers Analysis
The growth of the surgical equipment market is fundamentally anchored by the global demographic shift toward an aging population, which inherently leads to a higher volume of surgical procedures such as joint replacements and cataract surgeries. Furthermore, the rapid advancement in minimally invasive surgery (MIS) techniques has reduced patient recovery times and hospital stays, making surgery a more viable option for a broader demographic. The continuous innovation in electrosurgical devices and the integration of high-definition visualization systems have also empowered surgeons to perform complex procedures with greater accuracy, thereby fueling market demand.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Aging Global Population and Chronic Disease Prevalence | +3.2% | Global (High in Japan & Germany) | 2025 - 2034 |
| Advancements in Robotic-Assisted Surgery (RAS) | +2.8% | North America & Western Europe | 2026 - 2032 |
| Expansion of Ambulatory Surgery Centers (ASCs) | +1.5% | United States & United Kingdom | 2025 - 2030 |
| Rise in Medical Tourism | +1.7% | Thailand, India, & Mexico | 2027 - 2034 |
Surgical Equipment Market Restraints Analysis
Despite the positive growth trajectory, the market faces significant headwinds from the high cost associated with advanced surgical systems, particularly robotic and automated platforms, which can limit adoption in budget-constrained healthcare settings. Additionally, stringent regulatory approval processes and the requirement for extensive clinical data can delay the market entry of new products. The global push for healthcare cost containment and value-based pricing models also puts pressure on manufacturers to lower equipment prices, potentially impacting profit margins across the industry.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Capital Investment for Advanced Systems | -1.8% | Developing Economies (Africa & SE Asia) | 2025 - 2034 |
| Strict Regulatory & Compliance Standards | -1.2% | European Union (MDR Compliance) | 2025 - 2028 |
| Shortage of Skilled Surgical Professionals | -0.9% | Global | 2026 - 2034 |
Surgical Equipment Market Opportunities Analysis
The integration of Artificial Intelligence (AI) and Machine Learning (ML) into surgical workflows presents a transformative opportunity for equipment manufacturers. These technologies can provide predictive analytics and real-time intraoperative guidance, significantly enhancing the value proposition of surgical tools. Furthermore, the untapped potential in emerging markets provides a fertile ground for market expansion, as governments in these regions increase their healthcare budgets and invest in specialized surgical centers. The development of portable and battery-operated surgical devices for use in remote or field settings also represents a growing niche market.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| AI Integration in Surgical Navigation Systems | +2.4% | Global (Tech-centric Markets) | 2026 - 2034 |
| Growth in Emerging Healthcare Infrastructure | +2.1% | China, Brazil, & Indonesia | 2025 - 2034 |
| Shift Toward Disposable Specialized Instruments | +1.3% | Global (Infection Control focus) | 2025 - 2030 |
Surgical Equipment Market Challenges Impact Analysis
One of the most pressing challenges is the disruption and volatility in the global medical device supply chain, which can affect the availability of raw materials and specialized electronic components. Additionally, the rapid pace of technological change creates a "training gap," where surgeons and theater staff must constantly be re-skilled to operate increasingly complex equipment safely. Cyber security also emerges as a critical challenge as surgical systems become more interconnected and reliant on digital networks, posing risks to patient data and system integrity.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Instability for Components | -1.4% | Global | 2025 - 2027 |
| Cybersecurity Vulnerabilities in Connected Devices | -0.7% | Developed Nations | 2026 - 2034 |
| Economic Inflation and Increased Raw Material Costs | -1.1% | Global | 2025 - 2028 |
Surgical Equipment Market - Updated Report Scope
This report provides a comprehensive examination of the surgical equipment market, encompassing a wide range of tools from traditional handheld instruments to advanced robotic systems. The scope includes a detailed analysis of market dynamics across various surgical specialties such as orthopedics, cardiology, and gynecology. The study evaluates the competitive landscape by profiling industry leaders and emerging innovators, while also analyzing the regulatory environment and reimbursement policies that shape market entry and product adoption across different geographies.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 18.50 Billion |
| Market Forecast in 2034 | USD 40.85 Billion |
| Growth Rate | 9.2% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Medtronic plc, Johnson & Johnson (Ethicon), Stryker Corporation, B. Braun Melsungen AG, Becton, Dickinson and Company (BD), Intuitive Surgical, Inc., Zimmer Biomet Holdings, Inc., Olympus Corporation, Smith & Nephew plc, Cook Medical, Boston Scientific Corporation, Abbott Laboratories, ConMed Corporation, Integra LifeSciences, Teleflex Incorporated, Getinge AB, Steris plc, Richard Wolf GmbH. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The surgical equipment market is segmented primarily by product type, category, application, and end-user, each reflecting distinct market dynamics and growth drivers. The product segmentation highlights the dominance of surgical sutures and staplers, while the category segment shows a significant shift toward disposable instruments due to hygiene protocols. Application-based segmentation reveals that orthopedic and cardiovascular surgeries are the largest contributors to revenue, whereas the end-user analysis underscores the growing importance of ambulatory surgery centers in the decentralized healthcare landscape.
- Handheld Surgical Instruments: This segment includes forceps, spatulas, retractors, and dilators, which remain the foundation of any surgical toolkit despite the rise of automation.
- Surgical Sutures & Staplers: This represents a high-volume segment, with constant innovation in bio-absorbable materials and ergonomic stapling devices.
- Electrosurgical Devices: These devices use electrical energy for cutting and coagulation, seeing high demand in minimally invasive procedures.
- Robotic Surgical Systems: The high-value segment characterized by rapid technological advancement and significant capital expenditure.
- Disposable vs. Reusable: The market is witnessing a transition where disposable instruments are preferred for high-risk procedures to eliminate sterilization costs and infection risks.
- Specialty Applications: Detailed analysis covers Orthopedics (highest volume), Cardiovascular (highest precision requirements), and Gynecology.
Regional Highlights
- North America: The largest market share holder, driven by the presence of major industry players, advanced healthcare infrastructure, and high rates of surgical procedures per capita. The United States leads in the adoption of robotic surgery systems.
- Europe: A mature market characterized by stringent regulatory standards (MDR) and a strong focus on cost-effectiveness. Germany, France, and the UK are the primary contributors, with a growing emphasis on minimally invasive techniques.
- Asia-Pacific: The fastest-growing region, fueled by massive investments in healthcare by China and India. Growing middle-class populations and expanding insurance coverage are driving the demand for quality surgical care.
- Latin America: Showing steady growth, particularly in Brazil and Mexico, as medical tourism for cosmetic and elective surgeries continues to rise.
- Middle East & Africa: A developing market with significant potential in the Gulf Cooperation Council (GCC) countries, where state-of-the-art hospitals are being built to reduce reliance on overseas medical travel.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Surgical Equipment Market. These companies are selected based on their market presence, product innovation, and strategic influence within the global surgical landscape.
- Medtronic plc
- Johnson & Johnson (Ethicon)
- Stryker Corporation
- B. Braun Melsungen AG
- Becton, Dickinson and Company (BD)
- Intuitive Surgical, Inc.
- Zimmer Biomet Holdings, Inc.
- Olympus Corporation
- Smith & Nephew plc
- Cook Medical
- Boston Scientific Corporation
- Abbott Laboratories
- ConMed Corporation
- Integra LifeSciences
- Teleflex Incorporated
- Getinge AB
- Steris plc
- Richard Wolf GmbH
Frequently Asked Questions
What is the projected market size of the Surgical Equipment Market by 2034?
The global Surgical Equipment Market is projected to reach approximately USD 40.85 Billion by 2034, growing at a steady CAGR of 9.2% from the base year 2025.
Which region currently dominates the Surgical Equipment Market?
North America currently dominates the market, accounting for the largest share due to advanced technological adoption, high healthcare spending, and a well-established regulatory framework.
What are the primary drivers of growth in this market?
Key drivers include an aging global population, the increasing prevalence of chronic diseases requiring surgery, and the rapid shift toward minimally invasive and robotic-assisted surgical procedures.
Who are the leading players in the surgical equipment industry?
Leading players include Medtronic, Johnson & Johnson, Stryker, Intuitive Surgical, and B. Braun, all of whom focus on innovation in surgical robotics and high-precision handheld instruments.
Why is there a shift from reusable to disposable surgical equipment?
The shift is primarily driven by the need to reduce hospital-acquired infections, eliminate the high costs and logistical challenges of sterilization, and ensure instrument performance consistency in every procedure.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted